Nubank intends to paint the U.S. banking system purple

Nubank has officially begun serving customers in the United States, rolling out an initial lineup built around high-yield savings, a no-fee credit card, and low-cost international transfers through its U.S. banking partner, Lead Bank.

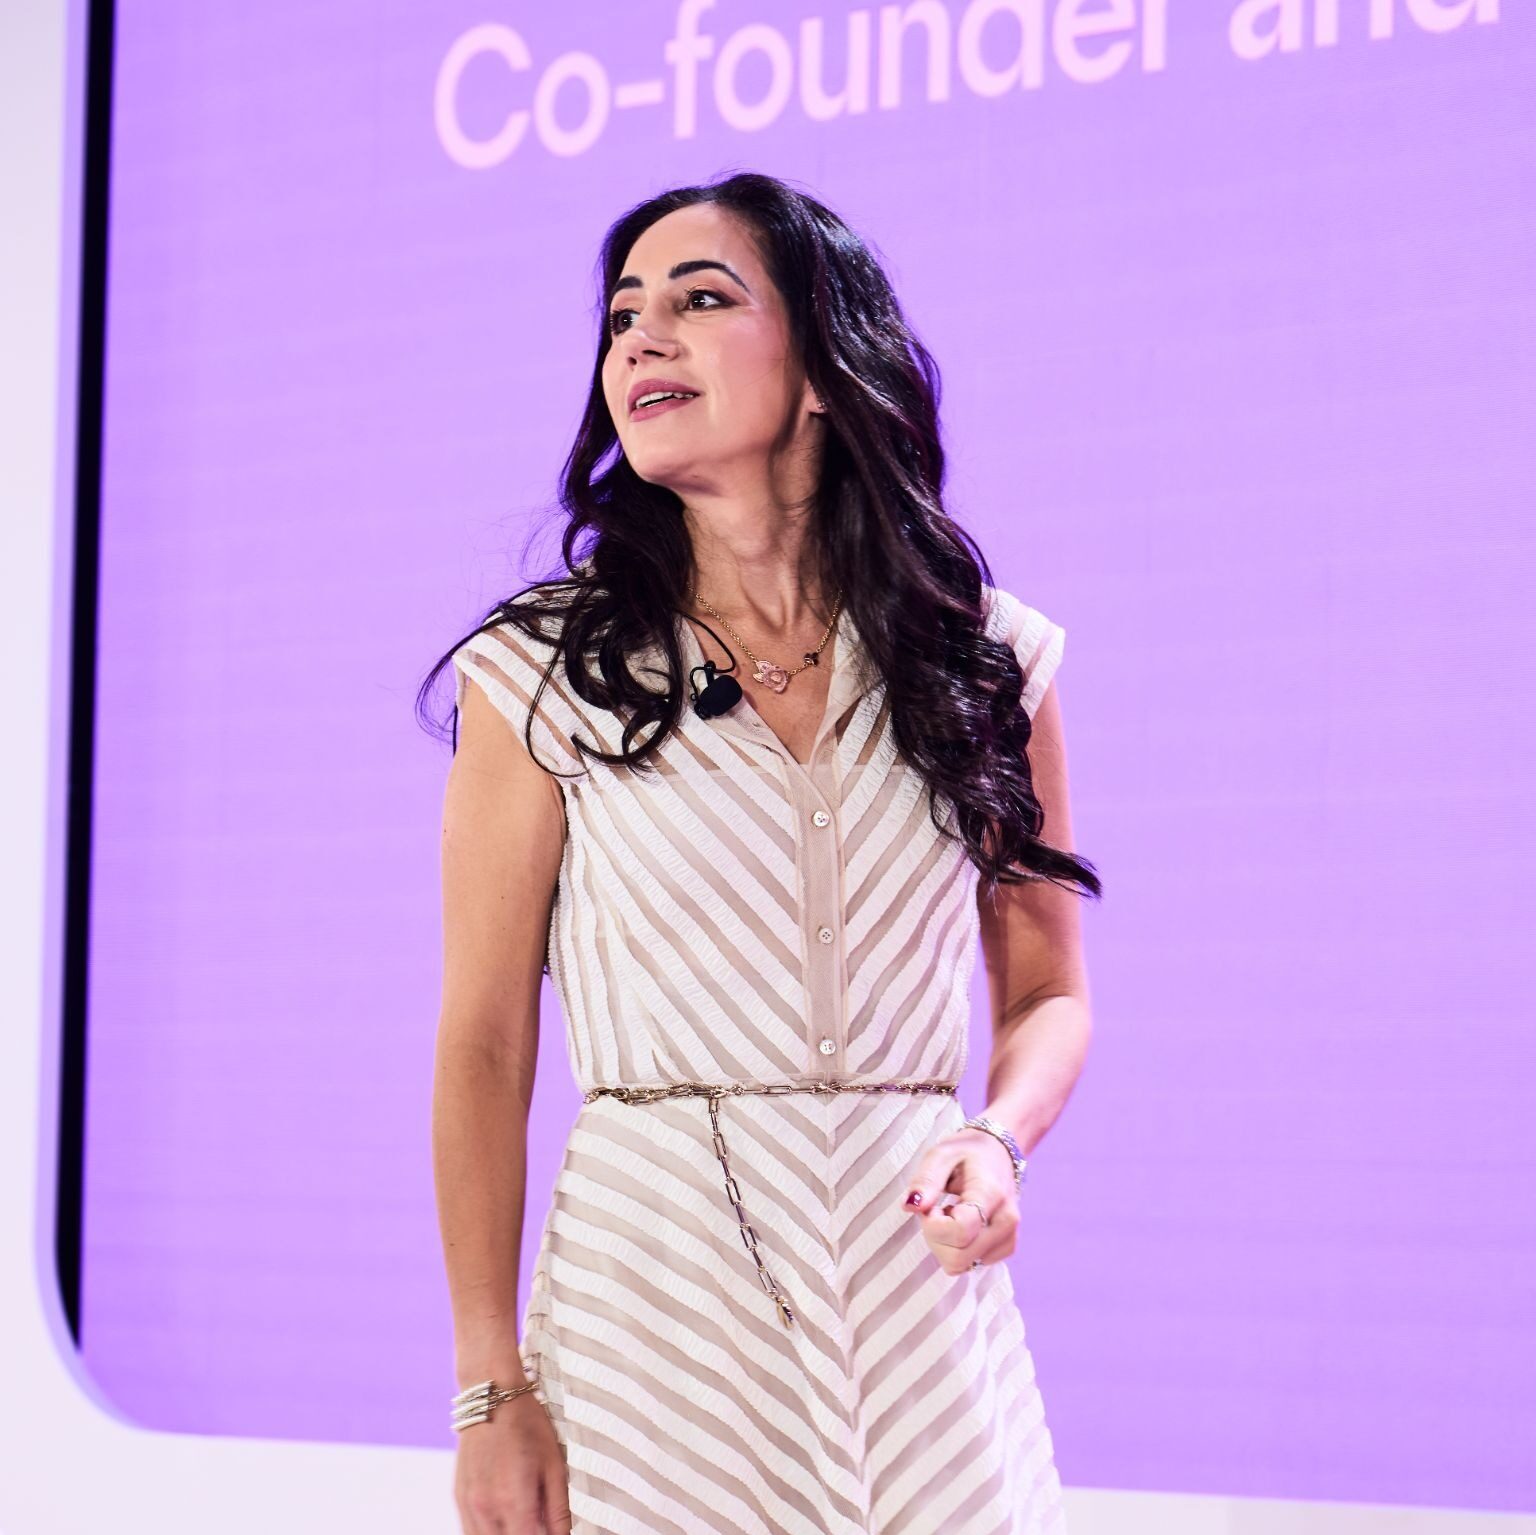
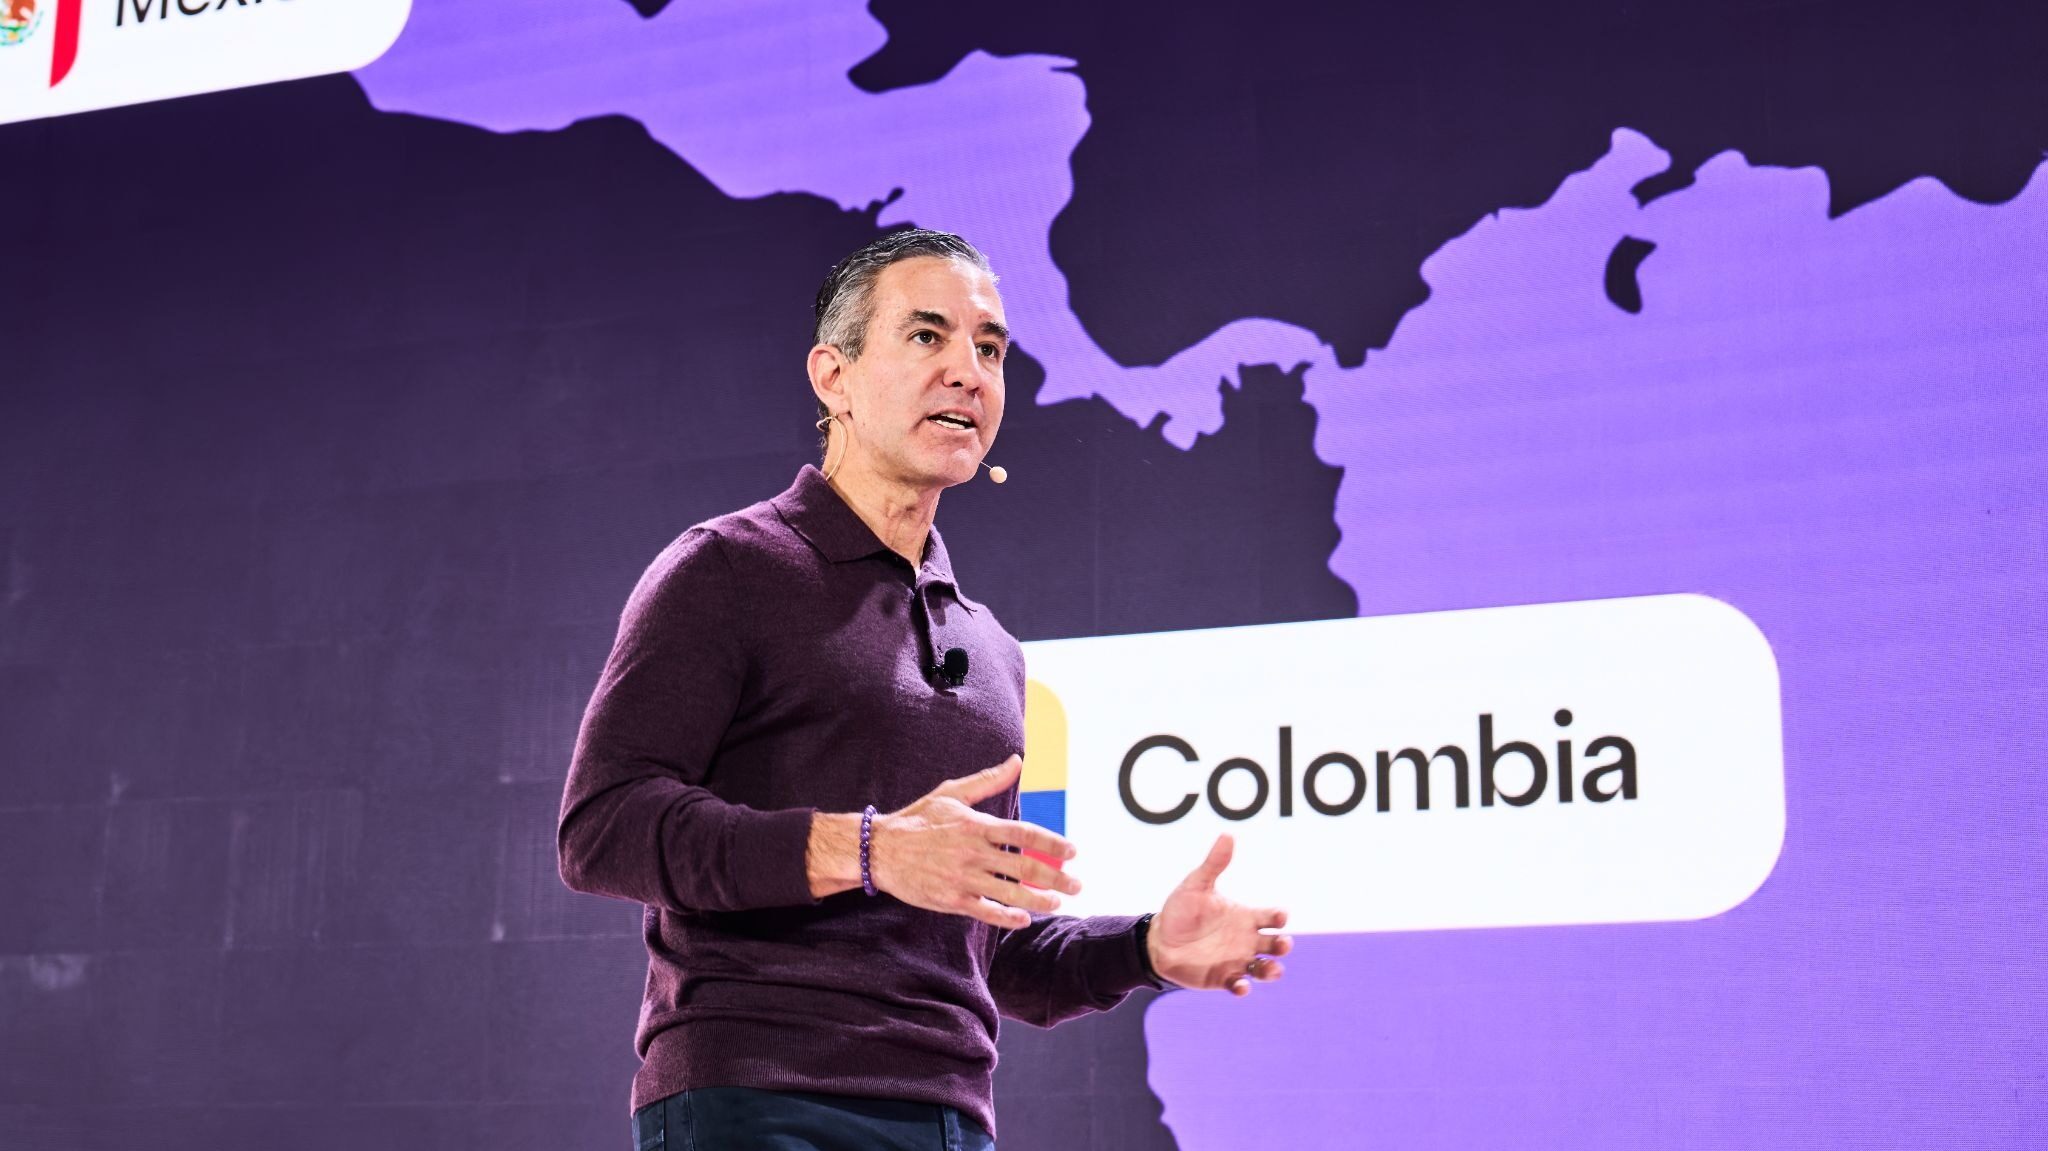
Speaking at a launch event in Miami, founder and CEO David Vélez and co-founder and head of the U.S. business laid out how the company’s entry product lineup consists of deposit accounts paying 3.50% annual yield, fee-free international remittances, and a no-annual-fee credit card that offers 1.5% cash back on purchases. 

In January, Nubank’s application for a national bank charter received a conditional approval from the Office of the Comptroller of the Currency, and the firm is now undergoing review by the Federal Reserve and the FDIC. Junqueira told the Miami audience that she expects Nubank to be fully operational under its own charter sometime next year.  Until then, the company will run its U.S. business through its partner-bank arrangement, which is a common structure among fintechs entering the American market.
What made Nubank work in Brazil

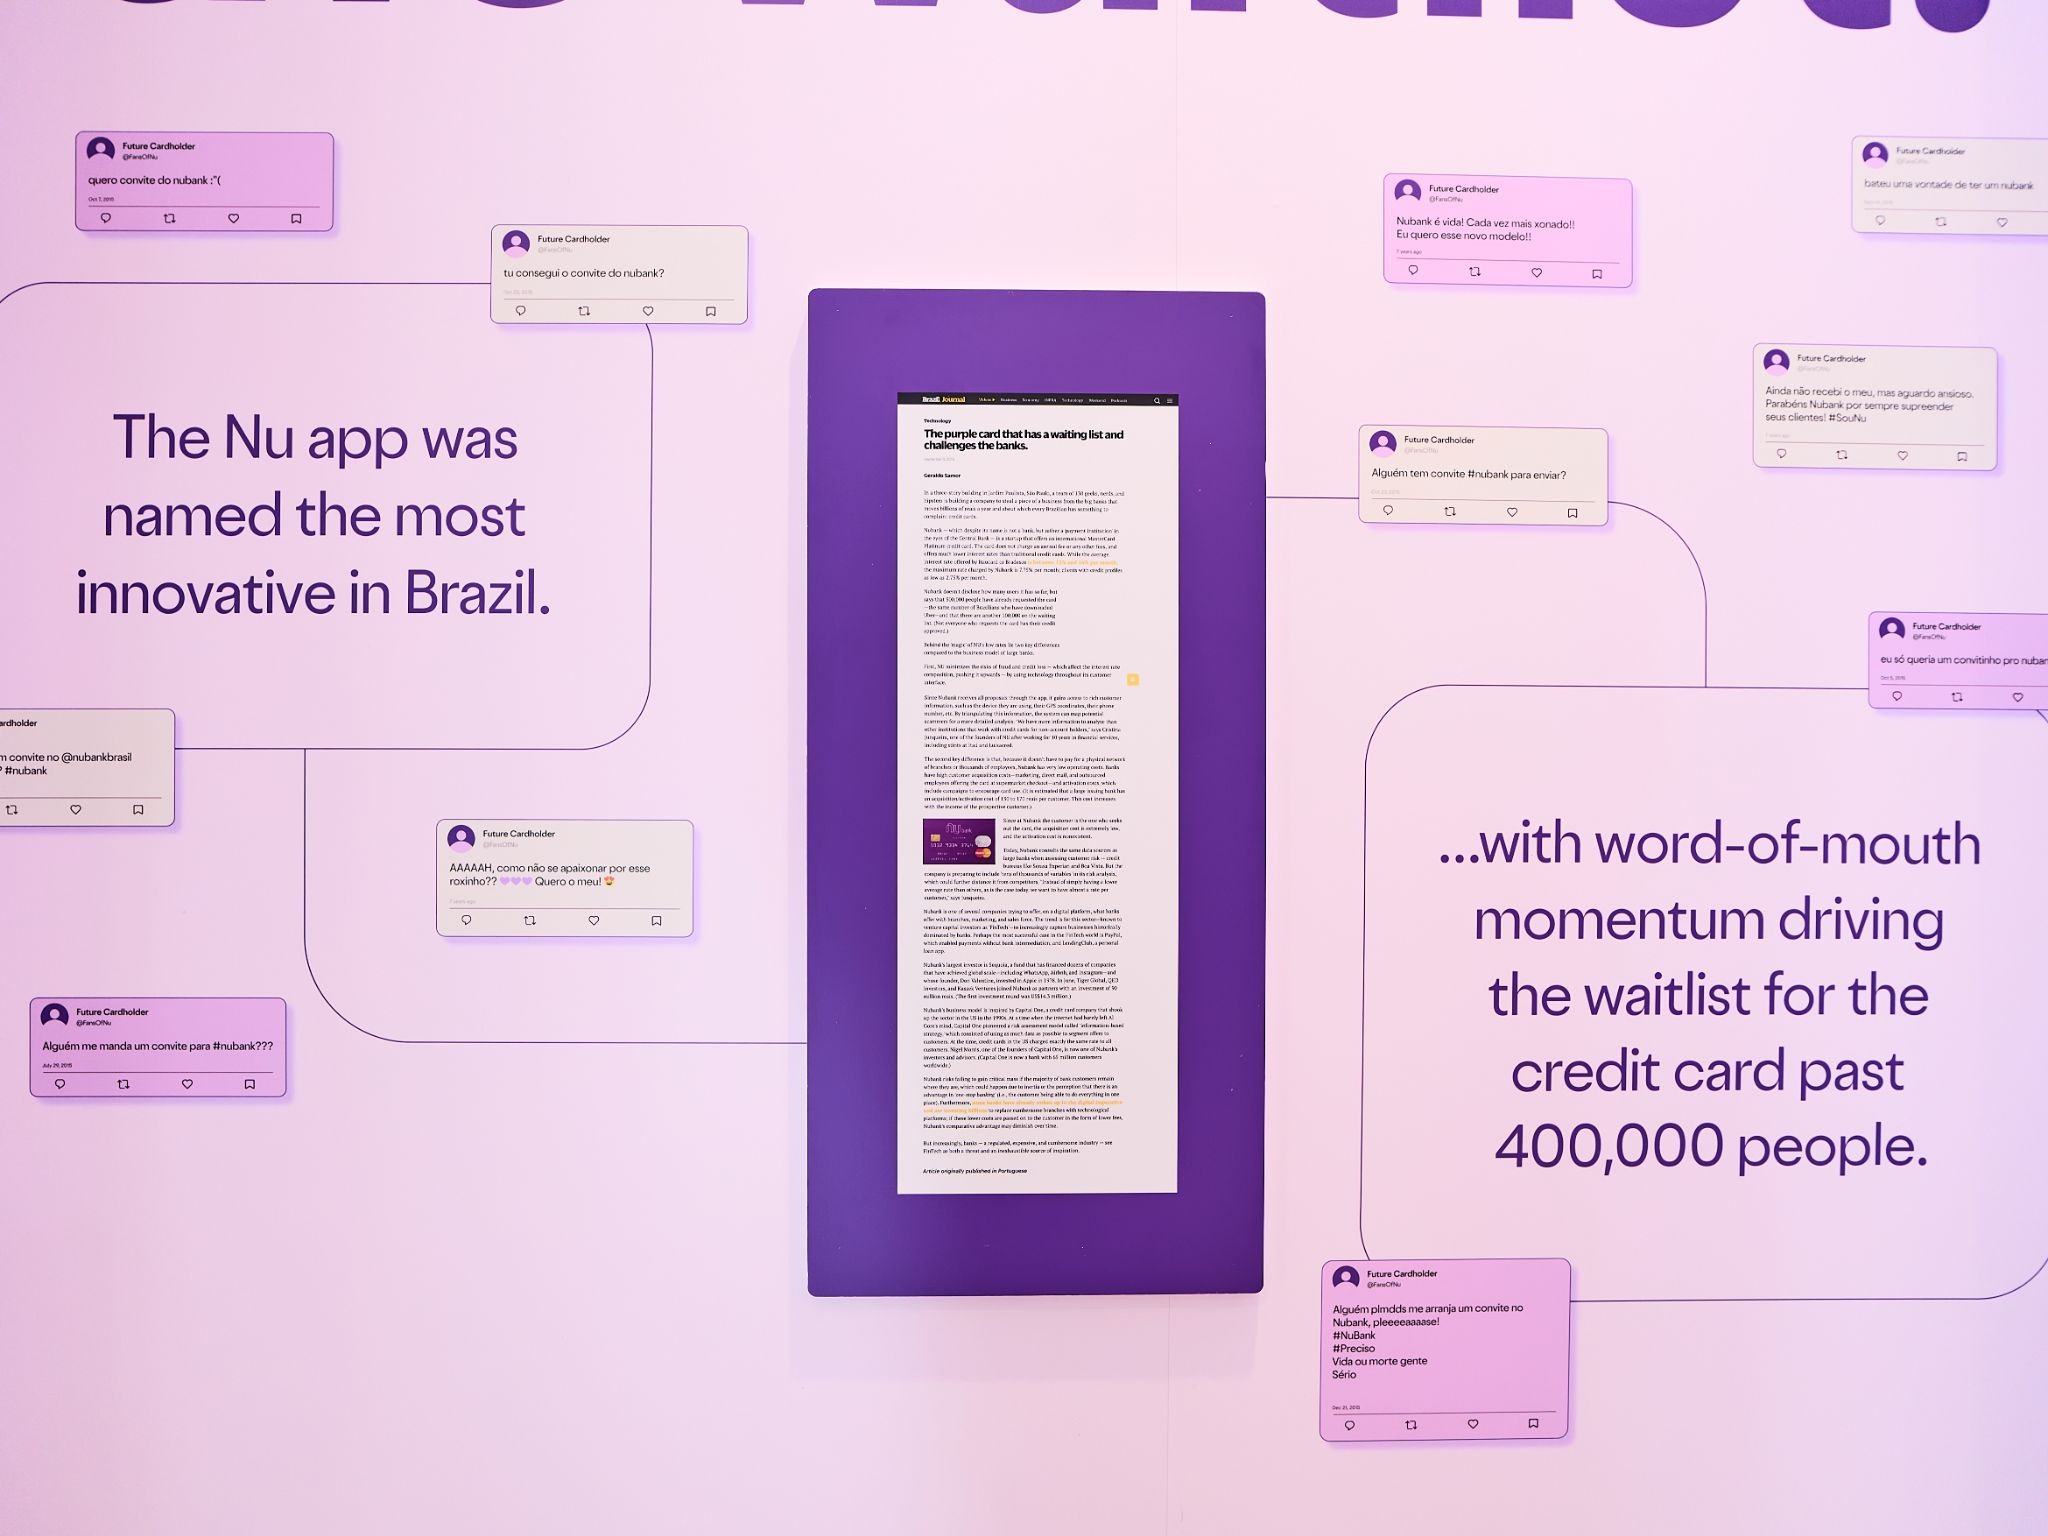
Nubank’s Brazilian rise is usually explained as a story of timing and temperament. When David Vélez, Cristina Junqueira, and Edward Wible founded the company in 2013, a handful of large incumbent banks controlled the vast majority of Brazil’s banking market and were known for high fees, branch-bound bureaucracy, and poor service. 

Sequoia Capital, where Vélez had worked as a partner, describes the setup as a near-monopoly that had gone unchallenged for decades, and frames Nubank’s rise as an underdog campaign against that entrenched oligopoly, one built around a level of consumer experience Brazilian banking customers had never been offered.

The company started small: its first product was a purple credit card, chosen in part because it was one of the few financial products in Brazil that didn’t require Nubank to hold a banking license. From there, the strategy leaned on eliminating the fees Brazilians resented most: Nubank charges no account maintenance or overdraft fees, arguing that customers shouldn’t have to pay to manage their own money. That mattered enormously in a country where large numbers of lower-income Brazilians had effectively opted out of formal banking because fees ate into thin balances. Going fully digital and branch-free allows Nubank to pass those savings back to customers while also reaching people traditional banks had largely written off.

Nubank also rebuilt underwriting from scratch. Rather than relying on the thin credit files that shut many Brazilians out of formal credit, it used alternative data to assess risk. In a single year,  the company brought 5.7 million previously excluded people into the credit-card market. 

The results have compounded over time. Nubank now serves over 60% of Brazil’s adult population and, by some measures, has overtaken Itaú and Caixa to become the country’s most valuable financial brand, all without ever operating a physical branch network.
Why the U.S. bet is interesting

…

Fiserv is reworking the infrastructure behind modern banking


    Weekly 10-Q

    The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

    Message Sara


    Fiserv is reworking the infrastructure behind modern banking

    The bank-tech complexity problem is moving upstream


    Fiserv [FISV] has built its business around helping financial institutions navigate technology change. Now it is confronting a transformation of its own. Its market value is about $26 billion, down from roughly $90 billion at its peak, with the sharpest break coming in October 2025, when the company cut its outlook and shares plunged more than 40%. 

    The business is now trying to simplify a sprawling technology estate, improve service and product delivery, rethink how its products fit together, and scale AI across the organization.

    In June 2026, Fiserv appointed Takis Georgakopoulos CEO, effective immediately, after Mike Lyons left to become CEO of Truist. Georgakopoulos had joined Fiserv in late 2024 after 17 years as Global Head of Payments at J.P. Morgan Chase’s Corporate & Investment Bank, and had already risen from executive vice president to chief operating officer and then co-president at Fiserv.

    Georgakopoulos is not assuming control of a company looking for its next big product idea, but one that has to make a very large, very complicated business work better. And Fiserv is not simply another technology vendor that happens to sell software to banks. It processes payments, runs networks, provides account-processing and digital-banking infrastructure, operates merchant acquiring businesses, and powers commerce through Clover. Its infrastructure sits underneath financial institutions and businesses moving money every day. Fiserv describes itself as a financial infrastructure business spanning payments, account processing, digital banking, merchant acquiring, network services, e-commerce, and commerce technology.

    That makes the current overhaul a little nerve-racking because the company is trying to modernize the machinery that other companies rely on while simultaneously asking those same clients to trust it with more of their future infrastructure.

    Fiserv got bigger; the stack got messier

    Fiserv’s roots of today’s problems go back to a strategy that made sense for a long time, which was to keep adding capabilities.

    …


    subscription wall for TS Pro

    The Week in Market Moves | Sept 10 – 17, 2026


    Company signals and market response

    This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

    It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

    Subscribe to PRO and get the full 10-Q story in your inbox every Friday!


    1. Truist (TFC) – Close: $48.45

    • Truist is selling $5.5 billion of auto loans and exiting near-prime auto lending, covering substantially all of the assets at Regional Acceptance Corporation.
    • The move is part of a broader effort to redirect capital toward more profitable relationships, particularly commercial banking, while reducing credit risk and wholesale funding needs.

    Why it matters: Truist is getting more selective about what it wants its balance sheet to do. Auto lending can generate volume without necessarily creating the broader relationship economics the bank gets from commercial clients across deposits, payments, liquidity and capital markets. With RAC roughly break-even in the first half, the portfolio sale makes the logic of exiting fairly clear: less capital tied up in a business that isn’t pulling its weight, and more room to concentrate on businesses with deeper economics.

    2. Circle (CRCL) – Close: $85.09

    • Circle has launched Arc, a blockchain built around real-time money movement, financial markets, and AI agents acting as economic participants, with more than 100 partners at launch.
    • Arc is tightly connected to Circle’s USDC and Agent Stack, extending the company’s stablecoin infrastructure into the transaction layer for agentic commerce.

    Why it matters: Circle is moving beyond making stablecoins useful and toward building infrastructure around how money moves in an increasingly automated economy. The bet is that AI agents will need their own rails for payments, liquidity, and settlement, rather than simply plugging into today’s consumer payment stack. Arc puts Circle closer to that underlying infrastructure and gives USDC a role in transactions that may happen without a person directly initiating each payment.

    3. J.P. Morgan Chase (JPM) – Close: $349.31

    • Chase is letting eligible cardholders convert Ultimate Rewards points into cash for investment through eligible J.P. Morgan Self-Directed Investing accounts or advisor-managed taxable accounts.
    • The feature turns rewards into another entry point into J.P. Morgan Wealth Management, alongside existing redemption options such as travel, cash back, and statement credits.

    Why it matters: The move stretches the definition of what a credit-card reward is supposed to do. Instead of simply giving customers something to spend, Chase can turn accumulated points into an on-ramp to investing and potentially deepen the relationship beyond the card itself. It also shows how rewards programs are becoming connective tissue between different parts of a financial institution, rather than a standalone card benefit.

    4. Wells Fargo (WFC) – Close: $86.89

    • Wells Fargo has brought ExpressSend Mobile into its banking app, allowing customers to send money from the U.S. to recipients in 12 countries.
    • Customers can send money to bank accounts or cash-pickup locations, track transfers in real time, and manage recipients without leaving the app.

    Why it matters: It’s another example of the banking app becoming the place where more of a customer’s financial life gets handled. Remittances are a recurring, relationship-driven use case that historically pushed customers toward specialist providers; putting the capability inside the primary banking relationship gives Wells Fargo another reason for customers to stay within its ecosystem when money moves across borders.

    5. Affirm (AFRM) – Close: $70.28

    • Affirm has deployed a transformer-based underwriting model at U.S. checkouts that can approve applicants its previous system would have declined, including consumers with thin credit files or no FICO score.
    • Built on 14 years of transaction-level lending data, the model produced 3.4% more completed purchases in its initial deployment while maintaining comparable risk and outperforming a similar expansion using Affirm’s previous models.

    Why it matters: The story is that the model is extracting more signal from data Affirm already had. That matters in lending because expanding approvals without degrading credit performance is the hard part. Affirm is trying to make the boundary between “too little credit history” and “too little information to make a decision” much less rigid, while keeping explainability and real-time decisioning intact.

    NVIDIA bought Hugging Face. What happens to banks when AI models become open?


      Weekly 10-Q

      The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

      Message Sara


      NVIDIA bought Hugging Face. What happens to banks when AI models become open?

      What does this acquisition change for banks?


      A bank deciding which AI model to use is becoming a little like a bank deciding which payment rail to use. The next natural question in line is who controls the infrastructure underneath it. This is what makes NVIDIA’s $12.93 billion acquisition of Hugging Face worth watching from a financial services perspective. What looks like a bet on open-source AI also forces a harder question for banks: does making AI models more open give financial institutions more control, or does it simply move dependence to another layer of the stack?

      There are credible arguments for both scenarios.

      Hugging Face has become a major distribution point for open AI, with more than 18 million developers, 3 million models, 500,000 datasets, and 1 million applications on its platform. More than 200,000 companies use it to discover, evaluate, customize, and deploy AI. NVIDIA says the platform will remain open and that customers will be free to choose their models, frameworks, clouds, inference providers, and computing platforms.

      Financial institutions are already moving in this direction. NVIDIA’s 2026 financial-services survey found that 84% of respondents consider open-source models and software important to their AI strategy, while 42% are using or assessing agentic AI.

      We take a look at two potential scenarios that could unfold for banks following this acquisition.

      Scenario 1: Open models give banks more control

      …


      subscription wall for TS Pro

      Fifth Third is trying to make a bigger bank feel simpler


        Weekly 10-Q

        The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

        Message Sara


        Fifth Third is trying to make a bigger bank feel simpler

        Fifth Third is building more ways to serve customers without adding complexity.


        Fifth Third [FITB] has launched Truly Simple, a new card for easing the cost of carrying revolving debt. The card offers 0% APR on purchases and balance transfers for 18 months, carries no annual fee, and lets customers move balances and manage payments through Fifth Third’s mobile app. 

        “People are looking for practical and reliable ways to manage debt,” Ben Hoffman, Chief Strategy Officer and Head of Consumer Products, said during the announcement of the card launch.

        With its recent moves across AI, small-business banking, embedded finance, and acquiring Comerica, the new card points to a larger ambition for Fifth Third, expanding its reach while making the banking experience feel simpler. 

        The Ohio-based bank is simplifying its consumer card lineup around two primary needs: its 1.67% Cash/Back card for everyday rewards and Truly Simple for customers who want to finance purchases or consolidate debt. The firm is simplifying its product portfolio so customers have a clearer reason to choose one product over another.

        We look at how the new card launch is a part of Fifth Third’s broader product strategy.

        A bigger bank, with more ways into the relationship

        …


        subscription wall for TS Pro

        The Quarterly Review: BNY’s Carl Slabicki is pushing toward practical innovation


        In this edition, we spotlight Carl Slabicki, Head of Commercial for Global Payments & Trade at BNY. 

        At BNY, Carl Slabicki oversees the firm’s work connecting payments, liquidity, and trade for clients navigating an increasingly always-on financial landscape. BNY has long been a central player in global custody and treasury services, and under Slabicki’s tutelage over these past few months, its footprint has been expanding into more integrated, cross-capability solutions spanning digital assets, data, and AI. 

        In this edition, Slabicki dives into how BNY is moving clients from broad modernization conversations toward practical and measurable execution, and how this shift is shaping the firm’s approach to client relationships, market education, and commercial strategy.

        …

        The Week in Market Moves | Sept 03 – 10, 2026


        Company signals and market response

        This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

        It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

        Subscribe to PRO and get the full 10-Q story in your inbox every Friday!


        1. Chime (CHYM) – Close: $32.67

        • Chime is paying $590 million in cash to acquire Stride Bank, its bank partner of more than seven years, with the deal expected to close in the first half of 2027, subject to regulatory approval.
        • Stride’s national bank charter will become Chime’s own banking infrastructure, with the bank expected to operate as Chime Bank, N.A., a wholly owned subsidiary.

        Why it matters: Chime is bringing a critical piece of its banking stack in-house. The move reduces its dependence on a partner bank, eliminates partner-bank fees, and gives it more control over how quickly it develops and launches products. More importantly, it changes the economics and structure of the fintech-bank model: Chime is no longer just building on top of a bank; it is buying the bank underneath it.

        2. U.S. Bank (USB) – Close: $62.41

        • U.S. Bank launched USBDC, its own dollar-backed stablecoin, and used it in a live cross-border payment between its North American and European entities.
        • The pilot ran on the Stellar blockchain and tested the full stablecoin lifecycle, including minting, payments, redemption, freezing, and clawback, while connecting back into the bank’s existing risk, compliance, and operating infrastructure.

        Why it matters: The interesting part is that U.S. Bank is testing whether tokenized money can actually run inside a regulated bank’s existing machinery. That makes the experiment less about crypto and more about modernizing cross-border money movement. As more banks issue their own digital dollars, the harder problem may become making those different forms of money interoperable.

        3. Visa (V) – Close: $367.21, Mastercard (MA) – Close: $565.37

        • Visa, Mastercard, and Ant International are working toward a common Know Your Agent framework to help identify and onboard AI agents across payment networks, wallets, marketplaces, and agent platforms.
        • The three companies already have separate agent protocols – Visa’s Trusted Agent Protocol, Mastercard’s Verifiable Intent, and Ant International’s Agentic Mobile Protocol – and are now exploring common principles and trust signals.

        Why it matters: Agentic commerce creates a new identity problem: the party initiating a transaction may no longer be the human customer. If every network builds its own way to verify an agent, merchants and platforms could end up repeating the same checks across ecosystems. A common KYA layer could become the plumbing that lets an AI agent carry trusted identity and risk signals from one payment environment to another.

        4. Coinbase (COIN) – Close: $172.28

        • Coinbase is partnering with Moov to bring stablecoin payments, settlement, and real-time funding to community banks and credit unions.
        • Moov will embed Coinbase’s regulated digital-asset infrastructure into its existing payments platform, allowing institutions to offer stablecoin services without building a separate crypto stack.

        Why it matters: Coinbase is attacking one of the biggest barriers to stablecoin adoption among smaller financial institutions: the technology burden. Instead of asking a community bank to become a crypto infrastructure company, the partnership puts those capabilities behind the payments systems it already uses. That could make stablecoins less of a specialized digital-asset product and more of an infrastructure feature that banks can switch on.

        4. Nu (NU) – Close: $15.02

        • Nu has entered the U.S. with a full consumer banking suite through partner bank Lead Bank, including a 3.5% APY account, credit card, debit card, savings tools, and cross-border transfers.
        • The launch gives Nu a way to enter the market while it works toward its own U.S. national bank charter, for which it received conditional OCC approval in January 2026.

        Why it matters: Nu is taking a different route into the U.S., rather than waiting for its own charter before launching. Lead Bank gives it the regulatory and banking infrastructure to start learning from U.S. customers now, while Nu builds toward owning more of that stack itself. Nu Global, a multicurrency account that uses USDC and EURC to move money across 35+ countries, also gives the U.S. launch a distinctly cross-border angle, extending Nu’s Latin American cross-border DNA into its U.S. strategy.

        The Week in Market Moves | Aug 27- Sep 03, 2026


        Company signals and market response

        This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

        It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

        Subscribe to PRO and get the full 10-Q story in your inbox every Friday!


        1. Affirm (AFRM) – Close: $74.30

        • Affirm and Shopify are bringing Shop Pay Installments to Australia, giving eligible shoppers the option to split purchases into fortnightly or monthly payments.
        • The launch expands Affirm’s Shopify footprint beyond the U.S., Canada, and the U.K. and marks Affirm’s return to Australia, with the service powered exclusively by Affirm.

        Why it matters: Affirm is extending a distribution model that puts its credit product directly inside Shopify’s checkout. That’s a step forward as BNPL moves toward more frequent, everyday transactions rather than being reserved for large-ticket purchases. Affirm’s latest quarter supports that shift, with GMV up 36% to $14.1 billion and transactions growing by 41% to 53 million. The Australia launch gives that broader usage strategy another market to test.

        2. NVIDIA (NVDA) – Close: $228.45

        • NVIDIA has paused some revenue-sharing deals under its AI Compute Partnership Program, less than two months after launching the financing initiative for smaller AI cloud providers.
        • The retreat comes amid concerns that NVIDIA’s role as chip supplier, financier, and potential revenue participant could attract greater antitrust scrutiny.

        Why it matters: NVIDIA’s ambition has been expanding beyond selling chips into helping finance the infrastructure needed to deploy them. That can accelerate the AI buildout, but it also puts the firm in an increasingly unusual position: supplier, capital provider, and economic participant in the businesses using its hardware. The pause suggests there are limits to how far NVIDIA can extend that influence without raising questions about competition and the financing structures supporting AI demand.

        3. Intuit (INTU) – Close: $344.30

        • Intuit is bringing QuickBooks and Mailchimp into Perplexity Computer through MCP connectors, allowing businesses to access Intuit’s data and capabilities from an AI interface.
        • The integration moves beyond retrieving information, with users able to manage cash flow, chase overdue invoices, access payroll information, and analyze marketing performance.

        Why it matters: If businesses increasingly ask AI agents to do the work, Intuit’s value has to travel with the customer rather than remain inside QuickBooks or Mailchimp. The partnership with Perplexity lets Intuit put its financial data and domain expertise into an agentic workflow while keeping its systems underneath the actions being taken. That could make Intuit’s financial intelligence more valuable even when the customer is no longer starting with an Intuit product.

        4. Fifth Third Bank (FITB) – Close: $54.97

        • Fifth Third launched the Truly Simple Credit Card with 0% APR on purchases and balance transfers for 18 months and no annual fee.
        • The bank is simplifying its card lineup around two primary jobs: its 1.67% Cash/Back card for rewards and Truly Simple for financing purchases and consolidating higher-rate debt.

        Why it matters: Fifth Third is assigning each card a clear customer job instead of competing with a crowded rewards-card market on features. That fits the bank’s broader push to make its products feel simpler even as the institution itself becomes more complex through digital expansion and the Comerica integration. The card is a relatively straightforward product move, but the sharper strategy is deciding what each product is actually for.

        Goldman Sachs built its talent pipeline around apprenticeship. AI is now testing what that means


          Weekly 10-Q

          The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

          Message Sara


          Goldman Sachs built its talent pipeline around apprenticeship. AI is now testing what that means

          How do you develop talent when AI does the work they once learned from?

          Goldman Sachs approaches the first months of a young employee’s career as a formative period. The company puts new hires close enough to experienced bankers and traders to learn what no classroom could teach: how a client conversation actually works, why a senior colleague makes a particular call, and what to notice before anyone explains it.

          AI is changing the economics of that first pass and potentially the learning that came with it. The pressure is now showing up in a new place. Goldman’s internal research says entry-level workers are already facing stronger AI-related hiring headwinds than more senior employees. Entry-level work has traditionally served two purposes: getting the work done and training the person doing it. If AI eliminates enough of the former, companies have to deliberately recreate the latter.

          At the same time, Chris Churchman, who heads Marquee, Goldman’s digital platform for institutional clients, warns that the bank could automate away some of the very experiences through which junior employees learn to become senior ones. 

          So, what happens to the apprenticeship model when AI starts doing the work apprentices used to learn from?

          Goldman’s early-career programs were always deliberately hands-on

          When I spoke with Omer Tanvir, Goldman Sachs’ former global head of campus and diversity recruiting, for Tearsheet’s coverage of the bank’s 2024 summer internship program, the word “apprenticeship” described how the firm expected young people to learn.

          …


          subscription wall for TS Pro

          The Week in Market Moves | Aug 20-27, 2026


          Company signals and market response

          This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

          It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

          Subscribe to PRO and get the full 10-Q story in your inbox every Friday!


          1. Wells Fargo (WFC) – Close: $84.97

          • Wells Fargo is stepping up its recruitment of independent advisers, who can use the bank’s infrastructure without becoming full-time employees; those advisers have already brought in $17 billion this year.
          • The strategy is also helping offset adviser departures across the industry, with Wells Fargo attracting teams such as James Taylor’s from Morgan Stanley, along with nearly $6 billion in client assets.

          Why it matters: The wealth-management model is changing as technology makes it easier for advisers to operate independently. Rather than fight that shift, Wells Fargo is trying to become the infrastructure layer that independent advisers can build on. That gives the bank a way to keep the economics and relationships of wealth management without insisting every adviser fit the traditional employee model. The bigger bet is that flexibility, rather than employment status, becomes the new battleground for adviser talent.

          2. Visa (V) – Close: $379.66

          • Visa has expanded its Visa Vulnerability Agentic Harness (VVAH) from finding and assessing vulnerabilities to actually remediating and validating them.
          • It is pairing the technology with an expanded cybersecurity advisory practice, helping clients assess risk, prioritize vulnerabilities, and build remediation roadmaps.

          Why it matters: The interesting shift here is that AI is moving further down the operational chain. Finding a vulnerability is useful, but the real value comes from shortening the distance between discovery and fixing it. That’s becoming more important as attackers can exploit newly discovered weaknesses in hours rather than weeks. Visa is treating cybersecurity as an ongoing response loop, not a periodic assessment exercise.

          3. TD Bank (TD) – Close: $121.09

          • TD generated C$195 million ($141 million) in AI value during the first three quarters of fiscal 2026, putting it within distance of its full-year C$200 million target months early.
          • The bank is deploying AI across credit, software development, and contact centers, while expanding into areas such as insurance claims, employee knowledge management, and income verification.

          Why it matters: TD’s significance is that AI is being measured as a business outcome rather than an innovation program. The bank is pushing AI into processes where the payoff can show up in lower unit costs, faster decisions, and less manual work. It also gives TD a concrete baseline against which future AI spending can be judged. The next question is whether these early gains can compound to achieve the bank’s C$1 billion medium-term AI value ambition.

          4. Affirm (AFRM) – Close: $77.49

          • Affirm’s transactions grew 41%, faster than its 36% GMV growth, while average order value fell 4% – a sign that consumers are using BNPL for more frequent, smaller purchases.
          • Affirm Card is accelerating that shift: active cardholders more than doubled to 5.2 million, while card GMV jumped 124% to $2.8 billion.

          Why it matters: Smaller baskets and higher transaction frequency suggest Affirm is expanding from a financing product into a broader payment habit. That creates more opportunities for usage, but also puts more pressure on underwriting discipline as frequency rises. The usual test is whether Affirm can increase everyday engagement without turning that broader reach into a credit-quality problem.

          5. NVIDIA (NVDA) – Close: $227.98

          • Nvidia is reportedly nearing a roughly $13 billion acquisition of Hugging Face, the platform where developers share, discover, and build AI models.
          • The deal would give Nvidia a much deeper position in open-source AI at a time when developers are looking for alternatives to models controlled by OpenAI, Anthropic, and other closed-model providers.

          Why it matters: This is a strategic move beyond chips. Nvidia’s hardware dominance ultimately depends on there being a large and growing ecosystem of models that need to run on that hardware, and open-source models can help expand that market. Bringing Hugging Face closer could give Nvidia influence over both the developer and compute layers. It also highlights how the AI infrastructure battle is broadening: firms are now eyeing controlling the ecosystem around how models are built, deployed, and run.