

How banks can stay relevant, not relics: Lessons from BNY & Citi
- BNY takes the AI route to improve its operations, and Citi continues to use workplace flexibility to navigate talent challenges.
- Banks willing to embrace change — whether through AI, flexible work environments, or other innovations — can use it to their advantage and stay relevant.

Old Guard, New Rules: Who’s keeping up?
Big banks are playing offense. Fintech competition, tech leaps, and workforce expectations are evolving — so should banks.
Traditional banks are already trying on a modern fit — experimenting with tech, balancing brick-and-click, rethinking talent, and making new power couple moves in partnerships.
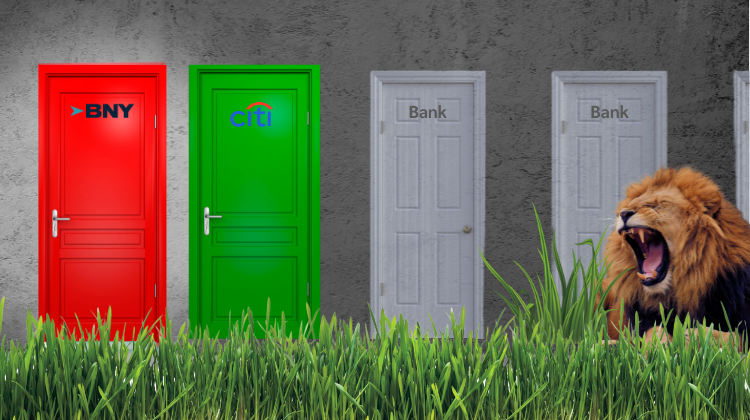
Two prime examples stood out last week: BNY takes the artificial intelligence route to improve its operations, and Citi continues to use workplace flexibility to navigate talent challenges. While these paths differ, they reflect a shared realization — adapt or risk becoming a museum exhibit.
BNY: Merging centuries of banking with AI innovation
Established in 1784, BNY is America’s oldest bank, which has thrived for over two centuries. Yet, instead of clinging to its storied past, the institution is looking forward, betting big on AI as the key to its future.
In a landmark deal, BNY has entered into a multiyear relationship with OpenAI, a decision that signals more than just technological adoption — it’s an illustration that even the most traditional players should innovate or risk being upstaged by a 25-year-old coder in a hoodie.
The cornerstone of this AI-driven transformation is Eliza, BNY’s proprietary AI platform, launched in 2024. Initially conceived as an internal chatbot trained on the bank’s vast institutional knowledge, Eliza has evolved into a multifaceted AI tool that empowers employees to build AI-powered applications. More than 50% of the bank’s 52,000 employees actively engage with Eliza, using it for tasks ranging from lead generation to workflow optimization. By integrating OpenAI’s most advanced models launched this year, BNY is supercharging Eliza with next-gen capabilities. These include Deep Research, which can analyze vast amounts of online information to complete multistep research tasks, and Operator, an AI agent capable of browsing the web like a human.
But why is BNY Mellon making this move now? Necessity. Competition. Strategic vision.
- Necessity: AI adoption in banking is no longer optional. From compliance to risk management, the financial sector deals with high complexity. AI offers solutions to streamline operations, reduce inefficiencies, and facilitate decision-making.
- Competition: Fintech startups and tech giants like Google and Apple are poised to take over market share if they fall too far behind. To hold its ground, BNY likely needs a tech upgrade to offer more AI-driven services.
- Strategic positioning: With banks emerging as some of the most active adopters of AI, BNY doesn’t want to be a bystander. Partnering with OpenAI gives it access to the latest underlying tech, positioning it as a strong player in the industry.
However, this transformation is not without its challenges. Integrating advanced AI framework into a 240-year-old institution is like teaching your grandparents to use TikTok. Ensuring compliance with strict regulatory standards, managing the ethical implications of AI-driven decision-making, and upskilling employees to work effectively alongside AI are all significant hurdles. Moreover, cybersecurity remains a major concern — handling sensitive financial data requires strong protective measures to prevent breaches.
Despite these challenges, BNY is forging ahead, not just out of necessity but out of the foresightedness that AI may likely be a big part of the future of banking. This puts other well-equipped banks on the spot — if the oldest bank in America can adapt, what excuse do the rest have?
Citigroup’s Hybrid Bet: Why sticking to flexibility might just be its smartest move yet
…