At Meridian, tokenized assets on Stellar go to work

Day three of Stellar’s Meridian in Lisbon centered on getting tokenized assets to do work. Denelle Dixon, CEO of the Stellar Development Foundation (SDF), said about $5 billion of real-world assets sit on Stellar today and most already earn yield. She wants them to become usable as collateral and in repo and lending, and then to be used at scale. Executives from Figure and M1X Global, which works with the Republic of the Marshall Islands, described products built for this next step.

Yield-bearing assets are the base

Dixon sorts the assets on Stellar into three groups. Useful assets already generate yield. Usable assets can serve as collateral or in repo, lending, and borrowing, which takes infrastructure and, in some cases, new permissions. Used assets do that work every day. “If we can’t do everything that you can do in traditional finance and then some, there’s not a lot of point to it,” she said. The approach reflects how SDF has worked since Dixon joined in 2019: the foundation stayed focused on payments and asset issuance while much of the industry chased meme coins, and Dixon told her team to keep their focus on the field and ignore the stands.

Figure’s YLDS is one example. Karl Samsen, who leads the YLDS business at Figure, said the product is a face amount certificate, a type of debt security registered with the SEC. It moves like a stablecoin, with no broker-dealer approving a transfer between holders on Figure’s allow list, and it pays yield that is credited daily and paid monthly. YLDS has been live on Stellar since May. A fintech or neobank can onboard in about 90 seconds and swap USDC for YLDS at no fee, and Samsen said Figure expects to add a permissionless version, wYLDS, on Stellar later.

Etherfuse applies the same idea to local currencies. CEO Dave Taylor said the company issues yield-bearing tokens it calls stablebonds, backed by local government debt held with a regulated custodian in each country. In Mexico, that means Cetes, the government’s short-term treasury bills, held at BBVA. About $50 million a month moves through the platform, he said.

Collateral and repo make assets usable

The Marshall Islands spreads across an ocean area the size of Mexico and relies on a few correspondent banks abroad. Its dollar-denominated sovereign bond, USDM1, is issued directly on Stellar and backed one-to-one by a U.S. Treasury held by a trustee under New York law, said Jordan Goldman, president of M1X Global, which partners with the government on the bond. Ambassador Charles Paul said the government used to fly cash to islands with 20 residents and send it by boat. Now it distributes aid in USDM1, and residents use it to buy groceries and power.

For institutions, Goldman compared USDM1 to a Brady bond and said it works under standard repurchase agreements. In a repo funded by a credit facility from Ascend Markets, USDM1 rolled 72 times at hourly intervals from October 16 to 19, including overnight and over a weekend, with a 2% haircut and pricing at SOFR plus 10 basis points. A traditional repo takes 24 to 48 hours to settle, Goldman said. Traditional firms have little appetite for trading around the clock, he said, but they want the option to move collateral on a weekend or when it is stuck in a 48-hour cycle. He said STS Digital accepts USDM1 as collateral for derivatives. Institutions want legal certainty, enforceability, and eligible collateral, he said, and a sovereign bond secured by a Treasury offers all three.

Banks move from pilots to production

Kurt Fields, an EY partner who focuses on blockchain and digital assets, said bank clients have shifted over the past few months from experimentation to scale. The work now is bringing risk, compliance, legal, and product teams along so projects stop feeling like sandbox pilots, and deciding how much legacy infrastructure to replace as banks move into a hybrid world. “The technology works,” he said.

Banks often arrive asking to tokenize without knowing what matters, Dixon said, so she points them to compliance, uptime, and how easy the integration is. She described Stellar as another rail for banks, with clawback and freeze controls and 99.99% uptime over the last 10 years.

Asked what a bank product leader should do in the next 90 days, Dixon and Samsen started with the bank’s own problems. Dixon said blockchain can speed treasury movement and earn yield on weekends, but “you need to identify the problems first.” Samsen said the conversation usually involves the CFO, the COO or CEO, and the chief product officer. Licensing depends on how a bank holds YLDS: a bank that executes transactions for clients and charges for it needs a broker-dealer, he said, while a bank that lets clients hold YLDS directly does not.

What 2027 holds

Several guests looked ahead to 2027. Taylor wants Etherfuse in the top 20 to 40 countries, up from nine, ranked by whether a country has investable debt, remittance volume, a high cost of credit, and low financial access, so that payments can move from the peso to the lira without passing through the dollar. Ed Nwokedi of RedSwan, which tokenizes commercial real estate, named work with the Nairobi Securities Exchange on tokenization and a profit-sharing structure for its general partner continuation funds, which large property owners want as a route to liquidity.

Dixon expects the DTC tokenization service, run by DTCC, to be connected to Stellar in the first half of 2027, and said SDF has spent months on the integration.
At Meridian, Stellar makes the case that utility should drive the network

Stellar’s Meridian 2026 opened in Lisbon on Wednesday, the first of two days of sessions on how banks, asset managers, and payments companies use Stellar, a public blockchain built for financial services. Stellar Development Foundation (SDF), the nonprofit that supports the network, used the opening day to argue that its next phase should be measured by use: more payments volume, and tokenized assets put to work as collateral and in lending, not only held in wallets. 

Executives had a consistent message for banks and asset managers weighing a public network: know who will buy the product before building it, and choose a network that works with regulators. 

Day two brings U.S. Bank and Centrifuge onto the stage.

SDF argues utility should drive Stellar’s next phase

SDF calls the network’s next phase a utility era. An SDF post featuring Tomer Weller, the foundation’s Chief Product Officer, calls for reconsidering Stellar’s tokenomics and asks whether a rewards mechanism funded from the network’s existing fee pool could improve the network’s utility. 

SDF’s yardstick is use. José Fernández da Ponte, SDF’s president and chief growth officer, says this year’s priorities are more payments and stablecoin volume, and more tokenized assets put to work as collateral for lending, margin, and repos. A tokenized money market fund that sits in a wallet is “good but it’s not great,” he added.

SDF’s testing a faster way to run Stellar in Project Thruput. Which allows many transactions to be processed at the same time, so the network can handle more payments by adding computers. There is no per-transaction fee. When the network is busy, accounts that hold more XLM get more of the capacity. The preview is running on FutureNet, Stellar’s testing network, and SDF says one validator reached 7.02 million payments per second on eight machines. This number covers one part of the system, and no one outside SDF has replicated it.

Institutions are building on the network

Today’s announcements that accompanied the event lend institutional examples to SDF’s argument. Securitize added Stellar to its supported chains, joining Ethereum, Solana, and Avalanche. CEO Carlos Domingo said Stellar has the fourth-largest tokenized real-world asset ecosystem. Securitize has not named a first asset or launch partner. Janus Henderson and Centrifuge announced JQQQ on Oct 27, a Nasdaq-100 tracking fund licensed by Nasdaq for non-U.S. professional investors, with a minimum of about $100,000 and Stellar as its only chain at launch. Subscriptions are not yet open.

Archax announced €GOVY, a euro version of its perpetual tokenized T-bill product, and joined Pontoro on a pool that pairs money market assets with private-fund interests. An SEC Form D filed Oct 13 lists a $200,000 minimum. SDF has invested in both Archax and Pontoro.

Spiko, a French fintech that runs tokenized cash funds on Stellar, says it manages $3 billion, mostly in overnight money market funds, and has grown more than 15 percent a month since launch two years ago. CEO Paul-Adrien Hyppolite says about 90 percent of the assets belong to companies, nonprofits, VC funds, and public institutions, and the funds’ holder counts show up in public on-chain data. “Many treasurers, CFOs we speak with really like the fact that our funds are not black boxes,” he said. 

U.S. Bank issued a dollar-backed token, USBDC, on Stellar and used it in September to move value between its North American and European entities.

What institutions weigh before they build

Fear of missing out is pushing some incumbents to launch tokenized money market funds because another institution did, Hyppolite says. “I would not do that,” he said. “Distribution first.”

Institutions weigh three things when they pick a network, according to Fernández da Ponte: the chain’s design for financial services, the depth of its developer and customer ecosystem, and its stance toward regulators. “If you work in financial services, you need to love your regulator,” he said.

Anthony Scaramucci of SkyBridge Capital frames the choice as one of foresight and will. His image is “shooting the iPod”: at the iPod’s peak, Steve Jobs could see the future the iPhone presaged. Scaramucci says banks need that foresight when it comes to tokenizing real-world assets, along with the institutional will to make the hard decisions that lead to a better future. He says he made that decision himself at SkyBridge. He expects the tipping point to come when the top 10 stocks are tokenized.

What to watch on day two

Thursday’s schedule has three sessions that answer open questions from today.

  • 10:05 AM: Jamie Walker of U.S. Bank on the bank’s stablecoin pilot.
  • 11:15 AM: Centrifuge and Janus Henderson on when JQQQ subscriptions open and when U.S. investors get access.
  • 5:10 PM: The closing session, which the schedule says will include a special announcement.

Banks have moved past whether to modernize. Now they want outcomes.

The debate over whether banks should modernize their core technology is largely settled. The question now is how to do it without putting the systems customers depend on at risk.

This evolution has shaped Temenos Regional Forum Americas in Orlando, where more than 350 customers, partners, prospects, and industry leaders gathered.


“Institutions are no longer debating whether to modernize,” said Brian DuVal, President of Temenos. “They’re focused on how to do it in a way that accelerates growth, improves customer experiences, and preserves trust.”

Temenos’ recent deals show how quickly the firm’s gaining momentum. A leading US regional bank chose Temenos SaaS to modernize its corporate banking, and Questrade, a top-rated Canadian online broker, launched its banking business on Temenos.

A path that fits the institution

Banks now want a modernization plan built around their own priorities, customers, and business model. They want speed and innovation, with less risk and disruption along the way. The systems behind payments, accounts, and access to funds can’t go down while the bank evolves.

Research Celent conducted for Temenos, released at the forum, shows 75% of US consumers said they are only moderately satisfied or less with their primary financial institution. Celent calls this group the “switchable middle.” Banks feel it too: 62% of US banks say winning and keeping customers has become harder over the past 12 months.

The gap goes beyond digital features. “It is about whether banks can keep pace with how customers want to manage their financial lives,” DuVal said.

AI moves into daily work

A year or two ago, bank conversations about AI centered on possibilities. Today they focus on specific applications: raising productivity, speeding up decisions, preventing fraud, and personalizing customer experiences. “The technology is moving from experimentation into everyday workflows,” DuVal said.

Customers increasingly expect banking to feel proactive and personalized, but bank budgets haven’t caught up. In the global edition of Celent’s research, just 4% of banks named personalization of the customer experience as their top investment priority. AI can’t fix this by itself, only capital and resources can. But AI can help accelerate deployment of modern personalization tools, closing the gap between customer expectations and banks’ ability to fulfil them.  

Through a sharper spotlight on the broader technology ecosystem, Gen AI has moved up the agenda. Cloud, data, and AI now come up in board-level modernization discussions, which brings partners like AWS and Microsoft into the room. Banks want to know how the full environment helps them move faster, scale securely, and strengthen resilience.

Trust takes on a wider meaning

Trust in banking starts with the basics. “Payment transactions go through. Accounts are secure. Customers can access their money whenever they need it. The institution performs exactly as expected,” DuVal said.

Customers are grading banks on those basics. Celent’s global survey found 53% of consumers dissatisfied with their payment services and 39% dissatisfied with security and fraud protection. The research also found that trust weighs heavily on whether a customer stays or switches.

Reliability is a minimum. Customers increasingly trust institutions that understand them and anticipate their needs. Trust today sits where resilience, security, and relevance meet.

Business outcomes over broad strategy

The Temenos Innovation Hub in downtown Orlando houses product and technology teams focused on the US market, and gives visiting institutions a place to work hands-on with those teams.

Banks that came through the hub this year skipped the broad transformation talk and brought pointed questions. How do we launch faster? Reduce cost? Improve a customer journey? Increase resilience?

“Modernization is no longer a strategy discussion,” DuVal said. “It’s a business outcomes discussion.”

Regional banks, credit unions, challengers, and large banks each approach modernization differently. But they all share the challenge of balancing stability with innovation.

Where it goes next

The next phase will judge transformation by the value it delivers: faster time to market, lower costs, and stronger customer experiences. More institutions will need to prove they can modernize without giving up stability, and AI will become embedded in everyday operations.

“Success will be measured not by the technology banks adopt,” DuVal said, “but by the experiences they create and the outcomes they deliver.”

AI is the car, and you are the driver: Bank of America’s approach to AI learning

Most academic curricula do not yet include formal Gen AI instruction, so for many new hires, the first structured lesson in working with Gen AI happens on the job. At Bank of America, which has more than 200,000 teammates, the design of that lesson carries real weight.  This responsibility is overseen by The Academy, the bank’s award-winning onboarding, education, and professional development organization.

Michael Wynn, Academy Enterprise Learning and AI Strategy Executive, leads this work. He anchors it in a single metaphor: “AI is the car, and you are the driver.”

For Wynn, Gen AI training begins in the analog. New teammates receive a pen and write down the outcome they want, the context that matters, and how they will know whether an answer is good. Wynn calls it a reflection technique that shows “the value of slowing down to think before you prompt,” and it builds the critical thinking and problem definition that make later prompting sharper.

Judgment stays with the person

At The Academy, strategic prompt design workshops and responsible use of AI training come first. The opening prompting course introduces a “human in the lead” concept, so teammates understand from day one that they remain accountable for reviewing, editing, and approving anything AI produces. …


Why Salient bet everything on auto lending and never looked back

Most AI startups chase breadth. They build a capable, general-purpose product and sell it across as many industries as are willing to buy it. Ari Malik, CEO of Salient, took the opposite approach. He picked one vertical, auto lending, and went deep enough that he eventually moved his company’s headquarters to Los Angeles to be closer to a single customer, Westlake Financial.

Two years later, Salient is live inside roughly half of the top 20 auto lenders in the country. By Malik’s account, the company has never lost one. In today’s episode, he walks us through how a decision that “wasn’t really ideological” turned into a full-stack servicing layer now handling collections, total loss, compliance, and loss recovery for some of the largest lenders in the U.S.

The origin story is less a strategic plan than lived experience. Malik came to the problem through the finance side of a prior company, Tesla, where he got a close look at how tangled loan servicing had become. “The workflows in this hyper-regulated part of the economy were so tangled with compliance obligations, state-specific regulations, legacy systems that weren’t API-friendly or real-time,” he said, “that we sort of felt like you could build something generic and horizontal, and actually have it work.”

Malik’s conviction has only hardened as horizontal AI tools have tried to move into consumer lending and run headlong into compliance violations. For Malik, the read was simple: a market this large and this regulated was ripe for going deep.

Watch the episode

Listen to the full podcast

Subscribe: Apple Podcasts I SoundCloud I Spotify

Depth over breadth, by necessity

Salient’s vertical bet rests on two observations: the regulatory complexity of auto lending makes horizontal tools brittle, while the market itself is enormous. Roughly $800 billion in new U.S. auto debt is issued every year, backed by an army of human agents making calls, sending letters, and negotiating payments. “It was a structural problem that was sitting at the largest asset classes, right, and across the largest lenders in the U.S.,” Malik said.

The incumbent alternative, in his telling, was servicing handled through BPOs with little visibility and significant compliance exposure. That left room for “an excellent software solution” to compete on trust as much as efficiency. Malik is candid that there was no grand plan behind any of this – just a landscape that pointed toward one large, underserved problem rather than many small ones.

That thinking also drove Salient’s decision to relocate to Los Angeles and be in closer proximity to Westlake Financial. Malik calls it “probably the most important thing we’ve ever done as a company.” Working alongside Westlake’s compliance, servicing, and total-loss teams surfaced nuances that would have been invisible from a distance. “What we think is extraordinarily intuitive may not be for the customer,” he said.

AI maturity is landing unevenly across lenders

Malik gently pushed back on the assumption that consumer lending is still stuck at the “is this real?” stage of AI adoption. Two years ago, he said, that doubt was genuine. Salient reportedly ran a demo at the time, in which an AI-generated voice of “Steve Jobs” called lenders, and the reaction was disbelief that the call wasn’t prerecorded. That skepticism has largely faded, but unevenly.

Bulge-bracket banks, somewhat counterintuitively, have moved fastest. Malik described enterprise-grade lenders as “extraordinary fast adopters of deploying AI not only in a consumer-facing way but also at the back end on the workflow side, where they can accrue more value.” Mid-market lenders and fintechs, by contrast, have been more hesitant, which he attributes to having less exposure to the cost and regulatory pressures pushing larger institutions to act.

The pitch has changed accordingly. Where the early conversation was about risk (what happens if the AI says something wrong), the argument now, backed by data from the largest deployments, is that AI can be safer and more compliant than a human workforce, with measurable improvements in roll rates. This reframing, Malik said, “hasn’t really percolated down fully yet to the smaller fintech.”

A product stack built by customer pull

Salient started with Taylor, a voice agent handling collections, servicing, and total-loss calls. The rest of the stack, Malik said, came from lenders pulling the company deeper into their workflows rather than from an internal roadmap. Calls that appeared resolved on the surface kept spawning downstream work: a credit dispute or chargeback that got routed to a human queue and sat there for two weeks. “We were like, this is taking two weeks. Why is this taking so long? We should resolve this with the customer,” Malik said. So Salient built that piece too.

Marshall, the company’s compliance and QA product, emerged the same way. As Salient’s consumer-facing tools scaled inside regulated institutions, lenders started asking how to prove the AI itself was compliant: audit trails, model risk documentation, and system-of-record checks. Rather than lenders hiring more staff to police the new technology, Malik said the response was to “create this product called Marshall, and it will automate compliance monitoring, QA monitoring, checking the system of record, cleaning it up, and outputting almost an audit report that can go to regulators.” 

From there, the suite expanded into total loss, credit-card chargebacks, and charge-offs, each one a response to a specific pain point rather than a feature added for its own sake.

Selling risk to banks, efficiency to everyone else

The sales conversation, Malik said, changes entirely depending on who’s buying. Mid-market and non-bank lenders respond to efficiency: handle time, operating expenses, recovery dollars, and scalability. Bulge-bracket banks are a different animal entirely, involving a steering committee, a compliance team, a vendor risk team, IT security, and legal review. “I had a lot more hair before we started navigating through bulge-bracket banks,” he joked. 

With that audience, the real conversation is about risk reduction, model-risk documentation under frameworks like SR 11-7, and satisfying regulators such as the OCC.

Notably, Salient doesn’t have a dedicated sales team. Malik said essentially every customer has come through referrals, and he stays personally involved in every large enterprise relationship, checking in with customers weekly or monthly. He describes the signal that a lender has truly bought in not as a single moment but as a change in tone: the question stops being whether Salient can do something and becomes when. “That kind of shows that they’ve internalized this daily as part of their almost key operating model, rather than a pilot that’s constantly being run,” he said.

The clearest evidence of that model working is Westlake, which set Salient a target of $15 million in annual savings. Deploying the technology across collections, total loss, and compliance didn’t just cut costs. Average handle time dropped, compliance violations dropped, and findings dropped alongside them. Malik said Salient’s mapping of Westlake’s customer interactions found that roughly 80% of use cases could be handled entirely by AI, freeing human agents for cases that actually require judgment. 

The pitch, as he frames it, moved “from just being this weird, fun toy or experiment of generative AI… into a service quality story, into a risk mitigation story.”

What the industry is still underestimating

Malik sees the biggest opportunity in making loss recovery predictive and individualized. Historically, treatment has been bucketed by simple delinquency rules rather than who a customer actually is. His example: two customers each miss two payments in the last 60 days, one with a poor payment history and the other who has never missed a payment. Under most current systems, they’re treated identically. Malik wants recovery decisions to reflect those differences, keeping good customers with the brand through a difficult stretch rather than pushing them out over one short-lived data point.

Looking ahead, Salient plans to launch three new products by the end of 2026, with Malik less involved in the day-to-day than he was in the company’s earlier years. “We’d really like to do it without me being super in the weeds on day one, but trusting my team to do more of it,” he said. 

It’s a fitting next step for a founder who has spent two years arguing that the way to serve a fragmented, regulated industry well is to get close enough to understand it completely, then build precisely for what you find.

Nubank intends to paint the U.S. banking system purple

Nubank has officially begun serving customers in the United States, rolling out an initial lineup built around high-yield savings, a no-fee credit card, and low-cost international transfers through its U.S. banking partner, Lead Bank.

Speaking at a launch event in Miami, founder and CEO David Vélez and co-founder and head of the U.S. business laid out how the company’s entry product lineup consists of deposit accounts paying 3.50% annual yield, fee-free international remittances, and a no-annual-fee credit card that offers 1.5% cash back on purchases. 

In January, Nubank’s application for a national bank charter received a conditional approval from the Office of the Comptroller of the Currency, and the firm is now undergoing review by the Federal Reserve and the FDIC. Junqueira told the Miami audience that she expects Nubank to be fully operational under its own charter sometime next year.  Until then, the company will run its U.S. business through its partner-bank arrangement, which is a common structure among fintechs entering the American market.

What made Nubank work in Brazil

Nubank’s Brazilian rise is usually explained as a story of timing and temperament. When David Vélez, Cristina Junqueira, and Edward Wible founded the company in 2013, a handful of large incumbent banks controlled the vast majority of Brazil’s banking market and were known for high fees, branch-bound bureaucracy, and poor service. 

Sequoia Capital, where Vélez had worked as a partner, describes the setup as a near-monopoly that had gone unchallenged for decades, and frames Nubank’s rise as an underdog campaign against that entrenched oligopoly, one built around a level of consumer experience Brazilian banking customers had never been offered.

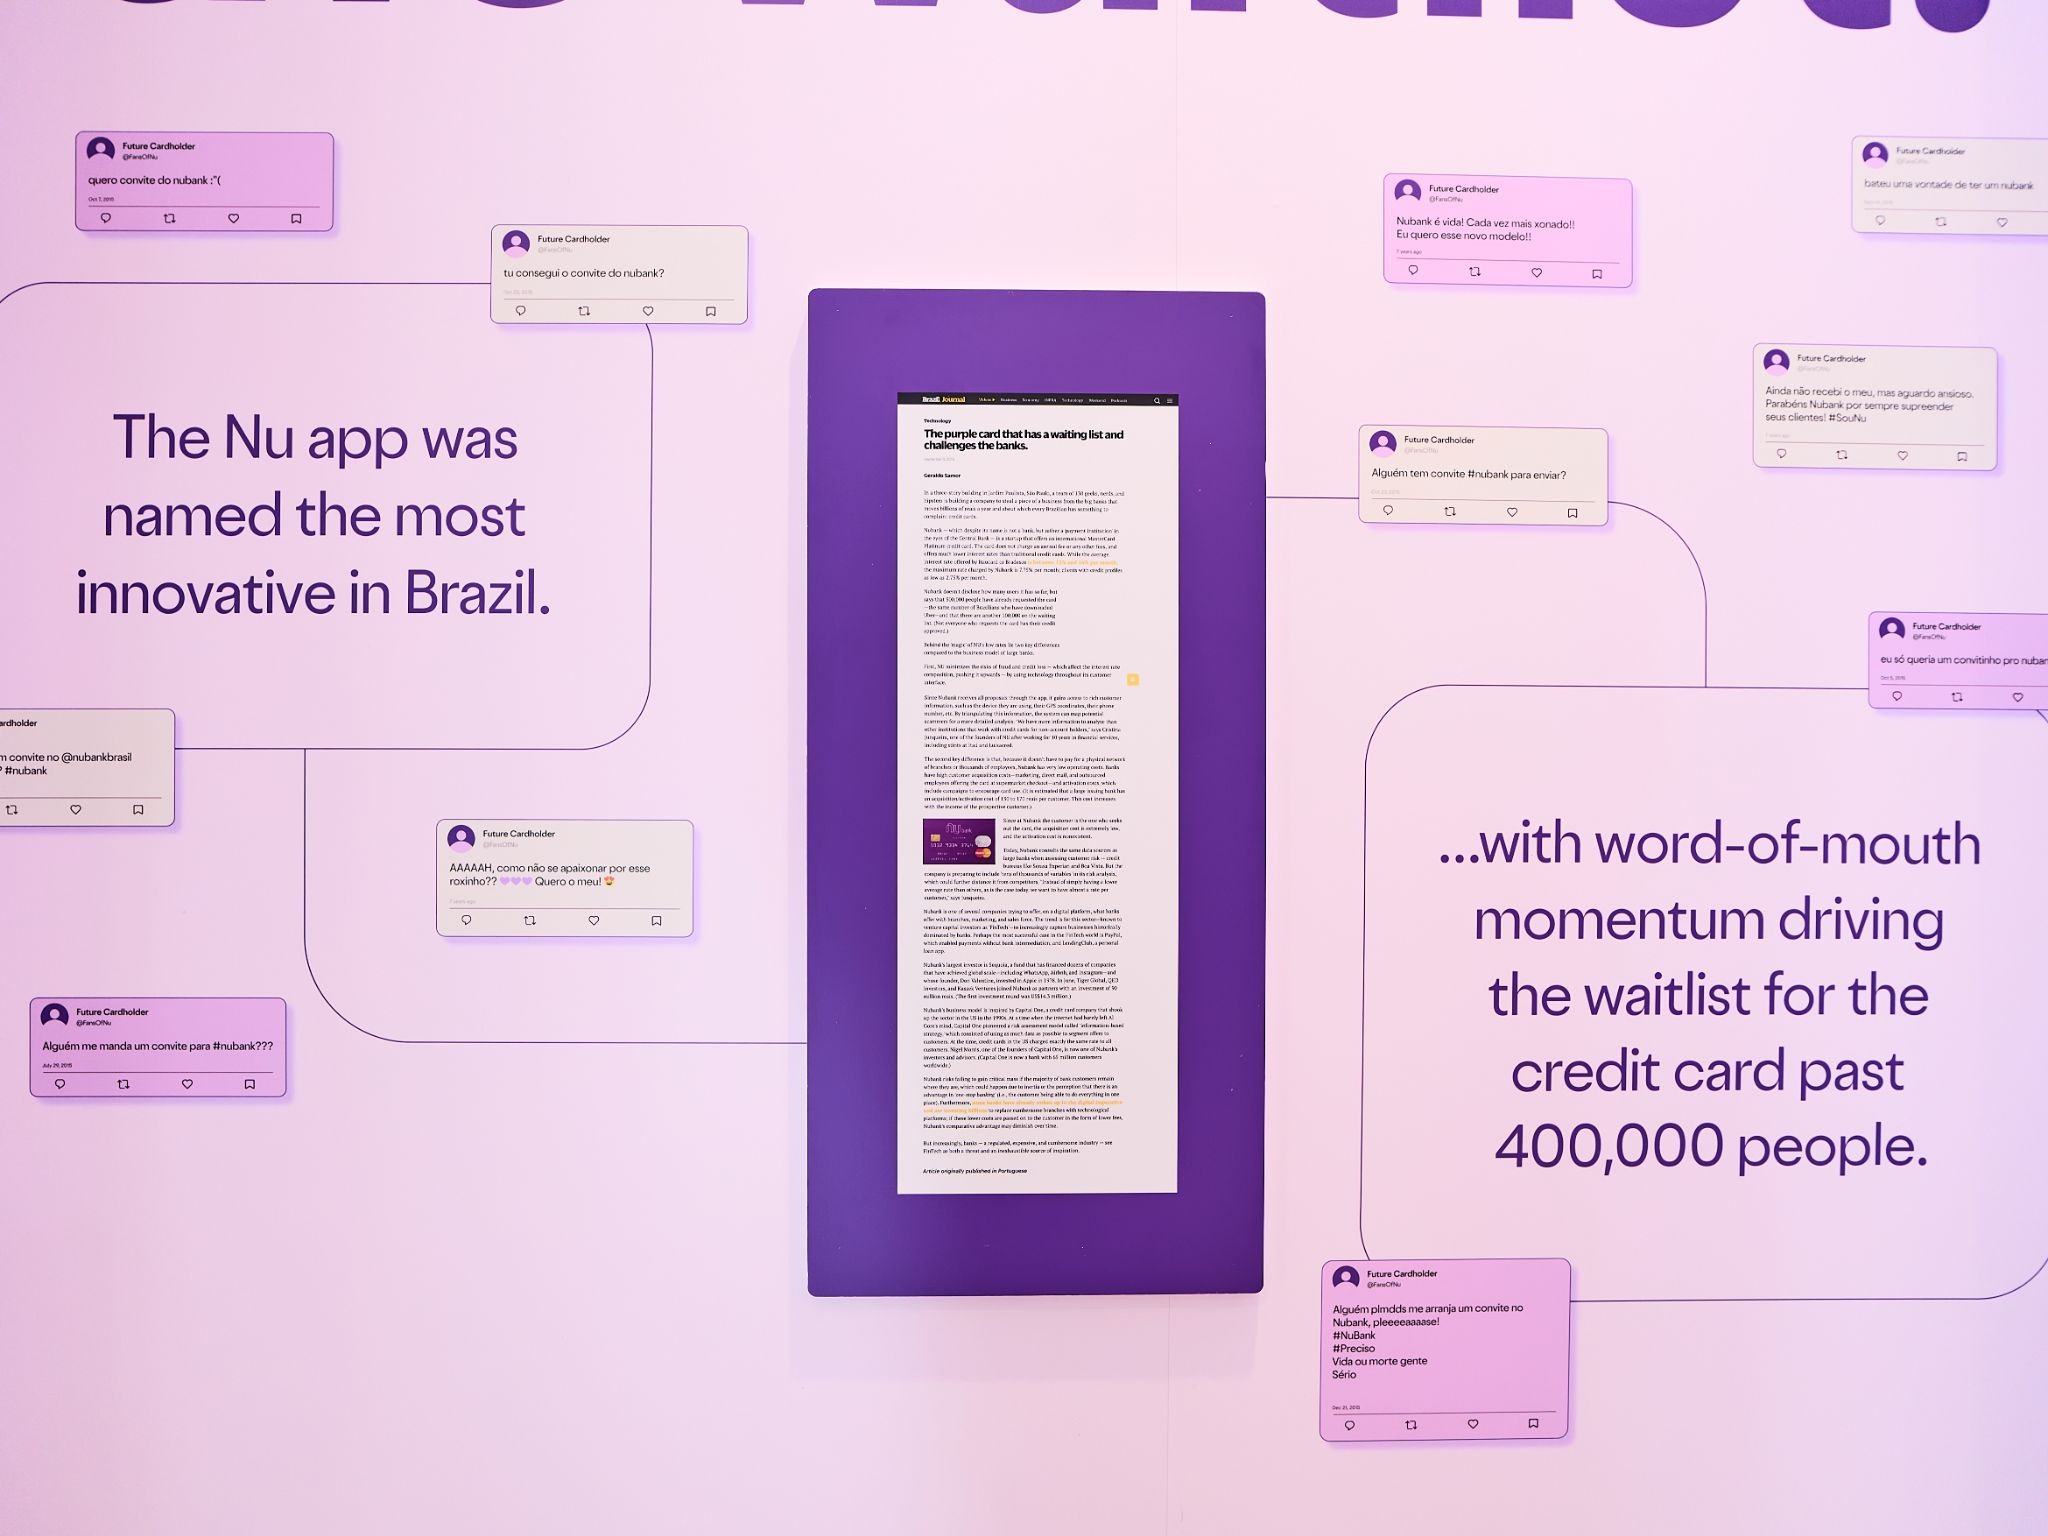
The company started small: its first product was a purple credit card, chosen in part because it was one of the few financial products in Brazil that didn’t require Nubank to hold a banking license. From there, the strategy leaned on eliminating the fees Brazilians resented most: Nubank charges no account maintenance or overdraft fees, arguing that customers shouldn’t have to pay to manage their own money. That mattered enormously in a country where large numbers of lower-income Brazilians had effectively opted out of formal banking because fees ate into thin balances. Going fully digital and branch-free allows Nubank to pass those savings back to customers while also reaching people traditional banks had largely written off.

Nubank also rebuilt underwriting from scratch. Rather than relying on the thin credit files that shut many Brazilians out of formal credit, it used alternative data to assess risk. In a single year,  the company brought 5.7 million previously excluded people into the credit-card market. 

The results have compounded over time. Nubank now serves over 60% of Brazil’s adult population and, by some measures, has overtaken Itaú and Caixa to become the country’s most valuable financial brand, all without ever operating a physical branch network.

Why the U.S. bet is interesting

…


The Quarterly Review: BNY’s Carl Slabicki is pushing toward practical innovation


In this edition, we spotlight Carl Slabicki, Head of Commercial for Global Payments & Trade at BNY. 

At BNY, Carl Slabicki oversees the firm’s work connecting payments, liquidity, and trade for clients navigating an increasingly always-on financial landscape. BNY has long been a central player in global custody and treasury services, and under Slabicki’s tutelage over these past few months, its footprint has been expanding into more integrated, cross-capability solutions spanning digital assets, data, and AI. 

In this edition, Slabicki dives into how BNY is moving clients from broad modernization conversations toward practical and measurable execution, and how this shift is shaping the firm’s approach to client relationships, market education, and commercial strategy.

…

The Quarterly Review: PayPal’s Jeff Pomeroy on scaling the firm’s payment services, and how crypto and agentic commerce fit in

In this edition we will spotlight Jeff Pomeroy, Payment Services & Crypto.

Executive Summary

Six months after setting an ambitious agenda that included unifying PayPal’s global platform, expanding in-store, and scaling value-added services, Jeff Pomeroy is back on The Quarterly Review with progress to show on all three.

He also plants a flag on a newly broadened mandate: one platform for every business, every channel, and every payment modality — future-proofed with crypto and agentic commerce. And he shares his read on trends worth watching, including where he thinks the next durable moat in payments will be built, and what he’s doing to build it.

“When we last spoke, I framed our work around one idea: intense focus,” Pomeroy said. “Now I’m coming up for air to tell you about it.”

Here is what Pomeroy and his team have accomplished since our last conversation:

  • Made value-added services like network tokenization self-serve, converting nearly all merchants in a recent free-trial.
  • Closed a string of omni-channel deals via Verifone, including PayPal’s first omnichannel government contract.
  • Brought Australia and Europe fully onto PayPal’s unified platform and began moving processing in-house.
  • Broadened his remit into a new org, Payment Services & Crypto, unifying enterprise, small-business, crypto, and agentic commerce.

The Full Review

A few quarters ago, Pomeroy set three priorities for PayPal’s enterprise payments business: a unified global platform, in-store expansion via Verifone, and scaled value-added services. Six months later, he’s back with what he calls a clean sweep.

“The short version is that we stayed the course,” Pomeroy said. “This is an industry that produces a new shiny object every week, and most of the discipline is in not chasing it.”

That discipline came from guardrails he’d put in place, measuring every initiative against merchant demand, ROI, and contractual obligations.

“That discipline is showing up exactly where it should,” he said, “in the deals we’re closing, the services merchants are turning on, and how we’re executing in the public market.”

Objective 01: Scaling value-added services

Six months ago, the goal was to scale value-added services — network tokenization, smart retries, debit routing, and payouts. Pomeroy says that work has moved from launch to self-serve: merchants can now go into their portal, look at their own reporting, and switch on some of PayPal’s most meaningful services themselves.

“That’s a different business than the one we had a year ago,” he said.

The bigger challenge, he says, was getting merchants to understand what they’re worth. So his team built a proof mechanism that turns on network tokens for free and lets merchants watch what it does to their own numbers.

“We did exactly that with hundreds of merchants recently, and all but one kept the tokens on at the end of the trial,” he said, “because once they could see the value it returned to their payments experience, the decision made itself.”

His team built tooling that surfaces a merchant’s own performance data such as auth rates and costs. “That lets us walk in with the merchant’s own performance in front of us and have a real conversation instead of a sales pitch,” he said.

The team’s speed comes from process restructuring and optimization. PayPal has leaned into AI internally to reduce time-to-live for products, freeing teams to focus their judgment on the parts of a payments problem that actually need a human who understands how the rails behave.

“AI doesn’t replace that,” he said. “It clears the runway so we get to it faster.”

Objective 02: Winning in-store and omni-channel

The Verifone partnership remains, in Pomeroy’s words, the spine of PayPal’s move into physical retail, and he says the deals are coming through. His team has closed an array of omnichannel deals with real net-new volume, despite a deliberately small team in market and a pipeline several times larger than its previously closed business. Among the wins is PayPal’s first government deal in omnichannel.

“Which is not the kind of logo you expect to win in payments this early,” he said, “and exactly the kind of proof point that tells you the model works.”

But Pomeroy is clear that in-store is only part of the ambition. The bigger goal is making PayPal’s and Venmo’s own wallets feel as natural in a physical store as they already do online. He reaches for a nautical analogy to describe why offline is where the growth now lives.

“When we first docked twenty years ago, it was a quiet marina, and it was all ours,” he said. “Now it’s become pretty crowded. So, what do you do when the marina is full? You go find new water to sail. Offline is clear, open water.”

Pomeroy wants a PayPal or Venmo transaction to flow as seamlessly in person as tapping a card, and he wants merchants to offer those wallets first, every time. However, this ambition is additive rather than exclusive.

“We will always take a payment,” he said. “Our obligation is to bring merchants and consumers into these new environments so that every part of the business rises with them.”

Objective 03: One unified platform, globally

Of the three original priorities, Pomeroy says platform unification has been the most satisfying to watch land. Australia is now fully live on PayPal’s global stack, and so is Europe, for both new business coming in and the existing book of merchants. By the end of the year, he expects the migration to be complete, putting every market on one unified payment stack.

“And we’re not stopping at routing transactions through partners,” he said. “The next step is bringing more of the processing in-house, which is already live in its first market.”

The point, Pomeroy stressed, is that the merchant experience stays constant even as the infrastructure underneath it changes. “The merchant keeps one connection the entire time,” he said. “The plumbing behind it changes; their experience doesn’t.”

The bigger mandate: Payment Services, Crypto, and Agentic

Pomeroy’s remit has broadened into a new organization, Payment Services & Crypto, sharpening what he once described as PayPal’s North Star.

“We want to become a flexible platform for all businesses, operating in every channel, with every payment modality,” he said.

Practically, that means merging enterprise and small-business processing into one center of payment excellence. “The question was when, not if,” he said. “The levers we built on the enterprise side and the levers that have lived in small business no longer have to live in separate boxes.”

Crypto belongs on that same platform, he argues. With more than 600 million crypto wallets globally, he sees efficiency gains across settlement, cross-border payments, and payouts.

“It’s becoming part of the global financial infrastructure, and at that point it can’t be a separate business anymore,” he said. “Putting payments and crypto under one roof is how you bring scale and speed to both.”

He also flagged a distribution gap: much of PayPal’s volume now arrives through platforms like BigCommerce, Wix, WooCommerce, and Shopware, where its value-added services have historically been unavailable. “The next leg of the journey is getting our services onto all of those surfaces, so it stops mattering how a merchant reaches us,” he said.

Pomeroy also names agentic commerce as an area he’s watching closely. “In thirty years in payments, you almost never see a genuinely new channel appear,” he said, “and this is one.” With AI agents projected to drive trillions in commerce by decade’s end, he sees the infrastructure for that shift as still unbuilt at scale. “You earn the right to answer those questions by building the foundation and putting up the volume,” he said. “Then you’ve won.”

A word for other leaders

Last time, Pomeroy talked about the leadership habits he tries to model, building a culture that sticks, empowering people rather than making them ask for permission, and carving out time to think. This time, his advice for other leaders is more compact.

“It is too easy to be distracted by the news cycle,” he said. “Focus in on what you can deliver, what drives value for your customers, and where your teams actually take pride in delivering things in a very focused and measurable way. That’s the whole game.”

This may be the final entry in this particular check-in series, but Pomeroy isn’t ready to close the book entirely.

“I know this series is over,” he said, “but I’d love to check in again next year to talk about how our North Star is coming into clearer focus.”

How BILL is becoming the financial backbone of the SMB economy

For most small and midsize businesses, financial operations remain a tangle of disconnected systems: A payroll platform over here, an ERP over there, and a manual AP process stitching them together with spreadsheets. 

BILL has spent the past year making a systematic argument that this doesn’t have to be the case. Through a rapid series of embedded partnerships and a suite of AI Agents, the San Jose-based fintech is positioning itself as the infrastructure layer that powers intelligent finance across the platforms SMBs already trust.

Proving the model: Building where businesses already work

Embedded finance partnerships between payroll, ERP, and AP platforms are still nascent, and the playbook for doing them well is still being written. BILL’s approach offers an early view of what that playbook might look like.

In the span of just a few months in late 2025, BILL announced embedded partnerships with three of the most consequential platforms in the SMB stack – two ERP platforms and a payroll provider – demonstrating how a single payments infrastructure layer can be woven into the platforms SMBs already rely on daily.

ERP platforms: BILL’s AP automation embeds directly into ERP platforms, giving customers a payment experience, capturing bills, paying vendors, and reconciling payments in real time, all without leaving their system of record.

Payroll and HR platforms: Integrating AP into payroll platforms alongside HR functions brings people management and vendor payments together for the first time — a combination that reflects the converging expectations of SMB operators.

Russell Kornman, Director of Product, Developer and Partner Platform at BILL, describes the approach as deliberately choosing depth over reach. “When a partner chooses BILL, they’re not just outsourcing payments plumbing,” he says. “They’re choosing to not rebuild something that already exists and is hard to get right. AP and payments aren’t just features – it’s rails, KYC/KYB, vendor onboarding, risk, and compliance. That’s years of work and ongoing cost.”

The beginning of a broader industry trend

These partnerships are still early-stage, proof points in what BILL views as a long-term infrastructure play. The embedded finance category is young, and the integrations being built today may look markedly different in three to five years. What matters now is who is developing the conceptual framework for how this should work.

BILL’s early moves suggest it is competing to define that framework. By embedding payments rails, compliance infrastructure, and an eight-million-business network into partner platforms — rather than building a standalone destination product — BILL is making a deliberate bet on where SMB financial operations are heading: away from point solutions and toward unified, intelligent workflows that work inside the tools people already use.

From system of record to system of execution

What makes the ERP integration model technically significant is how it reframes what an ERP is actually for. Traditional ERP implementations treat the system as a ledger, a place to record what happened. BILL’s embedded model pushes that further.

“Embedding BILL into an ERP turns AP from a multi-system process into a single flow,” says Kornman. “Users can select bills, pay them, and see status and reconciliation come back in near real time, all without leaving the ERP. That removes things where breaks occur for customers today: exports, file uploads, duplicate entry,” he added.

For cloud ERP customers, a complementary integration adds an AP layer alongside existing receivables capabilities.  Together, they create a complete pay-in and pay-out experience inside one platform. “BILL’s role is bringing a best-in-class AP engine and payments network into these systems  so customers get a stronger AP experience without the platform having to build and maintain it themselves,” Kornman said.

Converging people and payments

There is a convergence of workforce management and financial operations unfolding in the SMB space. For SMBs that have historically juggled HR, payroll, and vendor payments across separate systems, the direction of travel is toward a genuinely unified back office.

Kornman frames it as both a product opportunity and a strategic one. “Payroll, HR, and vendor payments are converging, and customers increasingly want that in one place. By embedding BILL inside a leading payroll platform, we become the financial operations layer within the HR tools SMBs already rely on.”

According to BILL’s research, 62% of SMBs cannot immediately view their current cash position across all accounts, and nearly 40% of businesses that haven’t yet automated their financial operations plan to do so within six months. Integrations like this meet that demand by delivering clarity, speed, and control inside a platform hundreds of thousands of SMBs already use daily.

The network effect at scale

Underlying all three partnerships is an asset that competitors would find difficult to replicate quickly: BILL’s network. With more than eight million businesses connected across its platform, BILL processes roughly 1% of U.S. GDP annually. When any partner embeds BILL, they gain instant access to a vendor network that reduces onboarding friction, accelerates electronic payments, and raises the floor on payment security.

“Customers can increasingly find and pay vendors already on the network, which reduces onboarding friction, cuts down on checks, and drives more secure electronic payments,” Kornman notes. “As more customers join the network, the experience only improves.”

This network advantage compounds over time, and it provides the foundation for BILL’s most ambitious move yet.

Agentic AI and the Fortune 5 million

In late October 2025, BILL launched BILL AI: A suite of AI agents specifically designed for what CEO René Lacerte calls the “Fortune 5 Million”: the small and midsize businesses that power the U.S. economy but have historically been underserved by enterprise-grade automation.

The initial agents are focused on eliminating the most painful manual workflows in SMB finance: BILL’s W-9 agent autonomously requests, collects, and pre-validates tax forms from vendors, eliminating over 80% of the manual steps in a process that over 90% of business leaders describe as the most painful part of tax season. 

Other agents like the reconciliation agent automatically codes card transactions so receipts reconcile themselves, with early rollouts showing a 533% increase in transactions coded entirely by AI. An agentic onboarding feature for Spend & Expense automatically creates virtual cards and permissions so new employees can begin spending compliantly from day one.

These agents are trained on more than $1 trillion in transactions and 1.3 billion documents – proprietary data that gives BILL’s AI a head start no synthetic dataset can replicate. And critically, they are woven directly into the embedded partner ecosystem. “Instead of building their own AI stack, partners will be able to offer capabilities like automated invoice capture and coding, anomaly detection, and approval recommendations,” says Kornman. “That raises the bar for what their platforms can deliver without adding complexity on their side.”

The embedded finance model is still early. The partnerships being built today are first-generation integrations, and the industry is still working out what “done” looks like. But BILL’s approach – leading with infrastructure, network effects, and proprietary AI, reflects a considered view of where SMB financial operations are heading. In a fragmented market, the company that builds the rails often ends up running the trains.

Why banks can’t policy their way out of shadow AI

Employees at financial institutions are using AI tools their employers never approved for tasks that touch sensitive customer data.  This unsanctioned use of AI, often called shadow AI, is not a toothless problem. In May 2026, an employee at Pennsylvania-based CB Financial Services, parent company of Community Bank, uploaded a file containing customer names, Social Security numbers, and dates of birth into an unauthorized AI application while preparing a presentation. The employee bypassed the bank’s approved AI tool for a personal account on a personal device.  The bank caught the exposure quickly enough to get the data deleted before it could be used to train the vendor’s model. Notably, the bank already offered a sanctioned AI tool. The employee simply chose not to use it.  The instinct inside most banks and credit unions is to treat this as a policy failure and respond with tighter restrictions, more monitoring, and firmer language in the acceptable-use policy. But that response gets the diagnosis wrong, according to Corey Gross, VP and Head of Data & AI at Q2 Holdings. “When employees bypass a sanctioned tool, they’re telling leadership teams that the approved option isn’t getting the job done.” In his view, the root cause sits upstream of governance entirely: institutions are buying AI tools without first understanding the workflows those tools are meant to support. Instead of writing stricter acceptable-use policies, Gross suggests the more useful question is why employees felt they needed to go around the tool they were given in the first place. “It’s rarely a governance or compliance issue,” he said.

The distinction sounds subtle, but it points to a different set of priorities for any bank trying to scale AI responsibly. It suggests that starting with the design of the work itself is more critical than the framing of the rules that surround it.

Workflow redesign has to come before the AI rollout

…