
Banking, Banking as a service, Member Exclusive

How Thread Bank is turning a century-old charter into a modern distribution engine

  • What it takes for a bank to scale in the US today – and still stand out – in a market where innovation is easy to claim but regulatory credibility is far harder to earn.
  • Thread Bank offers a useful lens into this reality. It operates through a partnership-led embedded banking model to expand its distribution and reach new clients.
close

Email a Friend

How Thread Bank is turning a century-old charter into a modern distribution engine

The competitive landscape for US community banks is expanding beyond traditional boundaries. Fintechs and digital entrants, including a growing wave of foreign neobanks, are pursuing US charters to scale and strengthen their foothold in the region. Against this backdrop, the emerging question is: what it takes for a bank to scale in the US today – and still differentiate – in a market where innovation is easy to claim but regulatory credibility is hard to earn.

Tennessee-based digital-first Thread Bank offers one lens into that reality. Its strategy sits at the intersection of embedded banking, deliberate scaling, and regulatory boundaries. The bank operates primarily through a partnership-driven embedded banking approach to expand its distribution and reach new clients.

The anatomy of Thread Bank – From community bank to infrastructure layer

The history: Thread Bank was founded on the foundation of Civis Bank, a community bank originally established in 1906 in Tennessee. A group of investors recapitalized the struggling Civis Bank in 2021 – a $90 million-asset institution – with an initial $47 million injection, ultimately building the platform to over $100 million in Tier 1 capital. It was then subsequently renamed and rebranded as Thread Bank in 2022 to focus on digital and embedded banking.
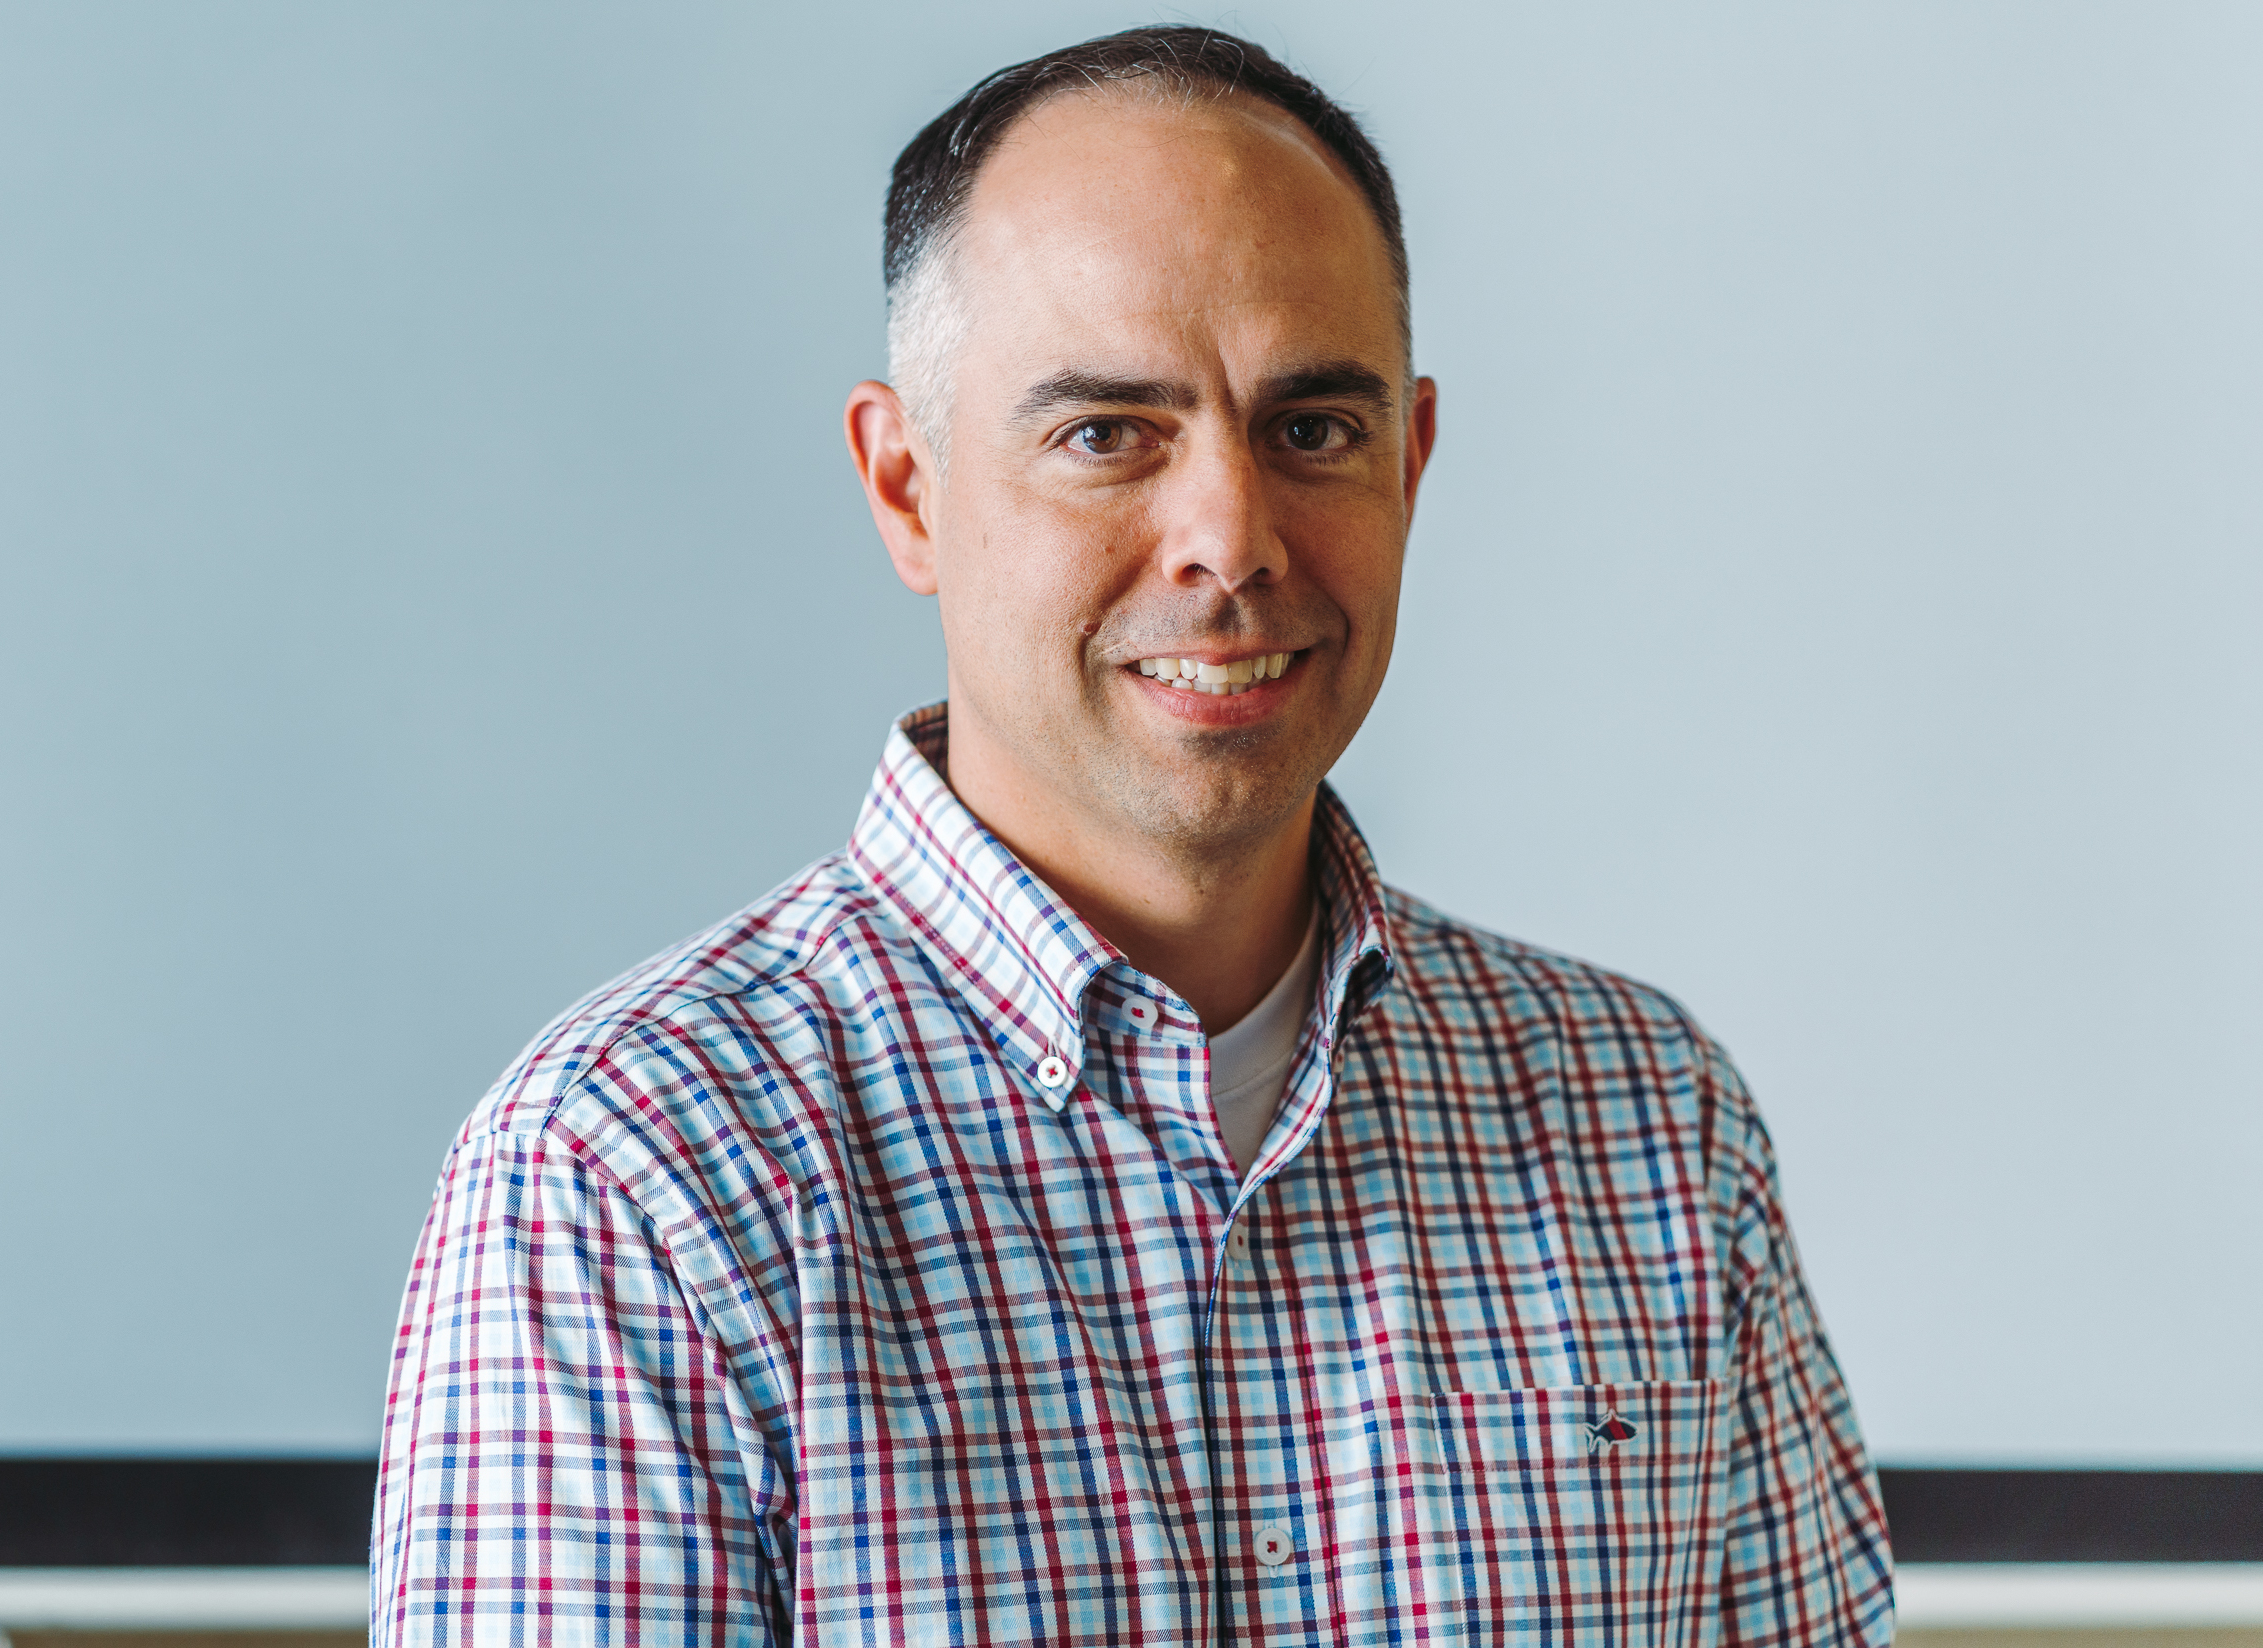
Chris Black, CEO and President of Thread Bank

“We combine more than a century of community banking heritage with modern, cloud-based infrastructure to provide full-suite digital banking capabilities,” says Chris Black, CEO and President of Thread Bank. “Together, these services transcend traditional geographic limitations while integrating seamlessly into our partners’ existing platforms.”

  …

Tearsheet Pro

0 comments on “How Thread Bank is turning a century-old charter into a modern distribution engine”

10-Q, Member Exclusive

Fifth Third is trying to make a bigger bank feel simpler

  • Fifth Third is simplifying its lineup as it grows, giving customers clearer products built around specific financial needs.
  • Its broader strategy is to expand what the bank can do while making the user experience feel increasingly simple.
Sara Khairi | September 11, 2026
Banking, Member Exclusive, Podcasts

Venture banking 3.0: How Stifel is rebuilding trust after Silicon Valley Bank

  • Stifel's Katya Kohen explains how venture banking is being rebuilt into what she calls 3.0 after Silicon Valley Bank's collapse.
  • She breaks down why bigger banks and neobanks each fell short of replacing SVB, and why venture debt has become essential capital for AI founders.
Zack Miller | September 09, 2026
Member Exclusive, The Quarterly Review

The Quarterly Review: BNY’s Carl Slabicki is pushing toward practical innovation

  • Carl Slabicki is Head of Commercial for Global Payments & Trade at BNY, where he leads client strategy across payments, liquidity, and trade for the firm's global commercial clients.
  • This quarter, Slabicki is focused on connecting capabilities across BNY, driving practical modernization, and grounding conversations around digital assets and AI in client execution.
Rabab Ahsan | September 08, 2026
Member Exclusive, Opinion

The infrastructure paradox: The better you become, the harder customers are to keep

  • Financial infrastructure is becoming part of the business itself, changing what customers are willing to outsource.
  • Providers now have to grow with their customers and keep expanding their value as those customers begin to question how much of the stack they should continue to outsource.
Sara Khairi | September 04, 2026
Business of Fintech, Member Exclusive

Financial firms are building new businesses from the layers beneath their products

  • Intuit is opening up its financial intelligence to AI agents, while SoFi is making its infrastructure programmable.
  • Both firms are betting that the layers beneath their products can become businesses in their own right, creating value across new interfaces, businesses, and customer relationships.
Sara Khairi | September 03, 2026
More Articles