

Banks have moved past whether to modernize. Now they want outcomes.
- At Temenos Regional Forum Americas, bankers set aside the case for modernization and focused on execution: how to modernize without disrupting critical systems, and where AI delivers measurable value.
- Launch speed, cost, and customer experience have become the yardsticks for transformation, as trust expands beyond reliability to include relevance.
The debate over whether banks should modernize their core technology is largely settled. The question now is how to do it without putting the systems customers depend on at risk.
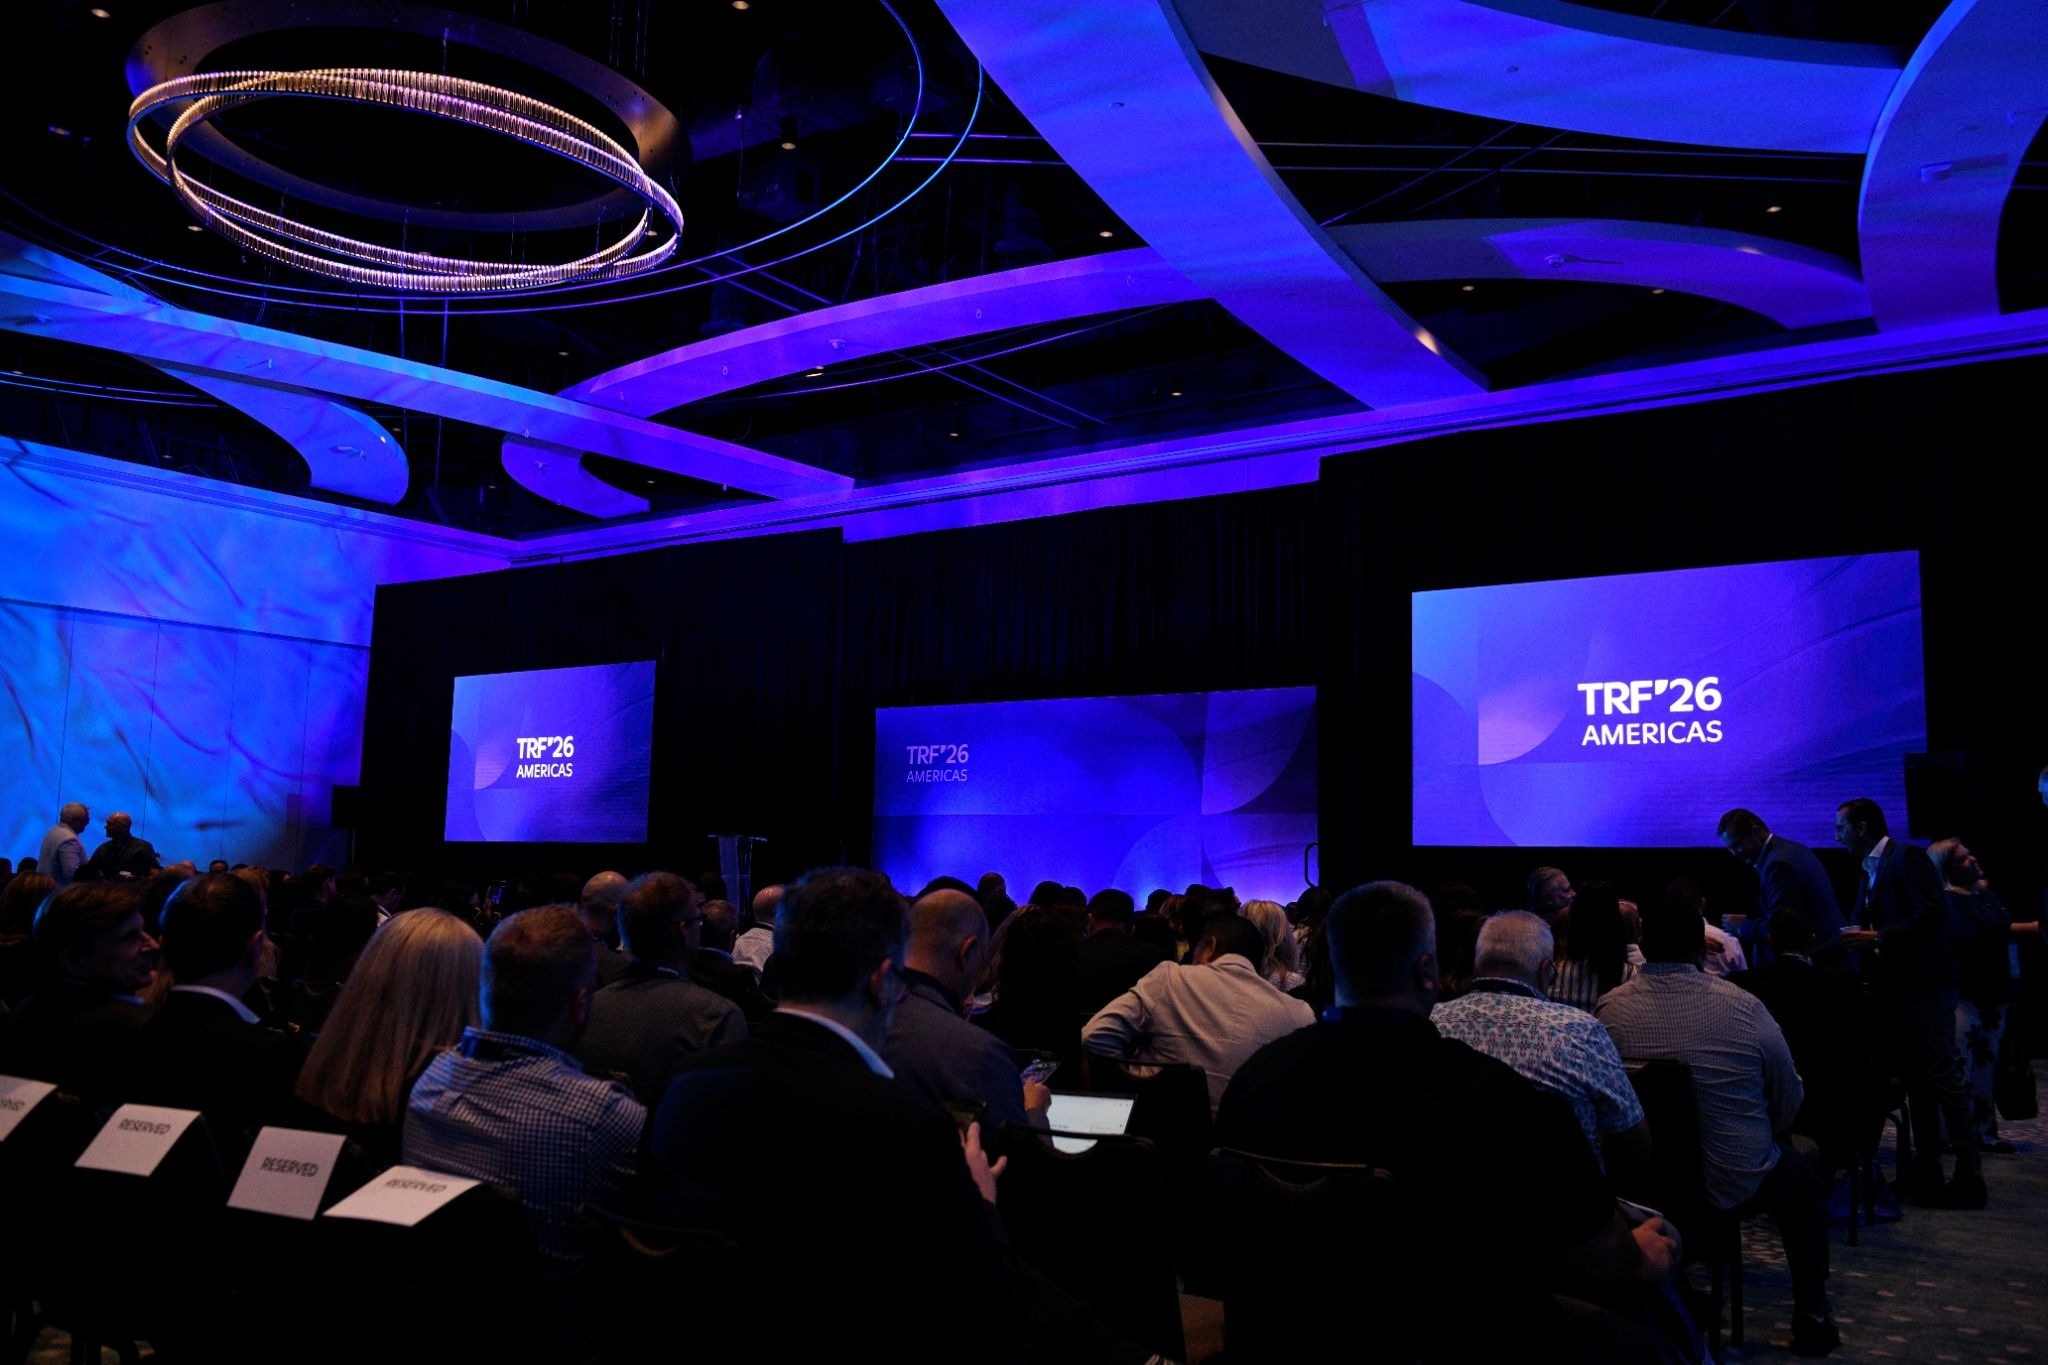
This evolution has shaped Temenos Regional Forum Americas in Orlando, where more than 350 customers, partners, prospects, and industry leaders gathered.
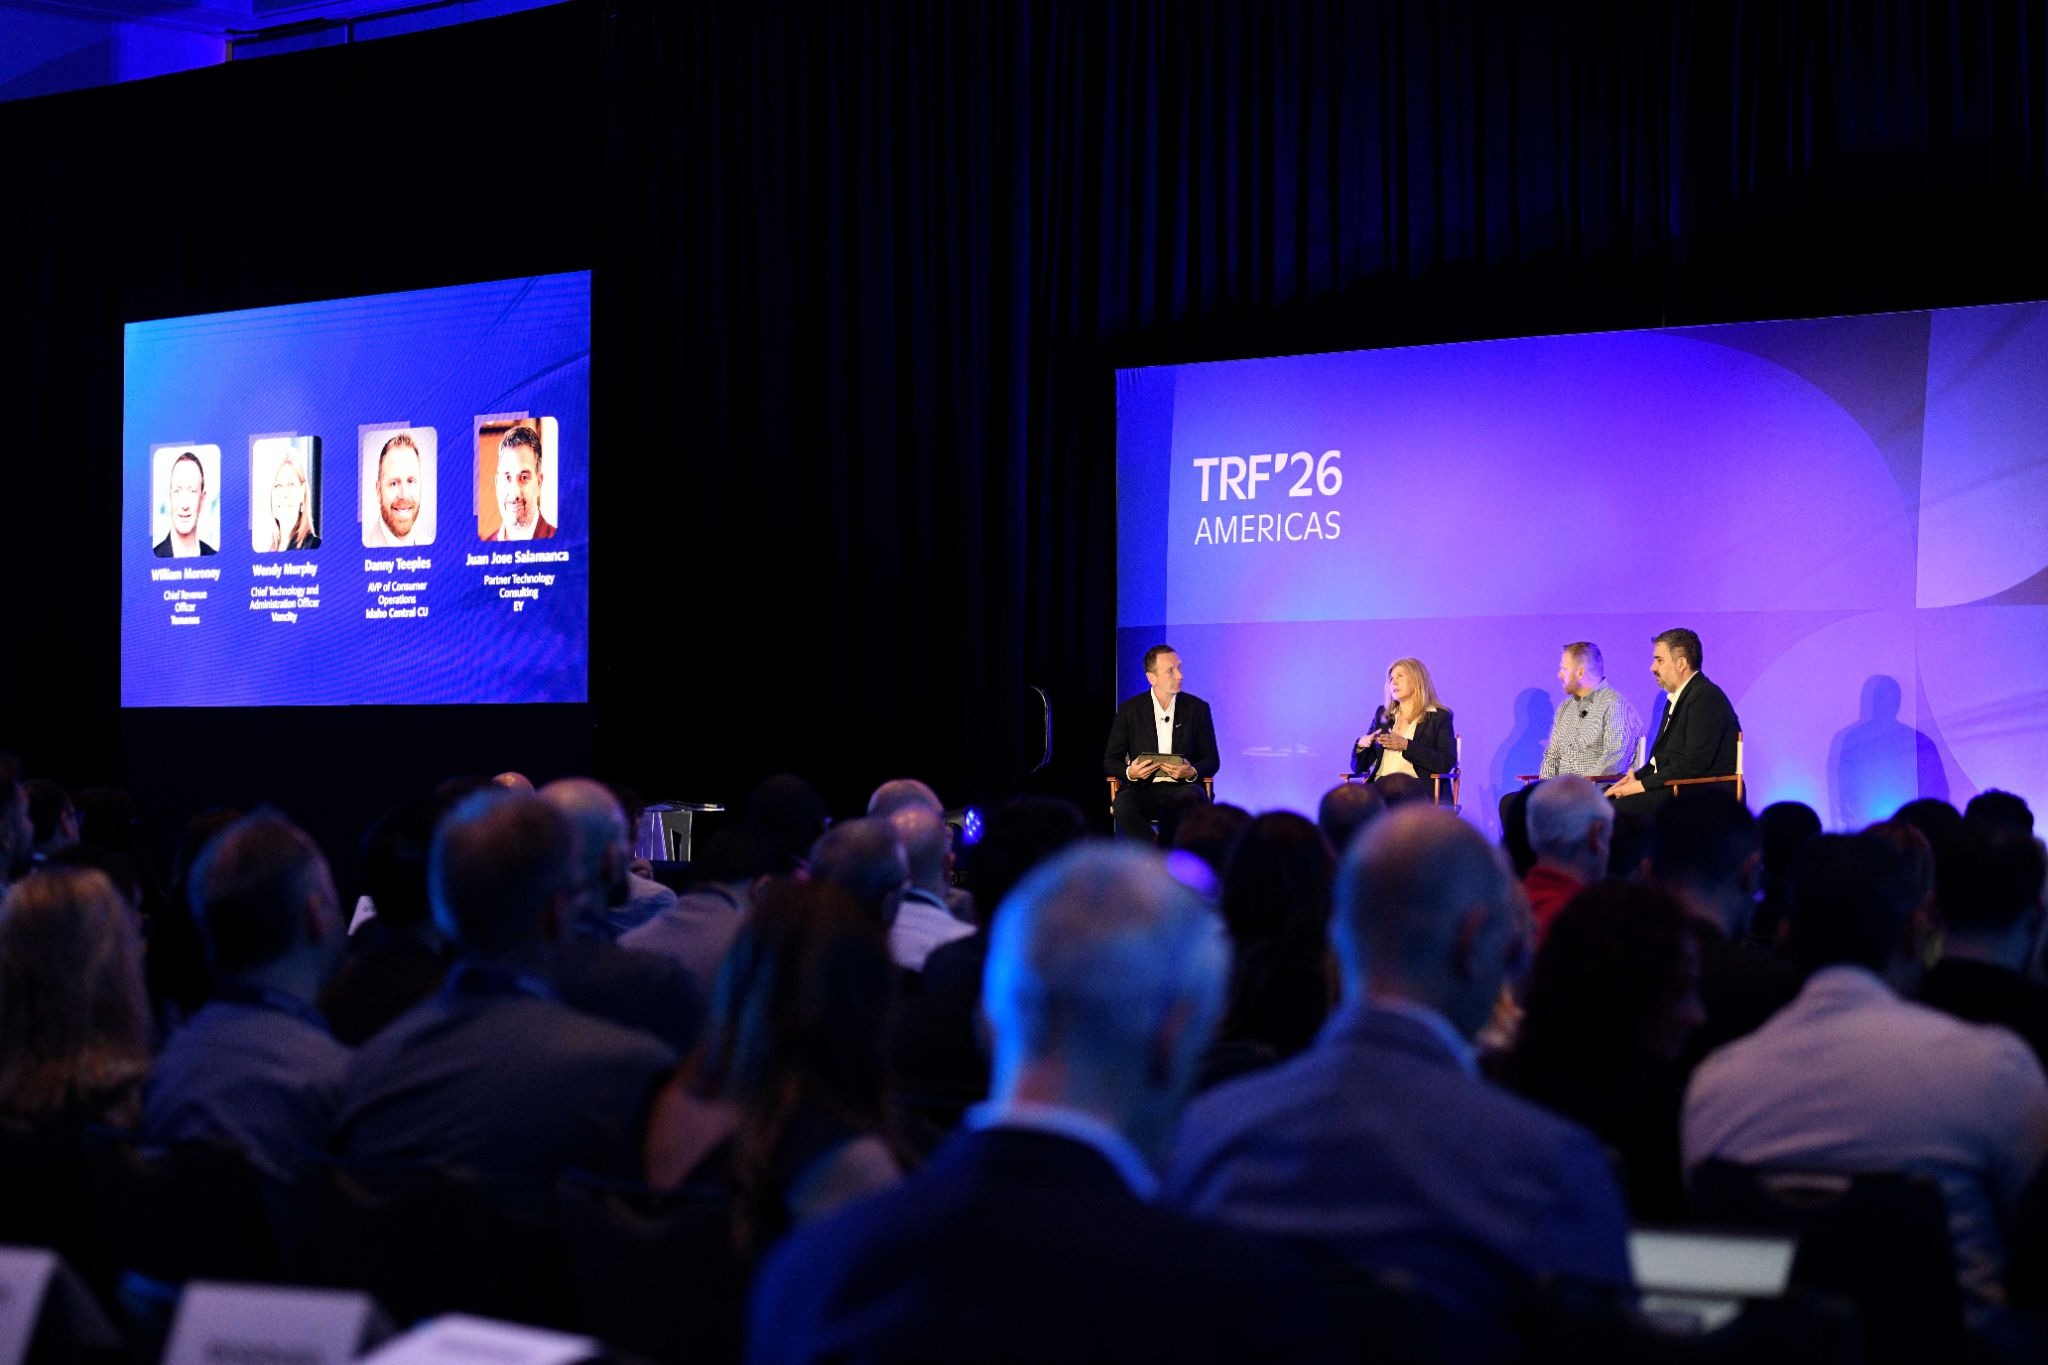
“Institutions are no longer debating whether to modernize,” said Brian DuVal, President of Temenos. “They’re focused on how to do it in a way that accelerates growth, improves customer experiences, and preserves trust.”
Temenos’ recent deals show how quickly the firm’s gaining momentum. A leading US regional bank chose Temenos SaaS to modernize its corporate banking, and Questrade, a top-rated Canadian online broker, launched its banking business on Temenos.
A path that fits the institution
Banks now want a modernization plan built around their own priorities, customers, and business model. They want speed and innovation, with less risk and disruption along the way. The systems behind payments, accounts, and access to funds can’t go down while the bank evolves.
Research Celent conducted for Temenos, released at the forum, shows 75% of US consumers said they are only moderately satisfied or less with their primary financial institution. Celent calls this group the “switchable middle.” Banks feel it too: 62% of US banks say winning and keeping customers has become harder over the past 12 months.
The gap goes beyond digital features. “It is about whether banks can keep pace with how customers want to manage their financial lives,” DuVal said.
AI moves into daily work
A year or two ago, bank conversations about AI centered on possibilities. Today they focus on specific applications: raising productivity, speeding up decisions, preventing fraud, and personalizing customer experiences. “The technology is moving from experimentation into everyday workflows,” DuVal said.
Customers increasingly expect banking to feel proactive and personalized, but bank budgets haven’t caught up. In the global edition of Celent’s research, just 4% of banks named personalization of the customer experience as their top investment priority. AI can’t fix this by itself, only capital and resources can. But AI can help accelerate deployment of modern personalization tools, closing the gap between customer expectations and banks’ ability to fulfil them.
Through a sharper spotlight on the broader technology ecosystem, Gen AI has moved up the agenda. Cloud, data, and AI now come up in board-level modernization discussions, which brings partners like AWS and Microsoft into the room. Banks want to know how the full environment helps them move faster, scale securely, and strengthen resilience.
Trust takes on a wider meaning
Trust in banking starts with the basics. “Payment transactions go through. Accounts are secure. Customers can access their money whenever they need it. The institution performs exactly as expected,” DuVal said.
Customers are grading banks on those basics. Celent’s global survey found 53% of consumers dissatisfied with their payment services and 39% dissatisfied with security and fraud protection. The research also found that trust weighs heavily on whether a customer stays or switches.
Reliability is a minimum. Customers increasingly trust institutions that understand them and anticipate their needs. Trust today sits where resilience, security, and relevance meet.
Business outcomes over broad strategy
The Temenos Innovation Hub in downtown Orlando houses product and technology teams focused on the US market, and gives visiting institutions a place to work hands-on with those teams.
Banks that came through the hub this year skipped the broad transformation talk and brought pointed questions. How do we launch faster? Reduce cost? Improve a customer journey? Increase resilience?
“Modernization is no longer a strategy discussion,” DuVal said. “It’s a business outcomes discussion.”
Regional banks, credit unions, challengers, and large banks each approach modernization differently. But they all share the challenge of balancing stability with innovation.
Where it goes next
The next phase will judge transformation by the value it delivers: faster time to market, lower costs, and stronger customer experiences. More institutions will need to prove they can modernize without giving up stability, and AI will become embedded in everyday operations.
“Success will be measured not by the technology banks adopt,” DuVal said, “but by the experiences they create and the outcomes they deliver.”