Goldman Sachs moves into predictable growth with Innovator acquisition

    The Wall Street incumbent embraces stability over volatility in asset management


    On December 1, Goldman Sachs revealed plans to acquire Innovator Capital Management, a provider of defined-outcome ETFs, bringing 159 defined-outcome ETFs and $28 billion in assets under management into its portfolio. This move underscores where the incumbent bank now prioritizes growth.

    [Defined-outcome ETFs, also called “buffered” ETFs, are exchange-traded funds designed to deliver a specific, pre-set investment result over a defined period. They use options and derivatives to offer upside potential while limiting downside losses.]

    This is a structural pivot. Innovator gives Goldman scale in one of the fastest-growing corners of public markets and nudges the firm a little further out from the revenue volatility that has long defined its dominance. The deal is expected to close in the second quarter of 2026.

    Why Innovator, and why now


    subscription wall for TS Pro

    What’s Left in the Shadows: How 90-year-old Webster Bank punches above its weight by combining purpose with profitability

      A storied beginning and a forward-looking purpose


      In 1935, with $25,000 borrowed from friends and family, Harold Webster Smith founded the First Federal Savings and Loan Association of Waterbury, Connecticut, to help people build homes during the Great Depression. His vision was that banking should serve the people around you, not just the bottom line.

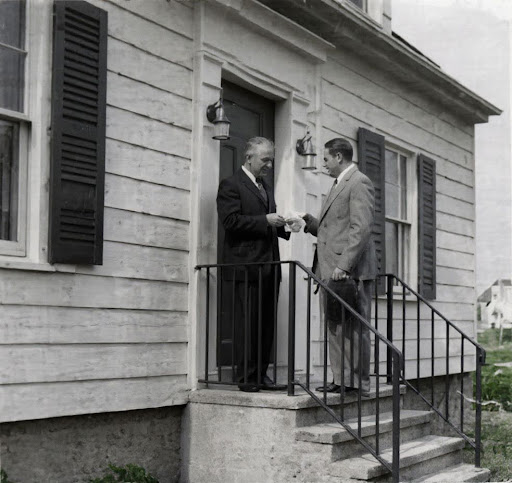
      Webster Bank founder Harold Webster Smith (right) makes the bank’s first loan to Joe Baltrush in December 1935 on the steps of his Waterbury home at 114 Chambers Street. Source: Webster Bank

      The organization was later renamed Webster Bank when it went public in 2002 and converted to a national commercial bank in 2004, enabling broader service offerings while largely preserving its regional identity. 

      Today, Stamford, Connecticut, serves as its headquarters, but its branches extend from suburban New York to Rhode Island and Massachusetts, giving it a solid regional footprint.

      Webster Bank (NYSE: WBS) remains true to its ethos: serving communities across the Northeast while moving billions of dollars of healthcare payments and powering fintech platforms behind the scenes. 

      Webster Bank’s evolution from a local thrift to a publicly traded commercial institution reflects a long-term focus. The bank serves clients across three key areas: commercial banking, consumer banking, and healthcare financial services.

      In today’s 10Q edition: What’s Left in the Shadows, we shine a light on the less-talked-about publicly traded names in the industry that do their own thing but remain integral to the banking ecosystem.


      subscription wall for TS Pro

      Klarna’s American drive and SoFi’s crypto comeback

        Klarna and SoFi: Betting big on credit and crypto


        If fintech competition were a boxing ring, Klarna and SoFi are trading very different kinds of punches, but both are very much in the fight for meaningful scale.

        Case Study 1: Klarna — Stretching the BNPL muscle in the US

        Recent move: Klarna struck a deal with Elliott Investment Management to sell up to $6.5 billion in US “Fair Financing” loans over the next two years. These are not short-term, no-interest BNPL loans — they’re fixed-term installment loans, with Klarna retaining underwriting and servicing duties.

        Why it matters:

        • Capital efficiency — By selling receivables under a forward-flow agreement, Klarna frees up balance sheet capacity to issue more loans. 
        • Scalable risk management — Rather than raising debt or equity, this structure allows Klarna to grow its credit book without taking on too much risk upfront.
        • US-centric growth — Fair Financing is growing faster in the US than globally (Klarna disclosed GMV up 244% in the US, vs. 139% globally over the past year). 


        subscription wall for TS Pro

        The fintechs that refuse to stand still

          The trajectories of Robinhood, Upstart, and LendingClub highlight the broader fintech trends heading into 2026


          The latest round of earnings from Robinhood, Upstart, and LendingClub reads less like a scoreboard and more like a temperature check on what fintech even means now. Each firm, in its own way, is evolving past the product it was born with – the trading app, the AI-driven lender, the online credit marketplace – and chasing something harder: resilience.

          But how they’re getting there couldn’t look more different.

          Robinhood: From trades to everything

          Robinhood’s early years were about giving retail traders a seat at the table, but its recent quarters have been about building a whole new table.


          subscription wall for TS Pro

          The Loyalty Flywheel: How Truist is turning its new business card into a relationship engine

            Why Truist’s new business card isn’t really only about the card


            As competition for SMB loyalty intensifies, financial institutions are rethinking where the first touchpoint begins. Increasingly, that entry point isn’t a checking account or a loan – it’s a card.

            Truist’s recent launch of its Business Premium Visa Infinite card fits squarely into that evolution. The super-regional bank is using the card as a relationship anchor: a gateway into an ecosystem of payments, working capital, and treasury solutions built around how small businesses operate.

            Chris Ward, Head of Enterprise Payments at Truist

            “It’s not just a credit product — it’s a relationship anchor,” says Chris Ward, Head of Enterprise Payments at Truist. That framing reflects a broader shift in banking strategy: away from transactional products and toward integrated, ecosystem-driven relationships where a card becomes both a data engine and a loyalty bridge.


            subscription wall for TS Pro

            Steering $10 Trillion Daily: JPM Payments’ Global Head of Technology on payments, AI, and leadership

              Inside the mind of a Payments Technologist Leader

              Payments is an industry that rarely stands still, and Sri Shivananda has spent enough time in its trenches to know how fast the ground can shift. Now Global Head of Payments Technology at J.P. Morgan Payments, his reflections on leadership and innovation cut through the usual hype.

              Shivananda’s career – from PayPal and eBay to one of the world’s largest banks – gives him a long view of how payments and its underlying tech have evolved. What he’s watching closely today: how real-time payments are setting new expectations, how AI is starting to reconfigure workflows, and why building inclusive teams matters if any of that is going to work at scale.

              Here’s my full conversation with him on what it takes to build in a rapidly evolving landscape.

              Sri Shivananda, Head of Technology at J.P. Morgan Payments


              subscription wall for TS Pro