The Week in Market Moves | July 2-9, 2026


Company signals and market response

This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

Subscribe to PRO and get the full 10-Q story every Friday!


1. Coinbase (COIN) – Close: $158.44

  • Coinbase secured U.K. regulatory approval to offer equities, derivatives, and perpetual futures alongside crypto products.
  • The move advances Coinbase’s ambition to become an “Everything Exchange,” combining traditional and digital asset investing under one platform.

Why it matters: Coinbase is steadily erasing the line between crypto exchanges and traditional brokerages. Rather than waiting for tokenized finance to fully emerge, the company is building a platform where conventional assets and blockchain-based products co-exist. The U.K. license gives Coinbase a regulated pathway to expand well beyond crypto, reinforcing a broader industry trend: the future competition may not be between banks and crypto firms, but between platforms that can offer every asset class through a single customer relationship.

2. U.S. Bank (USB) – Close: $61.90

  • U.S. Bank launched Enhanced Payments, giving small businesses a single digital interface to send same-day ACH, instant payments, and international wires without visiting a branch.
  • The bank has added higher transaction limits and payment guidance tools to help growing businesses choose the right payment rail for each transaction.

Why it matters: U.S. Bank is acknowledging that small businesses increasingly manage the same cross-border suppliers, cash flow complexity, and payment choices that were once reserved for larger enterprises. Rather than asking businesses to adopt another standalone payments platform, the bank is embedding sophisticated money movement directly into digital banking. The competitive battle is shifting from offering more payment rails to making those rails easier to navigate.

3. J.P. Morgan Chase (JPM) – Close: $335.47

  • JPM launched a dedicated Small-Cap Investment Banking business targeting companies valued between $100 million and $500 million.
  • It positioned the new team to work alongside commercial banking, private banking, and financing groups, extending J.P. Morgan’s existing relationships with growing businesses.

Why it matters: J.P. Morgan is moving further down the corporate ladder without changing its investment banking playbook. Many smaller businesses are approaching ownership transitions, attracting private equity interest or preparing for acquisitions, creating a growing pipeline of advisory work. By serving these companies earlier, J.P. Morgan increases its chances of keeping clients as they scale instead of losing them to boutique advisory firms. The strategy is as much about relationship expansion as it is about deal volume.

4. Block (XYZ) – Close: $77.42

  • Block agreed to pay $45 million to settle a multistate investigation into Cash App’s fraud protection and customer support practices.
  • The settlement requires stronger fraud controls, 24/7 live phone support, improved customer education, and compliance with reimbursement obligations for unauthorized transactions.

Why it matters: The financial penalty is significant, but the operational changes may matter even more. Regulators are making it clear that fintechs offering bank-like experiences are expected to deliver bank-like protections. As digital wallets become primary financial accounts for millions of consumers, fraud resolution and customer support are becoming competitive necessities rather than compliance checkboxes. The era of prioritizing growth over operational resilience continues to narrow.

5. Robinhood (HOOD) – Close: $115.11

  • Robinhood Chain’s earliest surge in activity came from memecoin trading, despite being designed primarily for tokenized real-world assets.
  • The rollout reinforces how retail speculation often becomes the first stress test for new blockchain infrastructure.

Why it matters: The story isn’t really about memecoins. It’s about how new financial infrastructure gains traction. Retail traders consistently become the first users willing to experiment with unfamiliar platforms, creating cash flow long before institutional use cases arrive. For Robinhood, the challenge now is whether infrastructure initially fueled by speculation can mature into a platform capable of supporting tokenized equities and broader financial products. The infrastructure – not the memes – will ultimately determine whether that transition succeeds.
What Robinhood’s June product blitz was really about


    Weekly 10-Q

    The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

    Message Sara


    What Robinhood’s June product blitz was really about

    The business Robinhood is becoming…


    Robinhood’s story has usually been told through the lens of trading. Every new product ultimately points back to one destination: getting people to buy and sell securities.

    June looked different, though. Within a matter of weeks, Robinhood became an IPO underwriter. It laid off roughly 10% of its workforce to accelerate product development. Days later, it unveiled Robinhood Chain, a blockchain purpose-built for tokenized real-world assets, alongside stock tokens, crypto lending, AI-powered trading accounts, and a broader international expansion.

    This string of announcements points to Robinhood systematically removing the boundaries between investing, banking, payments, capital formation, and blockchain infrastructure. The company is building a platform designed to own more of a customer’s financial life beyond just the moments when they trade.

    That evolution has been underway for years. Robinhood has steadily expanded beyond commission-free investing into retirement accounts, high-yield savings, credit products, wealth management, prediction markets, and family investing. Lending marked one phase of that transition. June’s announcements marked another milestone: building the infrastructure that connects those products into a unified financial ecosystem.

    Moving upstream in financial markets

    …


    subscription wall for TS Pro

    The Week in Market Moves | June 18-25, 2026


    Company signals and market response

    This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

    It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

    Subscribe to PRO and get the full 10-Q story every Friday!


    1. Green Dot (GDOT) – Close: $13.40

    • Green Dot shareholders approved the sale of Green Dot Bank, paving the way to split its regulated banking and fintech businesses.
    • The deal creates two focused companies: a publicly traded bank under CommerceOne and a privately owned fintech backed by Smith Ventures.

    Why it matters: The move reflects a growing belief that regulated banking and technology businesses no longer thrive under the same operating model. Banks are increasingly optimized for compliance, capital, and risk management, while fintechs compete on speed, software, and product innovation. Green Dot is acknowledging that each business may perform better when allowed to specialize rather than compromise.

    2. American Express (AXP) – Close: $342.46

    • American Express, Mercantile, and the American Bar Association launched a business credit card built specifically for solo lawyers and small law firms.
    • The partnership expands Amex’s push into profession-specific financial products instead of broad SMB offerings.

    Why it matters: Small businesses are becoming too diverse to serve with one-size-fits-all financial products. Rather than targeting SMBs as a single market, issuers are beginning to build around the economics of individual professions. Law firms have distinct cash-flow cycles, operating expenses, and financing needs, making verticalized financial products a more compelling competitive strategy than generic business cards.

    3. J.P. Morgan Chase (JPM) – Close: $335.12

    • J.P. Morgan promoted Doug Petno and Troy Rohrbaugh to co-presidents in its clearest succession move yet beneath CEO Jamie Dimon.
    • The appointments also place each executive in charge of one of the bank’s two largest operating divisions. Petno will become the CEO of the Commercial & Investment Bank (CIB), with Rohrbaugh taking the helm of the Consumer & Community Banking (CCB) business.

    Why it matters: Leadership succession has become a strategic asset for the world’s largest financial institutions. Rather than waiting for a CEO transition, J.P. Morgan is giving potential successors broader operational responsibility years in advance. It signals that institutional continuity is becoming part of a bank’s competitive advantage, particularly as scale makes leadership decisions increasingly consequential.

    4. Alphabet (Goog) – Close: $342.19

    • Google Finance introduced AI-powered portfolio management, investment research, and a dedicated Android app.
    • Users can now upload holdings, ask natural-language investment questions, and receive AI-generated market updates.

    Why it matters: Google is moving AI beyond answering financial questions into continuously monitoring a user’s portfolio. That shifts AI from an information layer to an ongoing financial companion that helps interpret markets, identify risks, and surface opportunities. As these tools become habitual, the interface where consumers check markets could increasingly become the place where financial decisions begin.

    5. NVIDIA (NVDA) – Close: $195.74

    • NVIDIA introduced an AI fraud detection blueprint that uses graph neural networks to uncover relationships between transactions, accounts, devices, and identities instead of evaluating payments in isolation.
    • The system is designed to detect coordinated fraud rings in real time, giving banks the ability to identify organized attacks before payments clear.

    Why it matters: The biggest shift in fraud is that banks are beginning to detect criminal networks rather than individual fraudulent transactions. As fraud grows more organized, transaction-by-transaction scoring leaves too many blind spots. Relationship-based AI changes the unit of analysis from the payment itself to the entire fraud ecosystem, enabling financial institutions to intervene earlier and make real-time fraud prevention more effective.

    PayPal is trimming the parts that don’t fit its new operating model


      Weekly 10-Q

      The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

      Message Sara


      PayPal is trimming the parts that don’t fit its new operating model

      PayPal is narrowing what counts as “core”.

      PayPal is weighing the shutdown of its venture arm, PayPal Ventures. Venture arms usually die for one reason: the parent company no longer believes it can afford ambiguity. And PayPal, right now, is choosing clarity over optionality.

      A company spokesperson said: “As part of our continued efforts to sharpen our focus, we are exploring strategic options for our corporate venture capital arm, PayPal Ventures.”

      “Exploring strategic options” is corporate language for something that is already structurally decided but not yet procedurally executed. According to multiple sources cited in reporting, the internal direction is more definitive than the phrasing suggests: shutdown or partial wind-down, with some positions potentially sold on the secondary market.

      Which brings us to the actual question: Why?

      Because PayPal is shrinking its perimeter of what counts as “core”

      To understand why a venture arm becomes expendable, we have to look at what the company is trying to become.

      …


      subscription wall for TS Pro

      Recognizing Excellence: The 2026 Tearsheet Bankchain Awards Winners

      As blockchain moves from the margins of finance toward the core of banking infrastructure, a mix of established and emerging institutions is shaping its development and deployment.

      Tearsheet’s Bankchain Awards recognize the banks, fintechs, and technology providers advancing the adoption of digital assets, tokenization, stablecoins, and distributed ledger technology across financial services.

      This year’s winners stand out for moving beyond experimentation and delivering real-world impact. Here are the organizations shaping the next chapter of banking and digital finance.

      2026 Winners of the Bankchain Awards


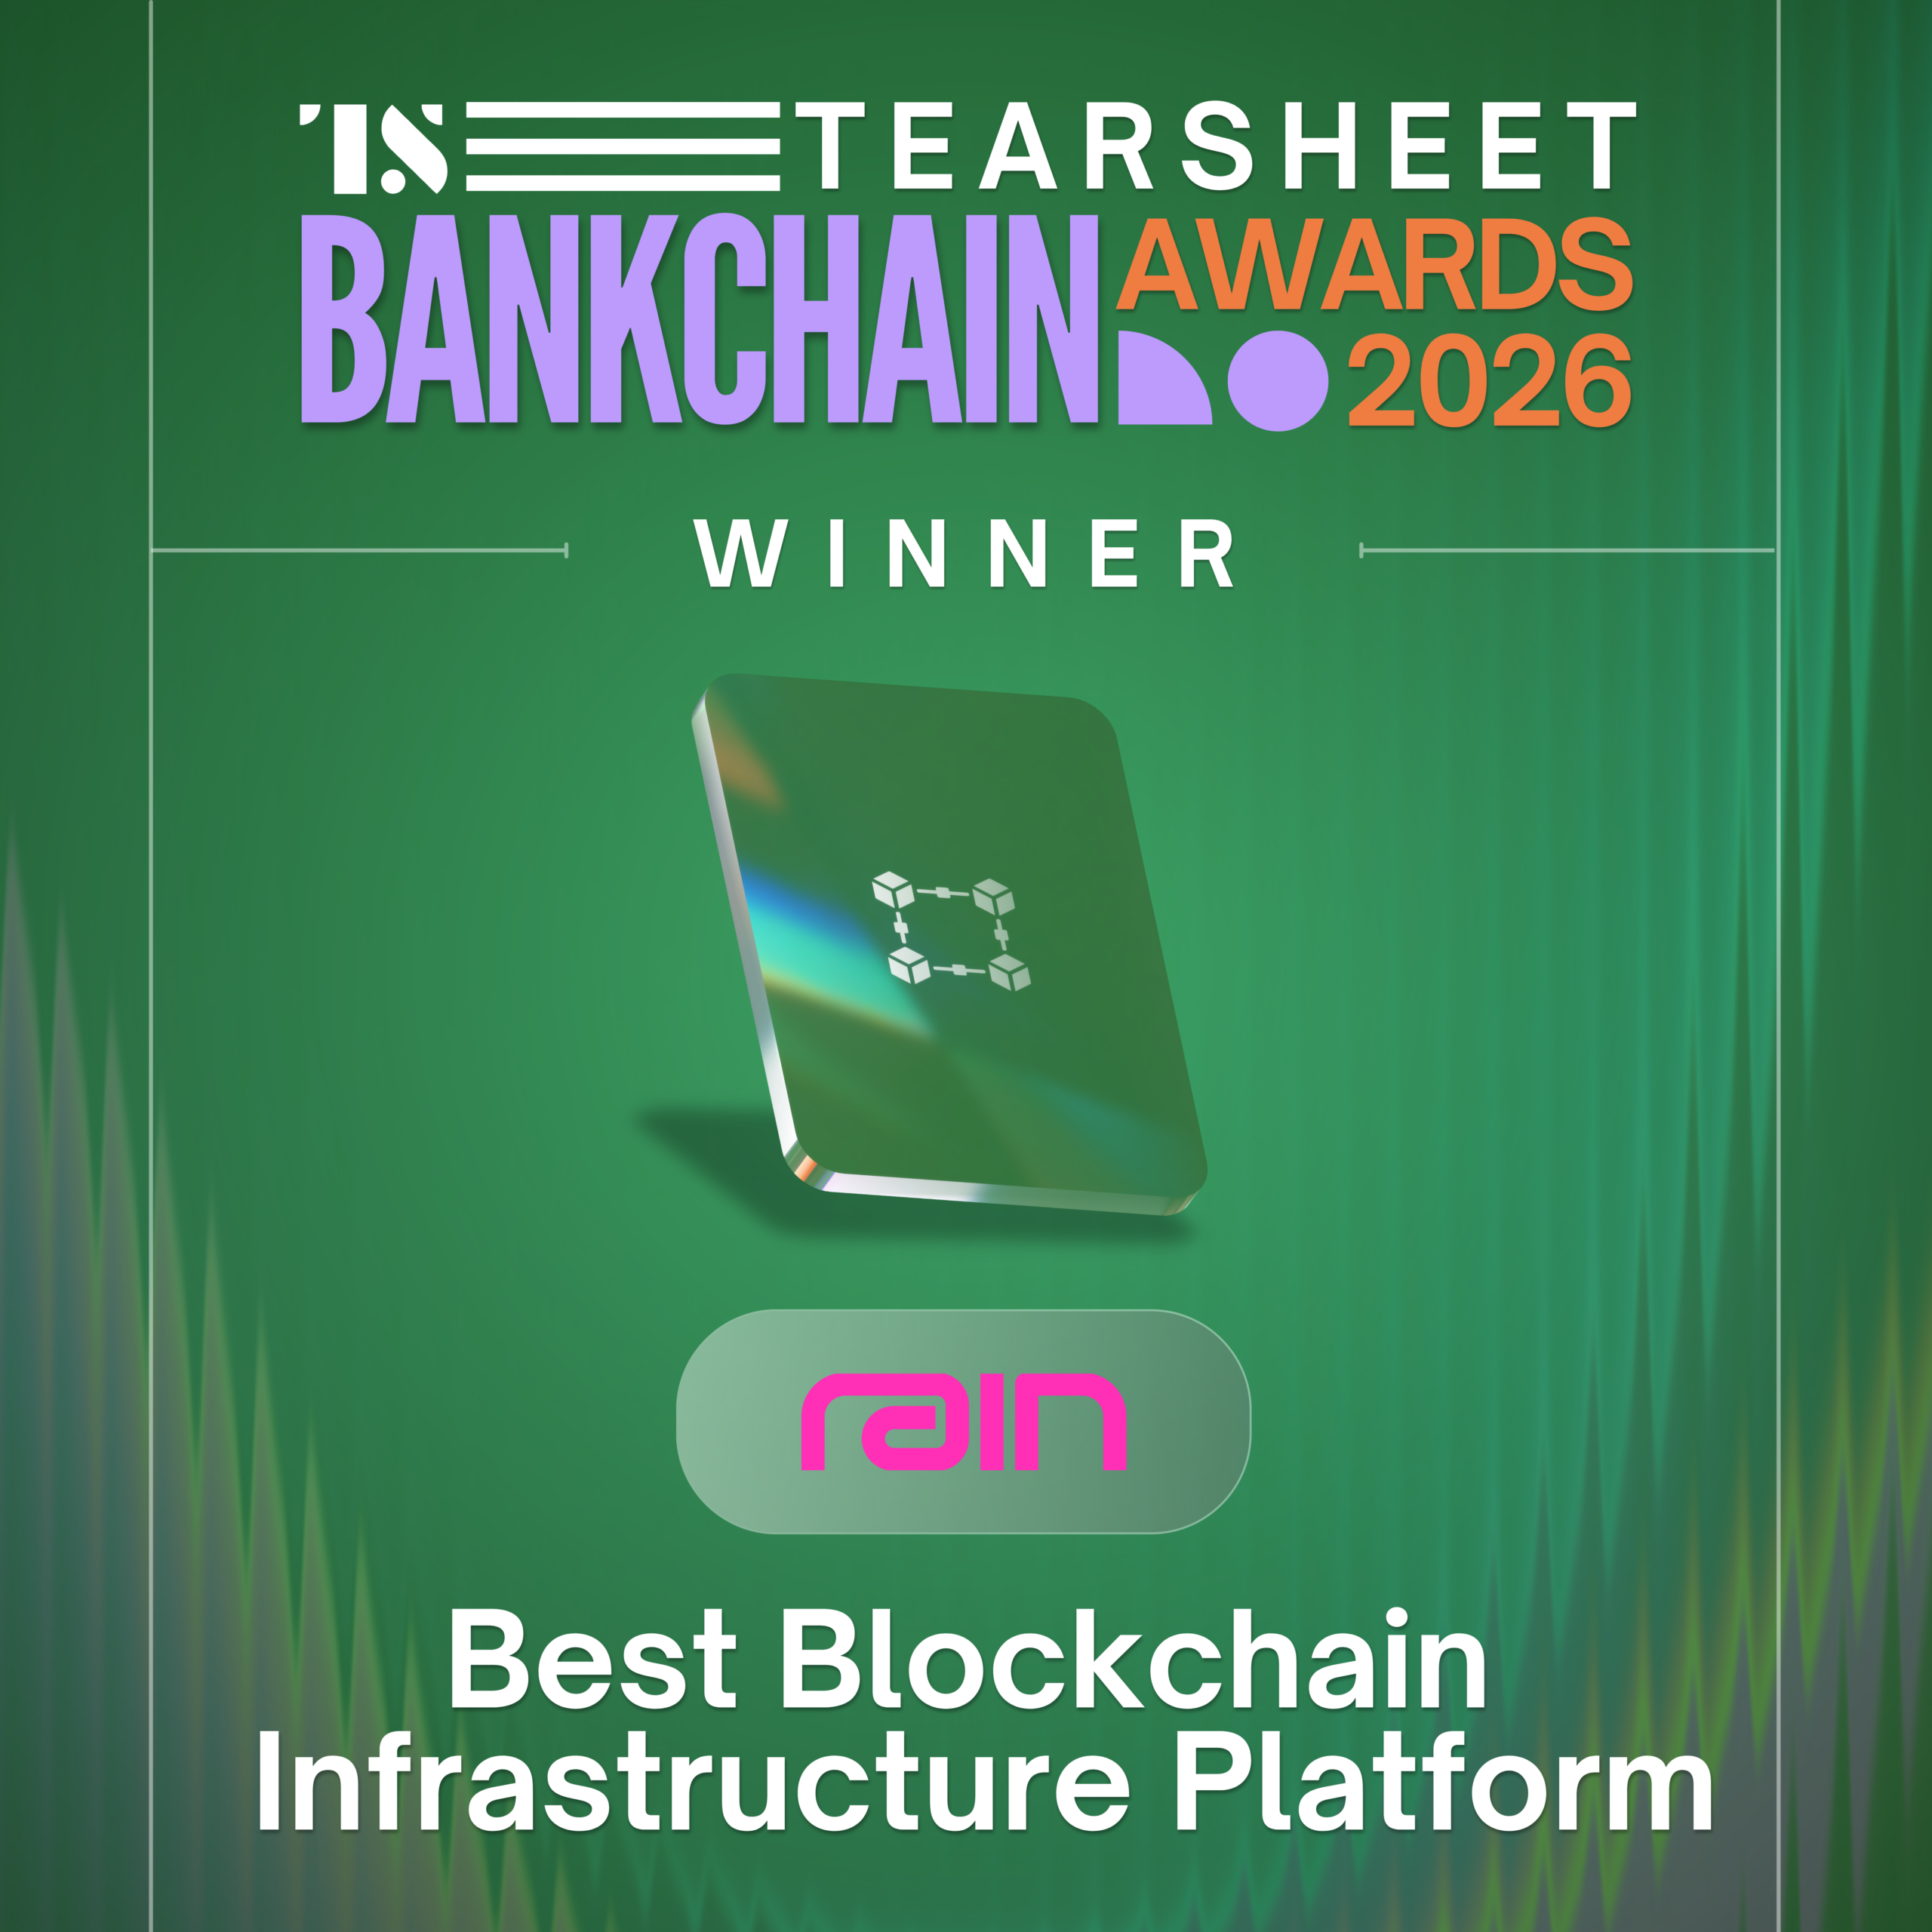
      Best Blockchain Infrastructure Platform: Rain

      Rain earns the Best Blockchain Infrastructure Platform Award for building the connective layer between tokenized money and everyday commerce. Its onchain-native card issuance and settlement infrastructure allows businesses and consumers to spend tokenized funds through existing card networks at more than 150 million merchants worldwide, without interacting directly with blockchain complexity. As a Visa Principal Member, Rain has pioneered onchain settlement that operates seven days a week while reducing the capital requirements traditionally tied to card programs. The platform already supports millions of transactions across more than 150 countries and serves customers including Western Union and Nuvei. By making tokenized money usable within familiar payment experiences, Rain is helping translate blockchain innovation into practical financial infrastructure.

      Innovation: Kinexys by J.P. Morgan

      Kinexys by J.P. Morgan wins the Innovation Award for introducing JPM Coin, the first bank-issued deposit token to operate on public blockchain infrastructure. Designed for institutional clients, JPM Coin brings regulated commercial bank money on-chain, enabling near-instant, 24/7 settlement while remaining integrated with traditional banking systems. The launch builds on more than a decade of blockchain development at J.P. Morgan, whose Kinexys platform has processed over $4 trillion in transactions since its inception. By creating a new category of digital commercial bank money and addressing the gap between traditional deposits and onchain liquidity, Kinexys is helping define how institutions will move capital in a blockchain-enabled financial system.

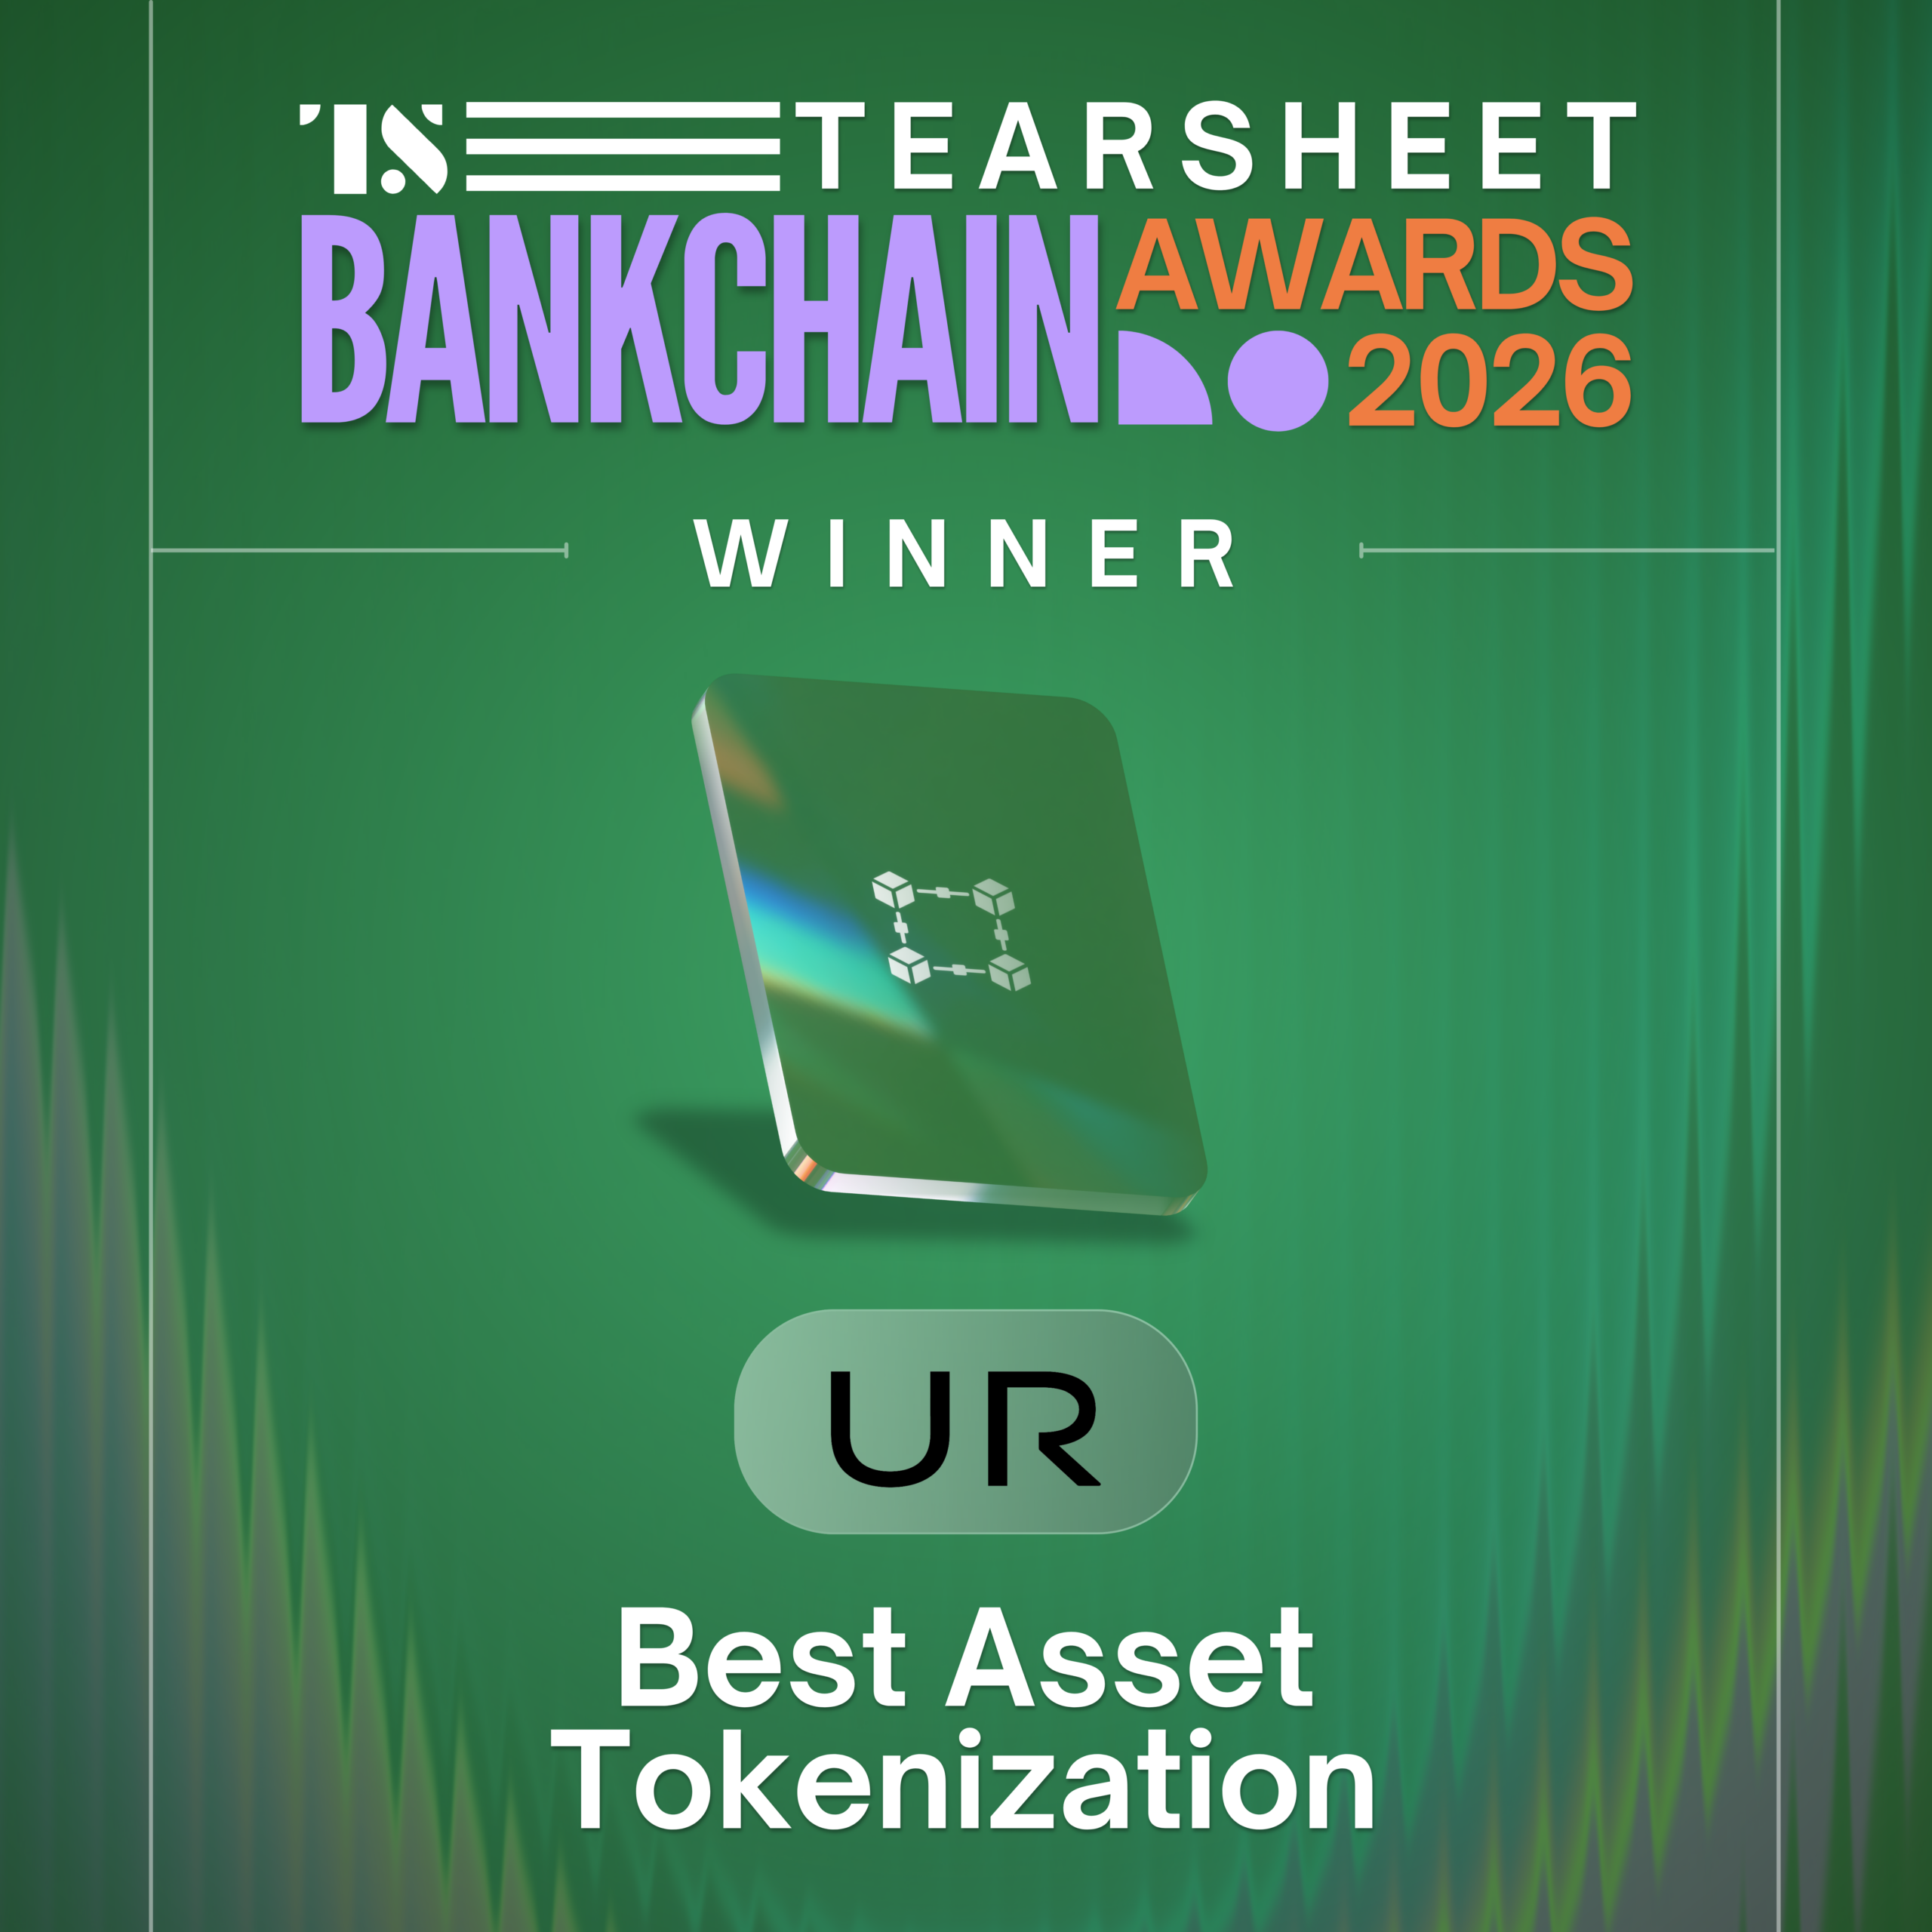
      Best Asset Tokenization: UR Technology

      UR Technology receives the Best Asset Tokenization Award for its role in building the technical infrastructure that allows users to have access to tokenized deposits, which serve as a practical bridge between onchain finance and everyday financial activity. UR’s value lies in empowering an open economy, drawing connections between blockchain technology and traditional finance for everyone globally. It operates as a technology integration layer, connecting third‑party financial service providers with blockchain and traditional payment rails. Through these back‑to‑back integrations, the tokenized representation of seven major fiat currencies, each backed 1:1 by client top-up held in regulated Swiss IBAN accounts, can be used by users to seamlessly move cross-border, foreign exchange, and spend-using cards for everyday use. This model has gained meaningful traction, with the underlying ecosystem processing over $1.2 billion in volume and more than 5 million Mastercard transactions across 240,000 verified users in more than 50 countries. By integrating regulated financial products with global payment capabilities, UR expands the practical utility of digital assets in everyday finance.

      Best Stablecoin Offering: PYUSD PayPal

      PayPal stands out as the recipient of the Best Stablecoin Offering Award, a complementary recognition for PYUSD, which combines regulated 1:1 dollar backing, strong compliance standards, and expanding real-world utility across payments, settlement, and cross-border flows. Now available across 70 markets, PYUSD can be bought, held, sent, and converted within PayPal, moved across Venmo, external wallets, and multiple blockchains, and used for payments at PayPal checkout, where merchants gain faster access to funds. Its growing role in Xoom-enabled cross-border transfers is helping reduce settlement friction and dependence on traditional banking hours, while early integrations with payout partners in regions such as Africa and Asia-Pacific extend its reach into real-world remittance corridors. With optional rewards for holding, improving liquidity, and increasing use across consumer, merchant, and settlement flows, PYUSD is steadily positioning itself as a compliant, interoperable dollar-native stable value layer embedded within everyday global commerce.

      Best Custodian: Anchorage Digital

      Anchorage Digital is selected for the Best Custodian Award as a complimentary recognition for defining institutional-grade digital asset custody through federally chartered, security-first infrastructure that unifies crypto and fiat within a single regulated platform. As the first OCC-chartered crypto-native bank, it combines qualified custody, segregated key management, biometric and quorum-based approvals, insurance protection, and SOC-certified auditability to ensure both control and compliance at scale, while enabling fast, API-driven settlement and transparent reporting for institutional workflows. Beyond custody, Anchorage has expanded into a broader regulated financial layer — integrating fiat banking, global wires, staking, trading, and settlement — while advancing high-profile initiatives such as partnerships with BNY, Google Cloud, and Western Union’s USDPT issuance, positioning it as a core infrastructure provider bridging traditional finance and onchain markets.

      Best Crypto Payments Infrastructure: WalletConnect Pay

      WalletConnect Pay is named the Best Crypto Payments Infrastructure Award as a complimentary recognition for bringing stablecoin payments into physical retail at scale through a wallet-native checkout layer. Integrated with Ingenico’s global POS network, it enables customers to pay in stablecoins directly from their existing mobile wallets while merchants receive settlement through their usual payment providers without new hardware, card networks, or workflow changes. By embedding compliance, identity, and transaction logic into the wallet experience, it removes blockchain complexity at the point of sale and makes crypto acceptance feel identical to traditional card payments. With expanding POS integrations and support for networks like Solana, WalletConnect Pay is positioning stablecoin payments as an embedded, behind-the-scenes layer of everyday commerce infrastructure.

      What Klarna, Coinbase, and Chase are building next


        Weekly 10-Q

        The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

        Message Sara


        What Klarna, Coinbase, and Chase are building next

        Klarna, Coinbase, and Chase and the business of moving closer to the customer.


        This week saw Klarna move deeper into deposits, Coinbase using stablecoins to re-engineer credit access, and Chase building intelligence layers around small business decision-making. 

        These moves offer a snapshot of how financial firms are searching for growth beyond the boundaries that originally defined them.

        Klarna: Turning spending behavior into a deposit engine

        Klarna has launched a US high-yield savings account in its app. This is the next step in a longer shift of treating spending and saving as a single behavioral system.

        The accounts -– FDIC-insured through WebBank, with no minimums, no fees, and yields above 3% APY -– place Klarna directly inside the deposit economy. “The average American earns less than half a percent on their savings, not because better options don’t exist, but because their bank hasn’t had to compete,” said Sebastian Siemiatkowski, CEO and co-founder of Klarna.

        …


        subscription wall for TS Pro

        The Week in Market Moves | May 28-June 4, 2026


        Company signals and market response

        This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

        It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

        Subscribe to PRO and get the full 10-Q story every Friday!


        1. Wise (WSE) – Close: $11.05

        • Wise is under investigation in Belgium over suspected AML lapses tied to cross-border flows totaling roughly €500M.
        • The probe follows earlier regulatory pressure in Europe and past remediation efforts across its AML and compliance systems.

        Why it matters: This goes to the core of what scaled cross-border fintech looks like under regulatory stress. As transaction volumes grow and geographies expand, the AML surface area expands with it.

        For Wise, the issue is less about whether it has controls in place and more about whether those controls can keep pace with increasingly fragmented enforcement regimes across jurisdictions.

        It also underscores a broader reality for cross-border players: speed and scale are only as durable as the compliance architecture underneath them.

        2. SoFi (SOFI) – Close: $16.92

        • SoFi introduced an AI-powered financial coach that aggregates data across over 12,000 institutions to provide personalized guidance.
        • Early testing shows 70% of engaged users took financial actions such as debt repayment or account optimization.

        Why it matters: This move pushes SoFi beyond being a multi-product financial app into a decision-making layer across a user’s entire financial life. The key shift is scope.

        By pulling in external financial data, SoFi is effectively positioning itself as the interpretive layer over fragmented financial behavior. That creates a stronger feedback loop between insight, recommendation, and action than product bundling alone ever could.

        3. Affirm (AFRM) – Close: $68.57

        • Affirm and Stripe expanded their partnership to bring BNPL capabilities to UK merchants using Stripe.
        • The collaboration also includes joint work on AI-powered commerce and tokenized, pay-over-time checkout experiences.

        Why it matters: This move is about checkout becoming a programmable decision layer. Payments are becoming adaptive financial choices embedded in commerce flows.

        Stripe continues to position itself as the orchestration layer for merchant payments, while Affirm plugs into that layer at the point of consumer decision.

        4. LendingClub (LC) – Close: $17.28

        • LendingClub is shifting its listing to Nasdaq alongside a rebrand to “Happen Bank” as it evolves into a broader digital-first bank.
        • The company is repositioning beyond lending into deposits, marketplace finance, and a more diversified banking model.

        Why it matters: The rebrand reflects LendingClub’s structural identity shift from product company to full-stack financial institution.

        Moving to Nasdaq aligns with its repositioning toward a more tech-forward narrative, but the real change is architectural. LendingClub is effectively trying to escape its original constraint as a lender and reframe itself as a system for financial activity rather than a single product.

        5. Bank of America (BAC) – Close: $54.07

        • Bank of America is launching a real-time cross-border payments solution integrated with SWIFT and its CashPro platform.
        • The system connects multiple global instant payment networks, including UPI, Faster Payments, and SPEI.

        Why it matters: This is a traditional bank directly responding to the real-time expectations set by fintech and payment networks. The move is about compressing settlement latency across jurisdictions while maintaining institutional control.

        The key shift is interoperability, connecting fragmented domestic instant payment systems into a unified corporate experience layer.

        SoFi bets the future of finance is fewer handoffs


          Weekly 10-Q

          The weekly 10-Q newsletter is part of the Tearsheet Pro subscription, where I unpack the recent moves and strategies of leading banks and fintechs in the public space, coupled with stock market analysis. In your inbox every Friday!

          Message Sara


          SoFi bets the future of finance is fewer handoffs

          SoFi’s new playbook: Own the customer, own the infrastructure, own the money movement


          The last ten years saw financial services steadily unbundle. Specialists emerged for lending, investing, payments, banking infrastructure, financial planning, and compliance. As a result, consumers gained more choice, and financial institutions gained more vendors. But the result was also more fragmentation. Money moved through multiple systems, customer information was stored in multiple databases, and financial decisions were made without a complete picture.

          SoFi’s string of announcements between May and June suggests the company sees the next phase differently. In less than a month, it acquired assets from capital markets platform PrimaryBid, bought loan servicing software provider Peach Finance, expanded access to its stablecoin SoFiUSD, hired payments veteran Kathleen Pierce-Gilmore to lead its technology business, and launched an AI-powered financial coach.

          These developments point to the firm’s broader attempt to reduce the number of handoffs between financial products, systems, and decisions.

          From products to systems

          SoFi started as a consumer products company, scaling from student loans into banking, investing, and credit cards through its single integrated financial platform.

          …


          subscription wall for TS Pro

          How money movement is becoming one continuous system

          This month began with two key developments in crypto and payments: Binance listing stocks and ETFs on its trading platform, and MoneyGram introducing a new US dollar-backed stablecoin.

          Binance and the push to collapse financial silos

          Crypto trading platforms and stock brokerages were designed as separate systems. One focused on digital assets, the other on regulated securities, with users expected to move between them.

          Binance is now testing a different assumption: users no longer think in asset classes.

          On June 1, the company began rolling out access to more than 7,000 US stocks and ETFs directly within its app, extending a platform that was once almost entirely crypto-focused into traditional equities. The pitch is consolidation. “Today’s users don’t think in silos,” the firm said in its announcement.

          The move mirrors a broader industry shift. Coinbase has also been building toward an “everything exchange” model, while infrastructure players and regulators are slowly opening the door to testing tokenized versions of traditional securities.

          Binance is going a step further with “bStocks,” planned tokenized representations of equities that would allow users to move between traditional shares and on-chain assets. The idea is to bring financial systems closer together.

          Regulators are still working through the framework. The U.S. Securities and Exchange Commission is evaluating tokenized securities structures, while institutions such as the Depository Trust & Clearing Corporation, which custodies over $114 trillion in assets, are preparing early-stage tokenization pilots for real-world assets later this year.

          What emerges from all of this is a structural question: if assets can move freely between crypto rails and traditional markets, does the distinction between the two still hold?

          Binance is of the view that for most users, it already doesn’t.

          MoneyGram and the shift from transfers to programmable dollars

          Sending money across borders has been defined by trade-offs: cost, speed, and access have rarely improved at the same time. Even as digital tools have reduced some friction and improved the experience at the margins, the underlying model of intermediaries and conversion layers has remained largely unchanged.

          MoneyGram is now attempting to reshape that foundation. With the launch of MGUSD, its new dollar-backed stablecoin, the company is moving beyond payments into what it describes as a “stable, dollar-denominated balance” that can be held, moved, and converted globally. The aim is to serve individuals in economies where currency instability, inflation pressure, or limited banking reach make financial predictability difficult.

          The structure behind MGUSD is intentionally layered. Bridge handles issuance, M0 provides smart contract infrastructure, Stellar supports blockchain settlement, and Fireblocks enables custody and transfer within MoneyGram’s existing distribution network. It is a coordinated stack built around distribution.

          Instead of starting with assets and searching for use cases, MoneyGram is starting with its global remittance network and layering stablecoin functionality into it.

          That approach comes at a time when institutional confidence in digital assets is still uneven. Research continues to show that most finance leaders hesitate due to regulatory ambiguity and concerns around control, even as interest in stablecoins grows for payments use cases.

          The hesitation stems from how these systems will behave when they move from experimentation to core financial infrastructure.

          MoneyGram believes that embedding stablecoins within a regulated, widely used distribution network removes that uncertainty, turning what is still seen as crypto infrastructure into underlying financial infrastructure.

          The Week in Market Moves | May 21-28, 2026


          Company signals and market response

          This analysis tracks the top company developments and how markets absorbed them through Thursday’s close, focusing on where shifting narratives translate into price action.

          It is part of Tearsheet PRO’s weekly 10-Q Newsletter, where strategy meets market reaction. I track how leading banks and fintechs are evolving in public markets and how investors are pricing those moves.

          Subscribe to PRO and get the full 10-Q story every Friday!


          1. Mastercard (MA) – Close: $493.75

          • Mastercard is asking Brazilian processors to share half the losses tied to Banco Master’s collapse and Will Financeira’s card portfolio exposure.
          • The dispute sits at the intersection of new central bank liability rules and legacy card-network risk allocation during issuer failure.

          Why it matters: Mastercard is testing how far network liability can extend when an issuer fails mid-transition in a tightening regulatory regime. Banco Master is a Brazilian bank that grew rapidly through high-yield debt funding and later faced cash flow stress, leading to its collapse and liquidation. The Banco Master collapse exposed ambiguity over who absorbs systemic fallout in card ecosystems.

          Brazil’s central bank has already shifted more responsibility onto payment networks for settlement guarantees, but Mastercard is pushing back on retroactive interpretation of those rules. The standoff signals a broader fault line: as regulators push for guaranteed settlement finality, networks are being forced to rethink how risk is distributed across issuers, acquirers, and schemes.

          If unresolved, this becomes less about one failed fintech and more about how payment networks price and structure systemic risk in emerging markets.

          2. Circle (CRCL) – Close: $108.24

          • Circle co-founder Sean Neville’s Catena Labs raised $30M and received OCC acceptance for a national trust bank charter application.
          • The company is building an “AI-native financial institution” designed for agent-driven transactions with embedded controls and policy layers.

          Why it matters: Circle co-founder Sean Neville is now rebuilding the financial stack around AI agents. His new venture, Catena Labs, is an AI-native financial infrastructure startup positioning agents as the primary actors in moving money, with humans acting as supervisors rather than initiators. This extends his earlier work in stablecoin-based payments into regulated banking rails designed for agent-driven finance.

          The key shift is architectural: agents get wallets, balances, and payment rails, while humans get a “control plane” to set constraints, approvals, and limits. That separation signals where the industry is heading, away from human-initiated transactions and toward delegated economic activity executed by software.

          If this model scales, the core battleground in financial services shifts from UX and apps to governance infrastructure: how much autonomy AI agents are allowed to have, and who controls the boundaries of that autonomy.

          3. Robinhood (HOOD) – Close: $84.84

          • Robinhood received Canadian regulatory approval for its acquisition of WonderFi, deepening its crypto infrastructure footprint.
          • The deal complements earlier acquisitions like Bitstamp as Robinhood expands custody, compliance, and trading infrastructure.

          Why it matters: Robinhood is rebuilding itself as a multi-layer financial platform spanning brokerage, crypto infrastructure, and emerging market-style financial products.

          Crypto trading revenue has fallen sharply, down roughly 47% year-over-year, but that decline is being offset by subscription products, prediction markets, and derivatives-linked activity. The WonderFi acquisition announced in 2024 extends this shift by adding regulated Canadian crypto rails, staking, and custody capabilities.

          The broader signal is structural repositioning: Robinhood is moving from a single-product brokerage dependent on trading volatility to a platform that combines investing, speculation, and infrastructure ownership. In that model, trading becomes one of several monetization layers inside a broader financial ecosystem.