Banking, Embedded Finance, Member Exclusive

The ‘discovery’ problem in embedded finance – and how OMB Bank found the right fintech partner

  • Despite rapid innovation and growth in embedded finance, one area remains largely unchanged: how banks and fintechs initially connect.
  • Treasury Prime identifies discovery – not diligence – as the real bottleneck in embedded finance, with AI now positioned to overcome it.
close

Email a Friend

The ‘discovery’ problem in embedded finance – and how OMB Bank found the right fintech partner

For Missouri-based community bank OMB Bank, finding the right fintech partner used to be a slow, manual process. Executive Vice President and Chief of Staff Jessica Sims recalls working from static PDFs of the bank’s preferences, followed by endless back-and-forth emails whenever a fintech expressed interest. The process worked, but painfully slowly, and promising opportunities often slipped through the cracks.

That changed when OMB discovered Backpack, a university payments fintech on Treasury Prime’s AI Marketplace, whose priorities perfectly aligned with the bank’s focus areas. OMB moved quickly, creating a smooth collaboration that benefited both parties.

The ‘discovery’ problem in embedded finance

Embedded finance is a three-way intersection: banks provide the regulated foundation, fintechs handle the tech and integrations, and non-financial brands deliver the end service to users.

Despite all the innovation and growth in the space, one part of the process has seen little advancement: how banks and fintechs find each other in the first place. Behind the scenes, most teams still spend weeks sorting inbound interest, chasing warm introductions, and manually assessing early-stage fit, with many discussions that go nowhere – long before compliance or economics even enter the conversation.

Finding fintech partners that truly align with a bank’s strategy, risk appetite, and operating model remains slow, manual, and opaque – the very problem OMB faced before meeting Backpack.

Treasury Prime believes that discovery, not diligence, is the real bottleneck in embedded finance equations – and that AI is now mature enough to fix it.

In December 2025, Treasury Prime launched its new AI Marketplace to change that starting point. The platform automates partner discovery and accelerates collaboration between banks and fintechs.

“Discovery is where banks feel the most friction,” says Chris Dean, co-founder and CEO of Treasury Prime. “The biggest change is that banks are no longer starting from a blank slate with every new fintech conversation.” 
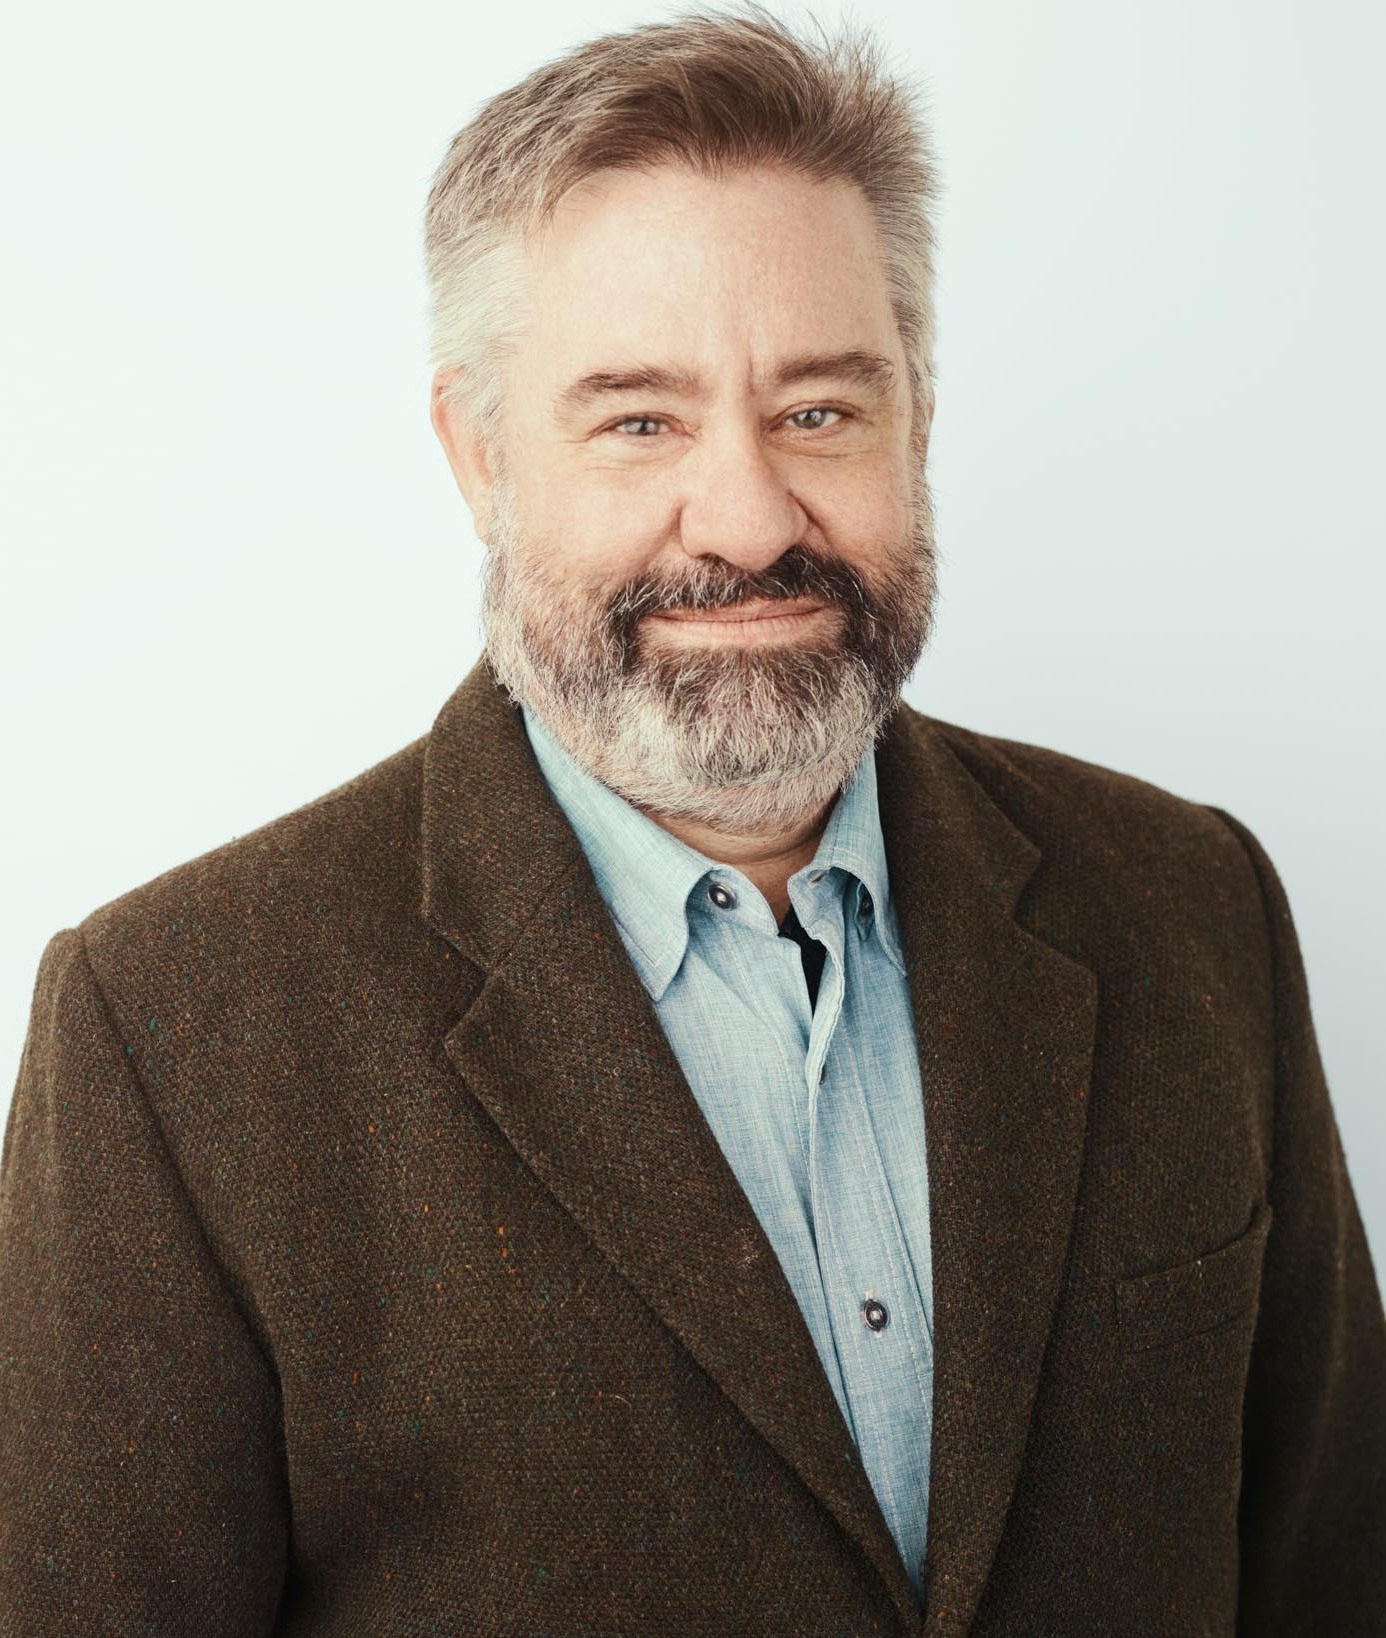
Chris Dean, co-founder and CEO of Treasury Prime


…


Tearsheet Pro

0 comments on “The ‘discovery’ problem in embedded finance – and how OMB Bank found the right fintech partner”

5 questions, Member Exclusive, Payments

How Gen Z’s expectations are pushing treasury toward real-time finance feat. Citizens

  • Gen Z is raising the bar for treasury, expecting payment visibility, transparency, and control to keep pace with real-time money movement.
  • Citizens is modernizing banking connectivity, but instant payments also demand earlier fraud checks and better information-sharing across banks, fintechs, and payment providers.
Sara Khairi | November 12, 2026
Business of Fintech, Member Exclusive

How Block is turning Square and Cash App into one local growth network

  • Block has connected Square’s seller network with Cash App’s consumer base via Neighborhoods, giving local businesses a way to turn discovery into direct orders, customer relationships, and potentially repeat visits.
  • Neighborhoods is designed to bypass the traditional marketplace model. Its growth will depend on whether Cash App can generate meaningful customer demand and repeat spending without adding another layer of cost for sellers.
Javarya Kamran | November 10, 2026
10-Q, Member Exclusive

Can Block turn an agentic voice layer into a merchant growth tool?

  • Block is betting voice AI could help Square become more valuable to merchants by improving the workflows that drive sales and service.
  • Turning this ambition into merchant value will depend on execution: accurate orders, useful recommendations, and measurable returns that justify the added cost.
Sara Khairi | November 09, 2026
Business of Fintech, Member Exclusive

Block has built the bridge between Square sellers and Cash App customers. Now it wants more people to cross it.

  • Block’s Neighborhoods connects Square sellers with Cash App users, helping local businesses drive discovery, direct orders, and repeat visits without monthly fees or marketplace commissions.
  • Early growth is promising, with $1 billion in annualized GPV as of June 2026, but the long-term test is whether Neighborhoods drives incremental spending and lasting customer relationships.
Sara Khairi | November 05, 2026
10-Q, Member Exclusive

Huntington wants to win small businesses before they become banking customers

  • Huntington is looking for its next small-business customers before they need a bank.
  • With 1866 Studio, it’s betting that helping entrepreneurs solve everyday business problems now could earn it a role in their financial decisions later.
Sara Khairi | November 02, 2026
More Articles