
Finance Everywhere, Lending

What will Walmart’s launch of BNPL through One mean for the industry?

  • Walmart is leveraging its fintech arm One to offer BNPL options to its customers, competing with existing players like Affirm, which already offers pay in four options in Walmart stores.
  • The entry of retail brands like Walmart into financial services could compel dedicated fintechs to offer more attractive financing options to maintain market share, while also allowing Walmart to deepen its customer relationships, particularly with younger consumers.
close

Email a Friend

What will Walmart’s launch of BNPL through One mean for the industry?

Walmart announced in April that it will be leveraging its majority-owned fintech One to offer BNPL options to its customers. This move is an addition to a growing list of retailers who are expanding into financial services like Apple and Amazon.

In 2022, Walmart’s One started offering some banking services to its own employees and some customers under the tutelage of new hires of Goldman Sachs’ Omer Ismail and David Stark. Before its launch of BNPL through One, Walmart partnered with Affirm to offer pay in four options to its customers. But now BNPL offerings by both One and Affirm compete for consumers’ attention in Walmart stores.
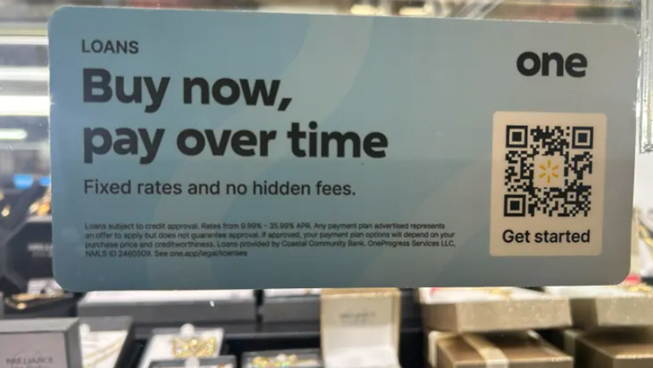
One's advert seen in a Walmart store, reading "Buy No, pay over time" with a QR code labelled "Get Started".
Source: CNBC

As retailers like Walmart move deeper into financial services, how will their presence impact dedicated fintechs like Affirm and Klarna as well as the industry as a whole.

Impact on fintech competitors

Tearsheet research found that 55% of executives in the financial services industry view retail brands as the most significant threat to traditional FIs long term. While Affirm is already competing for wallets in Walmart stores, the entry of a retail brand that owns 8% of the market share in the industry could compel dedicated fintechs to offer more “attractive or creative financing options to both customers and other retailers to maintain market share,” according to Peter Galvin, Chief Growth Officer of NMI, a payments technology provider.

This move may also allow Walmart to deepen its relationship with its customers, who already have access to financial services like debit rewards, early access to pay, and a high-yield savings option through One. “This strategic move not only bolsters Walmart’s competitive edge but also creates a deeper 

connection, enhanced engagement, and personalization for consumers who opt for buy now, pay later (BNPL) options,” said Galvin. _____________________________________________________________________ subscription wall for TS Pro

0 comments on “What will Walmart’s launch of BNPL through One mean for the industry?”

Lending, Member Exclusive, Payments

Affirm wants its data to tell a more complete customer story

  • Affirm is mining its data for a better read on borrowers with its new transformer-based underwriting model.
  • By extracting new signals from existing data, the BNPL firm is betting that its transaction-level view of consumers can become a competitive advantage in its own right.
Sara Khairi | September 24, 2026
Banking, Lending, Member Exclusive, Podcasts, SMB Finance

Live Oak Bank’s BJ Losch on why AI is an accelerant, not a strategy

  • Live Oak Bank grew from lending only to veterinarians into 40 verticals without ever opening a branch.
  • President BJ Losch explains how AI is helping cut SBA loan approval-to-close times from over 100 days toward a two-week target, while keeping the credit decision itself with a human underwriter.
Zack Miller | August 26, 2026
Lending, Member Exclusive

How Figure turned a lending business into a financial network

  • Figure reported second-quarter results, showing that its platform had reached a $1 billion weekly run rate for loan applications by early July.
  • The firm has come a long way since it was founded in 2018, building a more structured lending and capital markets system while increasingly making it intelligent and programmable.
Sara Khairi | August 20, 2026
Banking, Lending

Micro Case Study: LendingClub’s Identity Shift — When the business outgrew the brand

  • LendingClub is rebranding its digital bank Happen Bank to align brand identity with its evolution to an integrated banking ecosystem.
  • The bank is recalibrating its focus to a coordinated system where debt consolidation, credit score improvement, and savings accumulation work in tandem.
Sara Khairi | May 14, 2026
Banking, Lending, Member Exclusive

LendingClub rebrands to Happen Bank as its identity catches up to its model

  • LendingClub (soon Happen Bank) did what few scaled fintechs manage cleanly: it let the business lead, and the brand follow.
  • The company remains lending-centric, but is building out a broader post-loan experience.
Sara Khairi | May 07, 2026
More Articles