
Banking, Member Exclusive

HSBC’s Zing and how banking can learn to do cool and innovative better

  • With a modern UX and targeting a popular market, HSBC's new international money transfer app shows a lot of promise.
  • But it's what Zing -- and HSBC -- didn't do that points to a big opportunity for banks to provide something valuable to customers.
close

Email a Friend

HSBC’s Zing and how banking can learn to do cool and innovative better

A few years ago, I was chatting with Alex Jimenez, who was leading strategy at Zions Bank at the time. He said that most banks’ efforts to keep relevant basically amounted to innovation theater. Instead of trying to keep up with the new, cool things, he suggested that innovation really had to do with asking the right questions. I’ve been using that term ever since.

“Once you define the question really well, then you can brainstorm, and come up with and test ideas. I’ve seen a lot of groups define a question incorrectly that doesn’t solve the problem and what they end up doing fails. Spend a lot of time with a process that’s very specific in defining the question and then you can begin to innovate.”

Asking the right questions

So, last week, when HSBC announced a new app to send money internationally, my first thought went back to my discussion with Alex. 

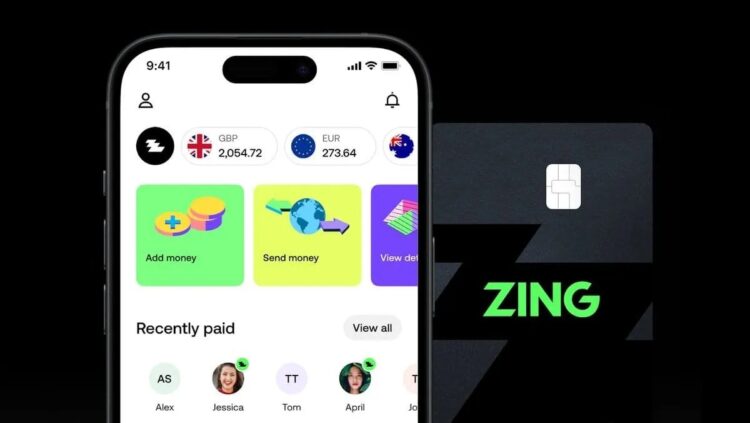
What question was HSBC asking when it decided to build Zing? The answer feels like it would be something like who’s doing something really well and how do we do something similar?

Because the product just looks and feels like competitor Wise (10 million customers) and part of Revolut (38 million customers). It just feels derivative. 

But, hey, that may be enough. Let’s look.

A closer look at Zing

subscription wall for TS Pro

0 comments on “HSBC’s Zing and how banking can learn to do cool and innovative better”

Designing new products, Member Exclusive, Opinion

Banking has had a product mindset problem, but it might be starting to get better

  • The product mindset gap comes down to whether banks build around internal structures or the problems customers are trying to solve.
  • AI is pushing product thinking further, challenging banks to move beyond features and interfaces toward responsive products that understand context and help customers get things done.
Sara Khairi | October 16, 2026
Blockchain and Crypto, Member Exclusive, Payments

Coinbase is taking stablecoin rails into banking, expanding the market for both

  • Coinbase is expanding stablecoin payments through banking networks of all sizes to diversify beyond trading revenue.
  • Moov connects Coinbase to community banks, while Citi opens access to institutional payment flows.
Javarya Kamran | October 15, 2026
10-Q, Member Exclusive

Financial companies are building closer to the customer

  • EverBank-WaFd shows banks moving beyond the digital-versus-branch debate, combining EverBank’s digital deposits and national lending with WaFd’s branches and relationship banking to own more of the customer relationship.
  • Circle-Tazapay takes a similar approach from the payments side, adding banking relationships and local payment rails around USDC.
Sara Khairi | October 14, 2026
Business of Fintech, Member Exclusive

Can banks buy fintechs without losing what makes them work?

  • Can a bank absorb a fintech’s customers, technology, and talent without losing the product judgment and culture that made those assets valuable in the first place?
  • Valley Bank’s acquisition of Bluevine puts that question into practice, with implications for product development, customer acquisition, and technology strategy.
Sara Khairi | October 13, 2026
Artificial Intelligence, Future of Investing, Member Exclusive

Robinhood is giving AI agents a bigger role in the trading workflow

  • Robinhood is moving AI agents from the sidelines into the trading workflow, giving them access to research, strategy-building, and execution, with customers deciding how much authority to hand over.
  • The company is building toward always-on trading, pairing agents with Loops, expanded market hours, and more market-data tools.
Sara Khairi | October 08, 2026
More Articles