Business of Fintech

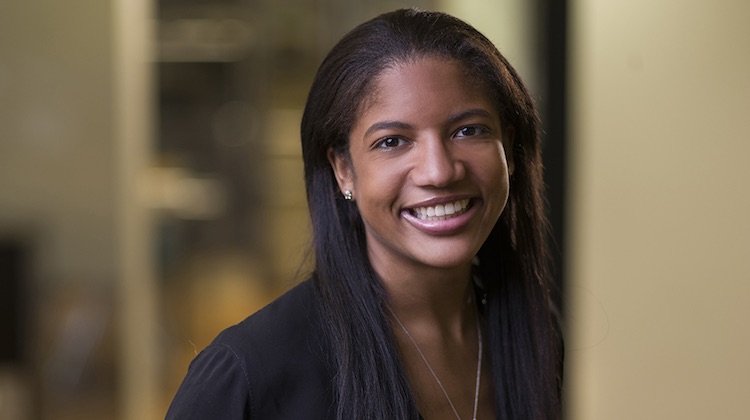
‘The market is really crowded’: Anthemis Group’s Jillian Williams on tough times for personal finance apps

  • Personal finance management is probably the most well-known part of consumer fintech, but many platforms are having trouble monetizing their product offerings
  • As the market for PFM becomes more competitive and banks take on more PFM capabilities, the pressure will fall on third-party PFM apps to provide a differentiated offering for the customer
close

Email a Friend

‘The market is really crowded’:  Anthemis Group’s Jillian Williams on tough times for personal finance apps


subscription wall for TS Pro

0 comments on “‘The market is really crowded’: Anthemis Group’s Jillian Williams on tough times for personal finance apps”

Business of Fintech, Member Exclusive

How Block is turning Square and Cash App into one local growth network

  • Block has connected Square’s seller network with Cash App’s consumer base via Neighborhoods, giving local businesses a way to turn discovery into direct orders, customer relationships, and potentially repeat visits.
  • Neighborhoods is designed to bypass the traditional marketplace model. Its growth will depend on whether Cash App can generate meaningful customer demand and repeat spending without adding another layer of cost for sellers.
Javarya Kamran | November 10, 2026
Business of Fintech, Member Exclusive

Block has built the bridge between Square sellers and Cash App customers. Now it wants more people to cross it.

  • Block’s Neighborhoods connects Square sellers with Cash App users, helping local businesses drive discovery, direct orders, and repeat visits without monthly fees or marketplace commissions.
  • Early growth is promising, with $1 billion in annualized GPV as of June 2026, but the long-term test is whether Neighborhoods drives incremental spending and lasting customer relationships.
Sara Khairi | November 05, 2026
Business of Fintech, Events

Money20/20 and the unfinished business of payments innovation

  • Money20/20 USA spotlighted how agentic AI and stablecoins are reshaping payments, with trust and security still standing in the way of wider adoption.
  • Across 4 key themes, the gist is that payments innovation must move beyond product demos to solve real world challenges without adding complexity for businesses and customers.
Sara Khairi | October 27, 2026
5 questions, Business of Fintech, Member Exclusive

How Bluevine will change under Valley Bank without losing its core

  • Valley Bank is buying Bluevine’s technology, talent, and digital customer-acquisition engine rather than spending years building those capabilities in-house.
  • Bluevine’s test is whether it can retain its speed and product culture while tapping Valley’s banking infrastructure and expanding its reach.
Javarya Kamran | October 20, 2026
Business of Fintech, Member Exclusive

Can banks buy fintechs without losing what makes them work?

  • Can a bank absorb a fintech’s customers, technology, and talent without losing the product judgment and culture that made those assets valuable in the first place?
  • Valley Bank’s acquisition of Bluevine puts that question into practice, with implications for product development, customer acquisition, and technology strategy.
Sara Khairi | October 13, 2026
More Articles