Remitly’s Q1 in review — and why its WhatsApp integration could be a turning point for fintech UX
Matt Oppenheimer, Remitly’s co-founder and CEO, shares key takeaways from the company’s Q1 earnings, while Ankur Sinha, Chief Product and Technology Officer, shares what the newly launched WhatsApp integration signals about the future of remittances and fintech UX.
We also explore the role of Remitly's conversational AI with the new integration.
A conversation on Remitly’s financial performance, platform integration, & conversational AI developments
The tech world loves a good shake-up story, especially when it comes to payments. But when the goal is only to upend an industry, things can get lost in translation. While speed and innovation are great, and one of the essential aspects of payments, for many, even small barriers to sending money can feel like an insurmountable challenge. That’s the market Remitly has focused on. The payments firm is solving a more fundamental problem — how to make sending money home a little more predictable, a little less frustrating.
Earlier this month, Remitly shared its Q1 2025 financial results. First quarter revenue was $361.6 million, up 34% YoY, and active customers increased to over 8 million, up 29%.
A week before its earnings release, the company announced its integration with WhatsApp. Through WhatsApp, Remitly users can send, monitor, and control their international transfers without downloading another app. Remitly’s goal isn’t necessarily to get users to only use the app — it’s to keep them in the Remitly ecosystem, regardless of channel.
I spoke with Matt Oppenheimer, co-founder and CEO of Remitly, to discuss the Q1 earnings highlights, and with Ankur Sinha, Chief Product and Technology Officer, to learn more about the new WhatsApp integration and what this launch signals about the future of remittances and fintech UX.
We also explore the role of Remitly’s conversational AI in enabling users to send money directly within WhatsApp, check live exchange rates and fees before sending, and track transfers — all while receiving support in a single conversation thread.
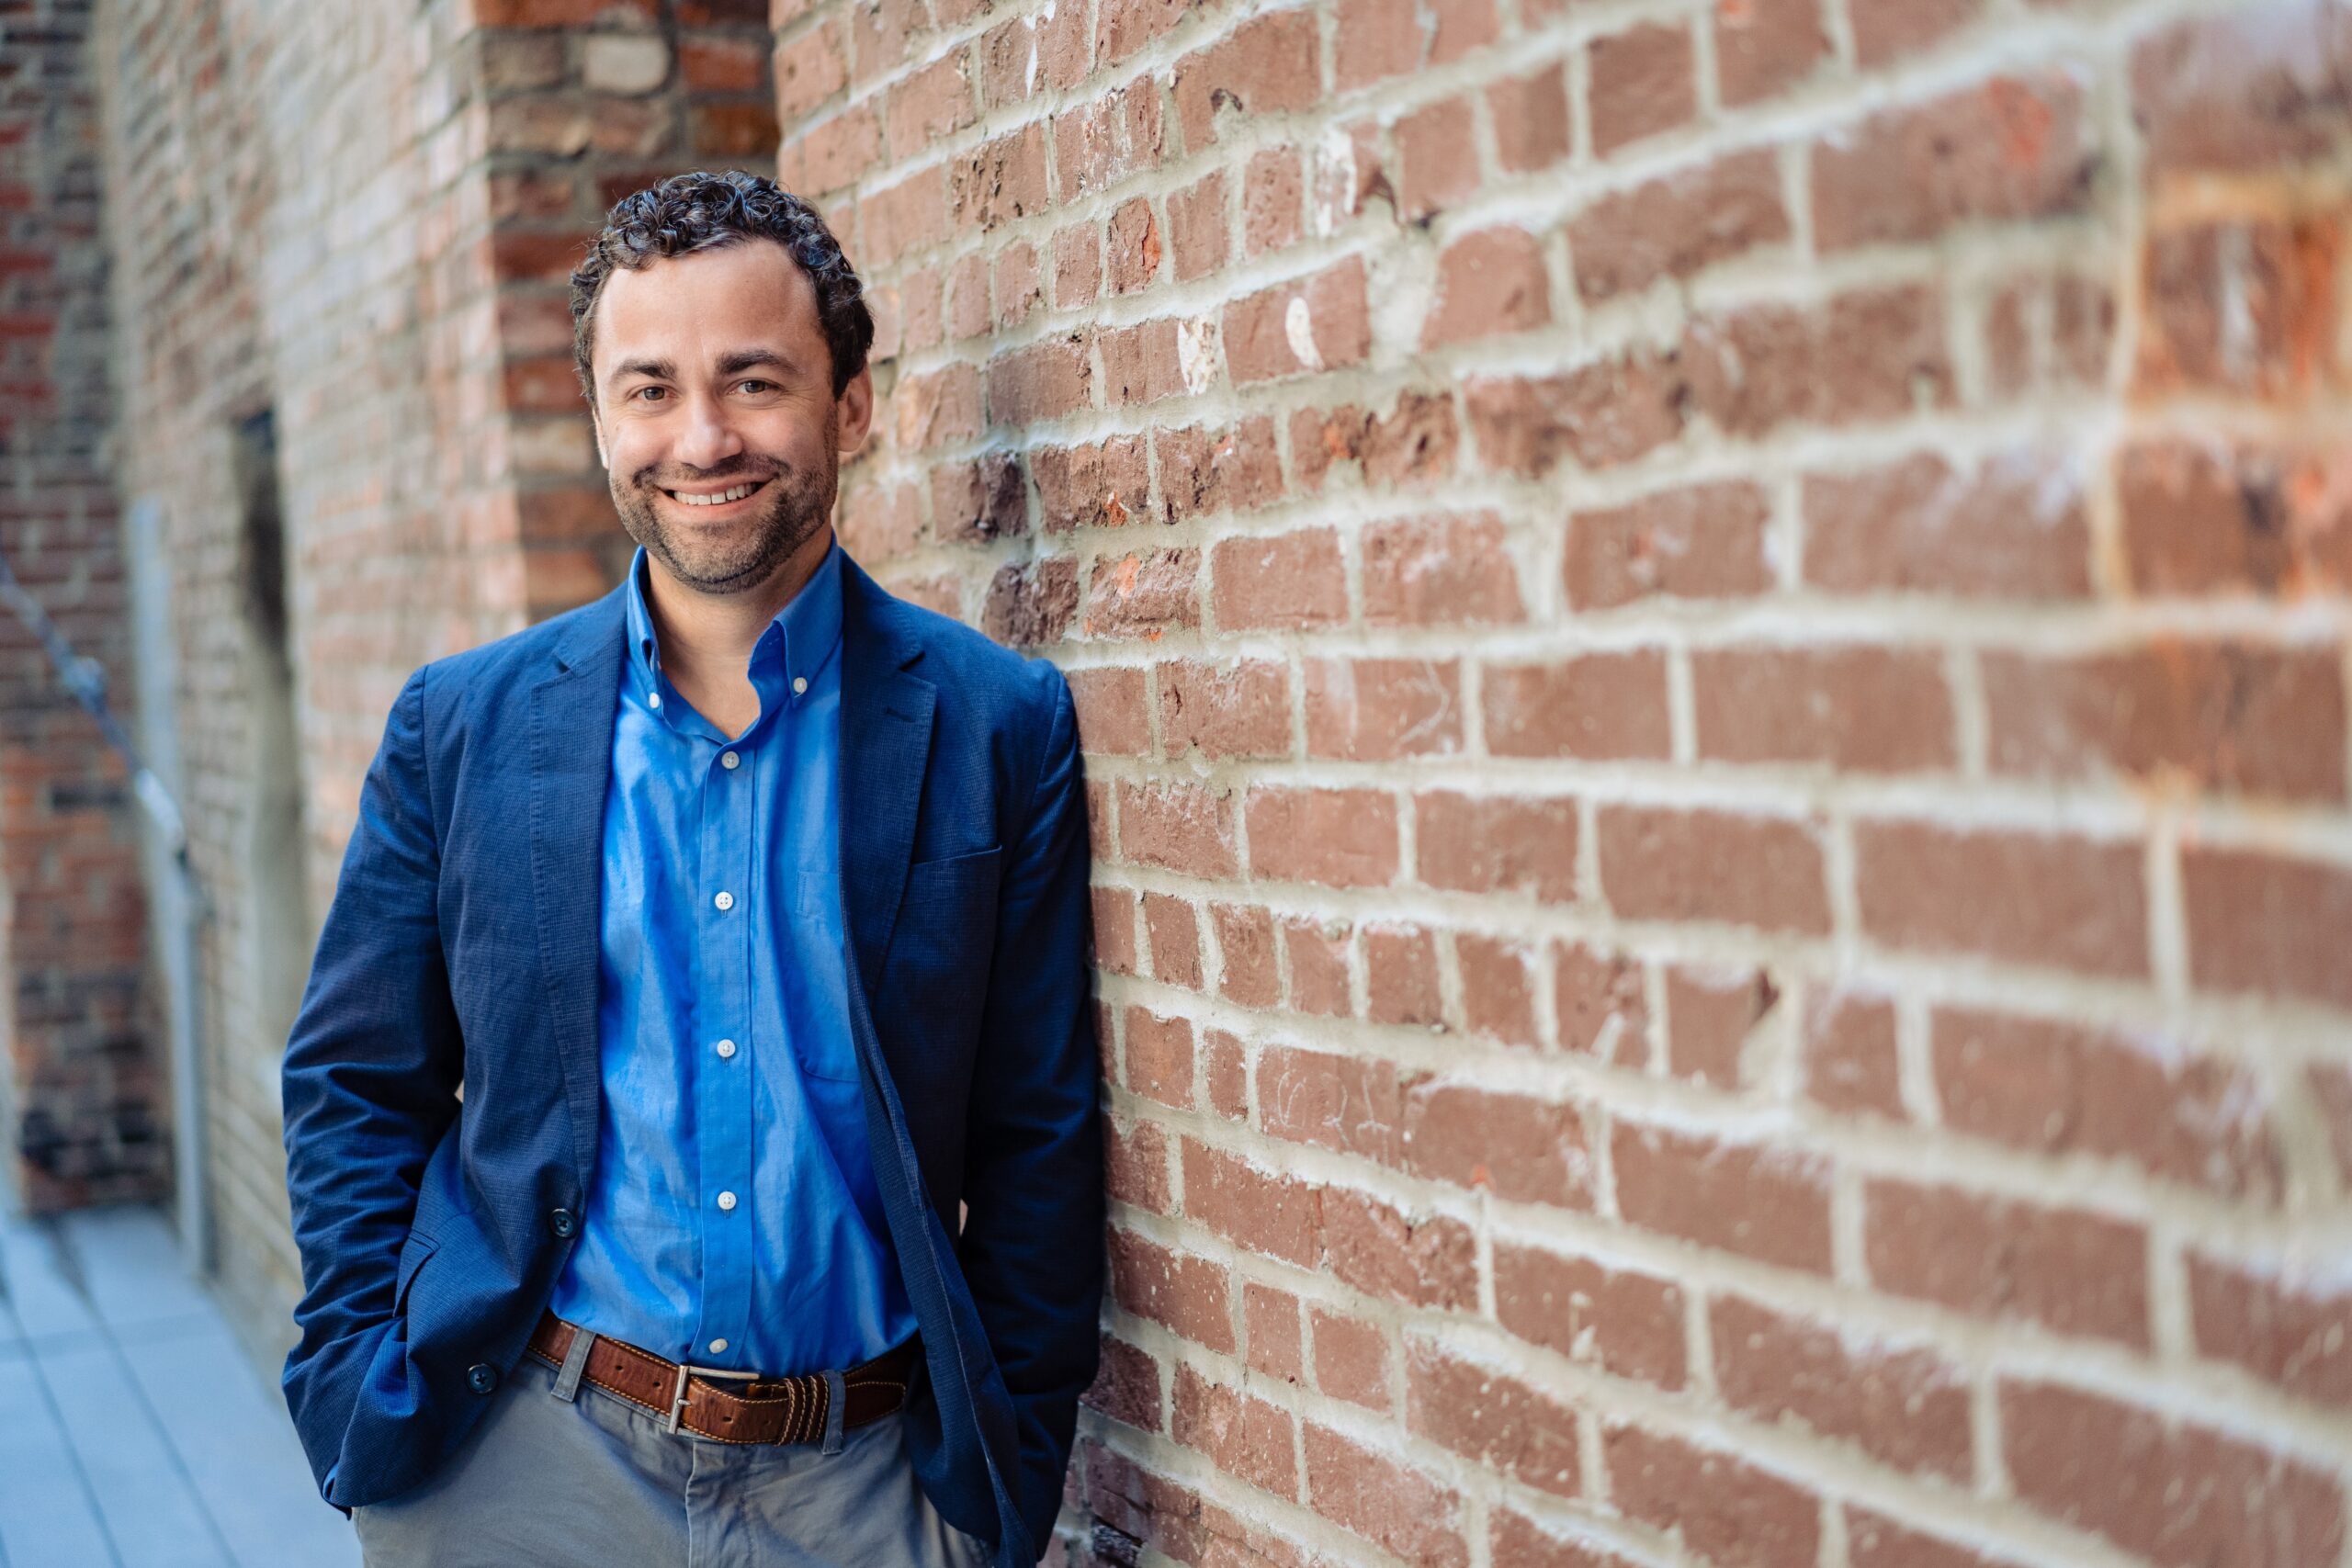
Matt Oppenheimer, Co-Founder and CEO, Remitly
Q: What key strategies contributed to Remitly’s Q1 2025 positive outcome?
Matt Oppenheimer: Our strong Q1 results reflect the compounding effect of three core drivers:
…
0 comments on “Remitly’s Q1 in review — and why its WhatsApp integration could be a turning point for fintech UX”
The product mindset gap comes down to whether banks build around internal structures or the problems customers are trying to solve.
AI is pushing product thinking further, challenging banks to move beyond features and interfaces toward responsive products that understand context and help customers get things done.
EverBank-WaFd shows banks moving beyond the digital-versus-branch debate, combining EverBank’s digital deposits and national lending with WaFd’s branches and relationship banking to own more of the customer relationship.
Circle-Tazapay takes a similar approach from the payments side, adding banking relationships and local payment rails around USDC.
Can a bank absorb a fintech’s customers, technology, and talent without losing the product judgment and culture that made those assets valuable in the first place?
Valley Bank’s acquisition of Bluevine puts that question into practice, with implications for product development, customer acquisition, and technology strategy.
Robinhood is moving AI agents from the sidelines into the trading workflow, giving them access to research, strategy-building, and execution, with customers deciding how much authority to hand over.
The company is building toward always-on trading, pairing agents with Loops, expanded market hours, and more market-data tools.