Coinbase is taking stablecoin rails into banking, expanding the market for both

After launching USDC in 2018 with Circle, Coinbase added USDC support to Coinbase Commerce in 2019, allowing merchants to accept the stablecoin directly. The bigger shift came in 2025, when the crypto exchange launched Coinbase Payments, a stablecoin payments stack that lets businesses and payment platforms integrate USDC payments into their existing systems.

Now Coinbase is extending that infrastructure into traditional banking. In September 2026, it partnered with Moov, a payments infrastructure provider whose platform connects more than 1,000 community banks and credit unions to payment systems. Coinbase brings stablecoin payment and settlement capabilities, while Moov offers a potential distribution channel across its network of community banks and credit unions. The announcement does not say all these institutions will offer Coinbase’s stablecoin capabilities or specify when individual institutions will activate them.

Later that month, Coinbase also expanded its collaboration with Citi, connecting its stablecoin payments infrastructure to the bank’s institutional banking and merchant-acquiring systems.

The two partnerships approach the same strategy from opposite ends of the financial system. Moov gives Coinbase a route into smaller institutions that may lack the resources to build their own stablecoin technology stack. Citi, which moves approximately $6 trillion a day, connects Coinbase’s capabilities to large corporate and institutional clients. 

…

Coinbase-Moov: Extending stablecoin infrastructure to community banks


…


After launching USDC in 2018 with Circle, Coinbase added USDC support to Coinbase Commerce in 2019, allowing merchants to accept the stablecoin directly. The bigger shift came in 2025, when the crypto exchange launched Coinbase Payments, a stablecoin payments stack that lets businesses and payment platforms integrate USDC payments into their existing systems.

Now Coinbase is extending that infrastructure into traditional banking. In September 2026, it partnered with Moov, a payments infrastructure provider whose platform connects more than 1,000 community banks and credit unions to payment systems. Coinbase brings stablecoin payment and settlement capabilities, while Moov offers a potential distribution channel across its network of community banks and credit unions. The announcement does not say all these institutions will offer Coinbase’s stablecoin capabilities or specify when individual institutions will activate them.

Later that month, Coinbase also expanded its collaboration with Citi, connecting its stablecoin payments infrastructure to the bank’s institutional banking and merchant-acquiring systems.

The two partnerships approach the same strategy from opposite ends of the financial system. Moov gives Coinbase a route into smaller institutions that may lack the resources to build their own stablecoin technology stack. Citi, which moves approximately $6 trillion a day, connects Coinbase’s capabilities to large corporate and institutional clients. 

The partnerships give Coinbase access to established banking and payment networks, while allowing banks and businesses to integrate stablecoin payment capabilities into their existing operations without having to build the underlying infrastructure from scratch.

This infrastructure expansion gives Coinbase a potential growth avenue beyond trading revenue, which fluctuates with crypto market activity. In a September 2026 Bloomberg interview, Coinbase CEO Brian Armstrong said the stablecoin market, valued at around $300 billion, could grow nearly tenfold by 2030.

Coinbase-Moov: Extending stablecoin infrastructure to community banks


…
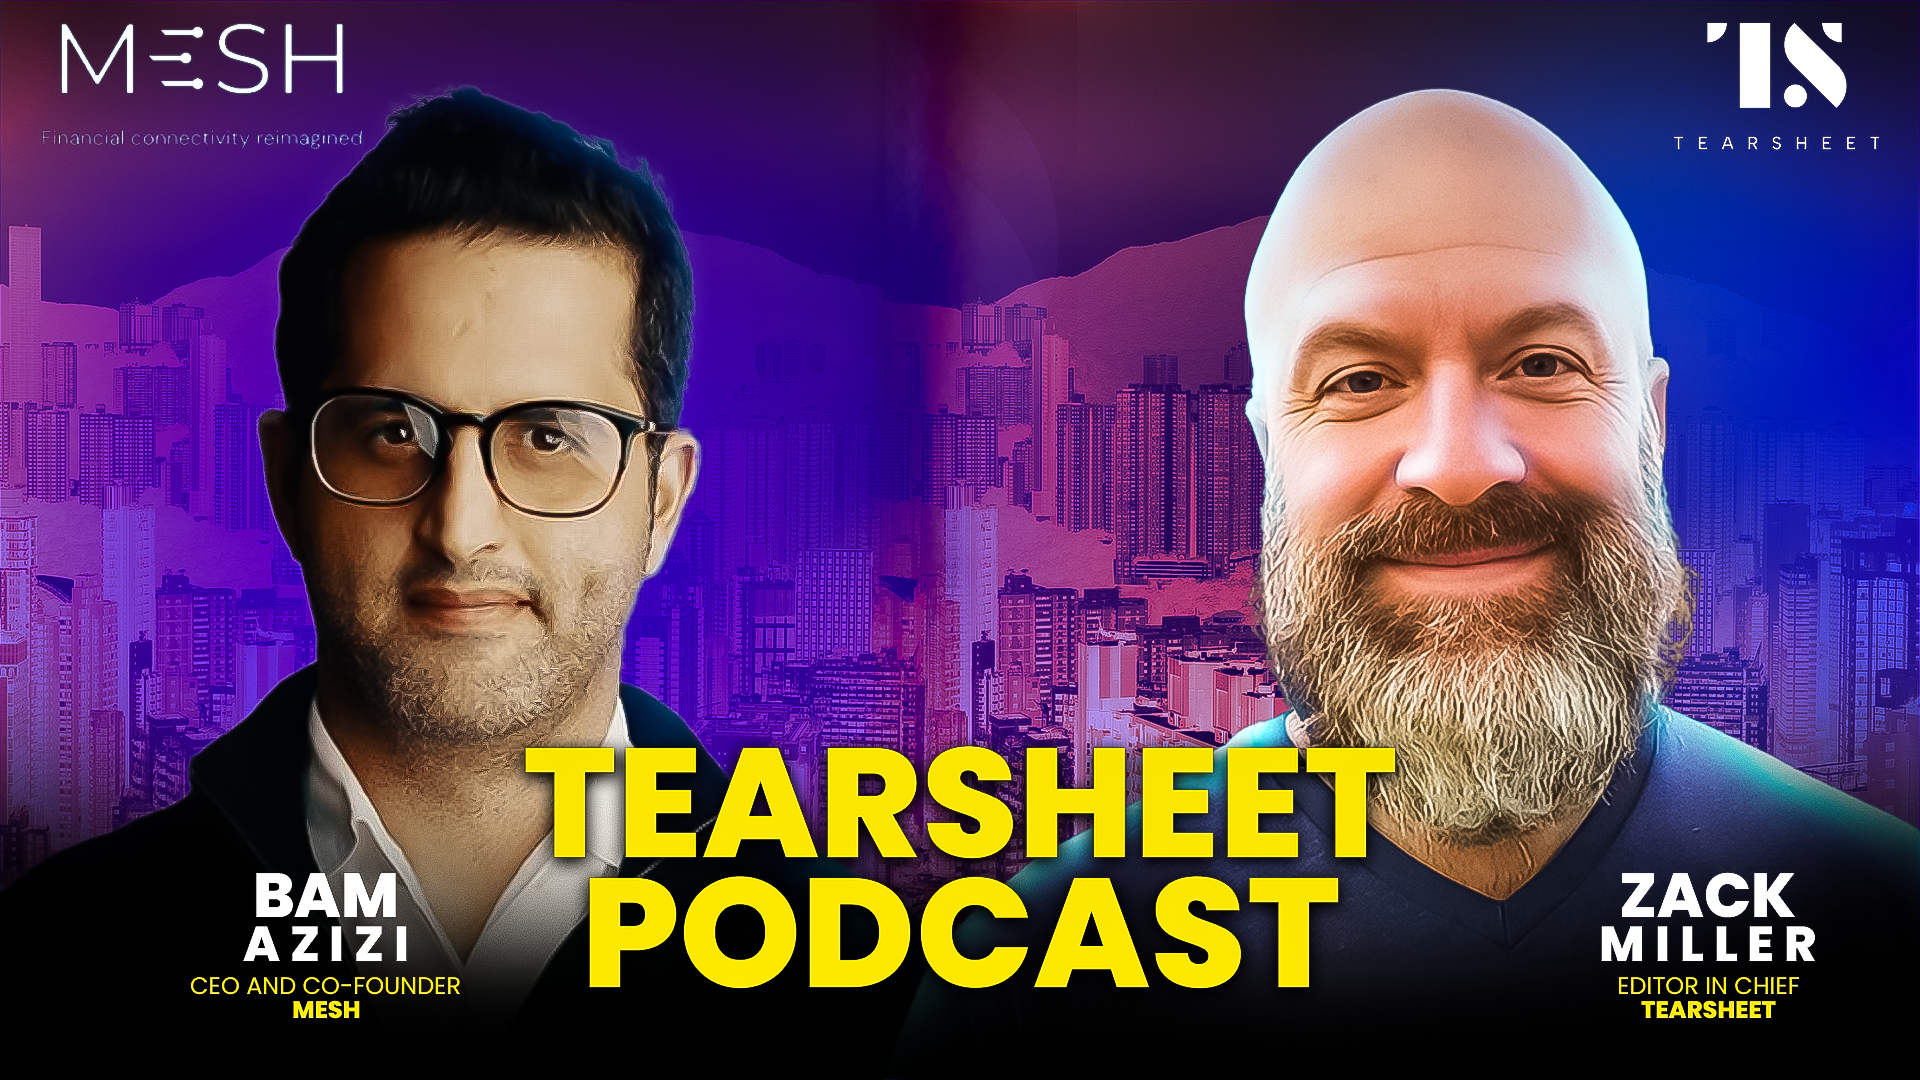


Building the bridge between crypto and coffee shops: A chat with Mesh’s Bam Azizi

crypto bam azizi

The Tearsheet podcast often explores the intersection of financial services and technology. What makes this exploration unique is its focus on emerging trends, like the connection of the Web3 technologies of crypto and blockchain with the traditional finance ecosystem. Today, Bam Azizi, the co-founder and CEO of Mesh, joins me on the podcast.

Founded in 2020, Mesh is an embedded financial platform designed to simplify crypto transactions by enabling real-time connectivity and asset transfers. Previously, Azizi co-founded the cybersecurity company, No Password. Azizi has a strong background in robotics and software engineering.

He is now leading Mesh towards a future focused on tokenized assets.“Everything will be tokenized because it’s easier to transfer and build,” says Azizi. He emphasizes the importance of addressing market gaps. Mesh integrates exchanges and enables crypto payments.

The Evolution of Crypto & Embedded Finance

Embedded finance has emerged as a pivotal market structure in fintech. It allows financial services to be seamlessly integrated into non-financial platforms. Azizi sees Mesh as a connection aggregator, not a data aggregator. This sets it apart from competitors like Plaid. “Plaid is the right solution for traditional assets,” Azizi explains. “We are the right solution for the crypto industry.” Traditional platforms focus on aggregating banking data — Mesh enables transactional capabilities. This includes transferring assets between exchanges and using crypto for payments.

Crypto Payments and Practical Use Cases

Mesh’s offerings have evolved from enabling cryptocurrency deposits to powering crypto payments. Azizi describes the creation of MeshPay, which is a comprehensive solution that addresses the unique challenges of crypto payments within a commercial setting. “Imagine paying at a coffee shop with crypto through Apple Pay,” says Azizi. This vision stems from a real-world use case where a small business embedded Mesh to accept crypto as a payment method. For regions grappling with hyperinflation, functionality like this offers real practical advantages.

Tokenized Assets: The Future of Finance

Azizi strongly advocates adopting tokenized assets. He predicts that “everything will be tokenized” in the coming decade. Tokenization can simplify asset transfers, improving accessibility and mirroring the digitization wave of the past two decades. Azizi believes traditional processes are inefficient. He points to asset transfers between brokerage accounts as an example. These processes are often cumbersome. Tokenized systems promise to end these inefficiencies. They pave the way for streamlined financial operations.

Challenges and Opportunities with Regulation

Discussing regulatory frameworks, Azizi underscores the importance of clarity. “Healthy regulation benefits everyone,” he notes. Azizi emphasizes how clear guidelines could boost cryptocurrency adoption and innovation. Mesh’s non-custodial model aligns with the crypto community’s ethos of decentralization. It resonates with users who prioritize privacy and control over their assets.

The Big Ideas

  1. Mesh bridges data aggregation with actionable connections. “We’re not just aggregating data; we’re enabling transactions,” Azizi explains. Mesh’s approach bridges the gap between traditional finance and the burgeoning crypto ecosystem.
  2. Embedded finance evolves alongside tokenized assets. Azizi predicts a shift where traditional and tokenized assets coexist. “Embedded finance must mirror this hybrid future,” he says.
  3. Mesh enables seamless crypto payments for everyday transactions. Azizi highlights MeshPay’s potential. He says, “Users can connect their Coinbase account and pay for things with crypto, just like using a credit card.”
  4. Clear regulations could unlock growth in crypto adoption. “We need clear regulations,” Azizi states. He believes that regulatory clarity will drive adoption, particularly among traditional financial institutions.
  5. Mesh focuses on privacy-focused, non-custodial solutions for crypto users. Reflecting on his experience with No Password, Azizi emphasizes, “We don’t store any user data.” This approach aligns with the decentralized ethos of crypto.

Listen to the full episode

Subscribe: Apple Podcasts I SoundCloud I Spotify

Watch the full episode