Who is building the modern bank?


The “Letter from the Editor” is a biweekly series of exclusive insight and opinion-driven analysis from Tearsheet’s Managing Editor Sara Khairi, connecting ideas, questioning assumptions, and tracking shifts across both mature and emerging trends in financial services.

This is now PRO-only content. Subscribe to PRO so you never miss a Letter from the Editor exclusive.

Issue # 14

Banks have long relied on technology providers for everything from core systems and payment infrastructure to software, data, and specialized capabilities. What is changing now is how deeply those providers are becoming embedded in the bank itself.

A bank today might run its core on one provider, its cloud infrastructure on another, use a third party for payments, bring in fintechs for specific capabilities, rely on external data providers, and increasingly put AI models and agents on top of all of it. They can become part of the workflows, infrastructure, data flows, and decisions that keep the institution running.

The bank still owns the customer, the balance sheet, and the regulatory consequences when something goes wrong. But increasingly, more of the capabilities underneath that relationship are being built, operated, and maintained by companies outside the institution.

So, if more of the technology that makes a bank work is being built elsewhere, what does it actually mean to build a bank today? The answer starts with how all the pieces fit together.

The technology advantage is in the connections

As external providers take on larger pieces of the bank’s infrastructure, the connections between those pieces become part of the technology strategy itself.

KPMG’s 2026 Banking Technology Survey found that 71% of banking executives agree their organizations need to invest in modernizing platforms to bring new or enhanced products and services to market, up from 46% in 2025. Another 77% said technology is a primary driver or one of several key factors in acquisition strategy over the next two to three years.

A modern core on top of fragmented data doesn’t get a bank very far. An AI agent is only as useful as the customer context it can reach. And even the best new capability loses value if employees have to move across six different systems to use it. 

The technology advantage is increasingly shifting away from individual products and toward how well a bank can make externally built systems function as one. That connective architecture may become one of the most important pieces of the modern bank.

Who controls the connective architecture?

…

Three regional banks, three different layers of the financial stack

The most important change in regional banking today is structural. These banks are moving away from a uniform modern banking model and toward specialized roles within the financial stack.

Across Citizens, Truist, and KeyBank, modernization is increasingly becoming a means to a larger end: repositioning the bank’s role in the financial ecosystem.

Citizens: The operating system bank

At Citizens, modernization is increasingly treated as part of the operating fabric rather than a discrete program.

Michael Ruttledge, the bank’s CIO, described a shift that is less about adopting new technologies than about removing legacy constraints. The bank has migrated its business applications to AWS and Azure and is in the process of decommissioning its remaining data centers.

“We’re the only super regional bank that is completely in the cloud,” Ruttledge said.

But the cloud transition is only one layer of a broader restructuring effort. Citizens’ “Next Gen Technology” initiative brings together DevSecOps practices, API-based architecture, workforce reskilling, mainframe retirement, and efforts to strengthen core system resilience.

Within that framework, the bank now has more than 70 AI use cases in progress across areas such as underwriting, software development, and internal operations.

…


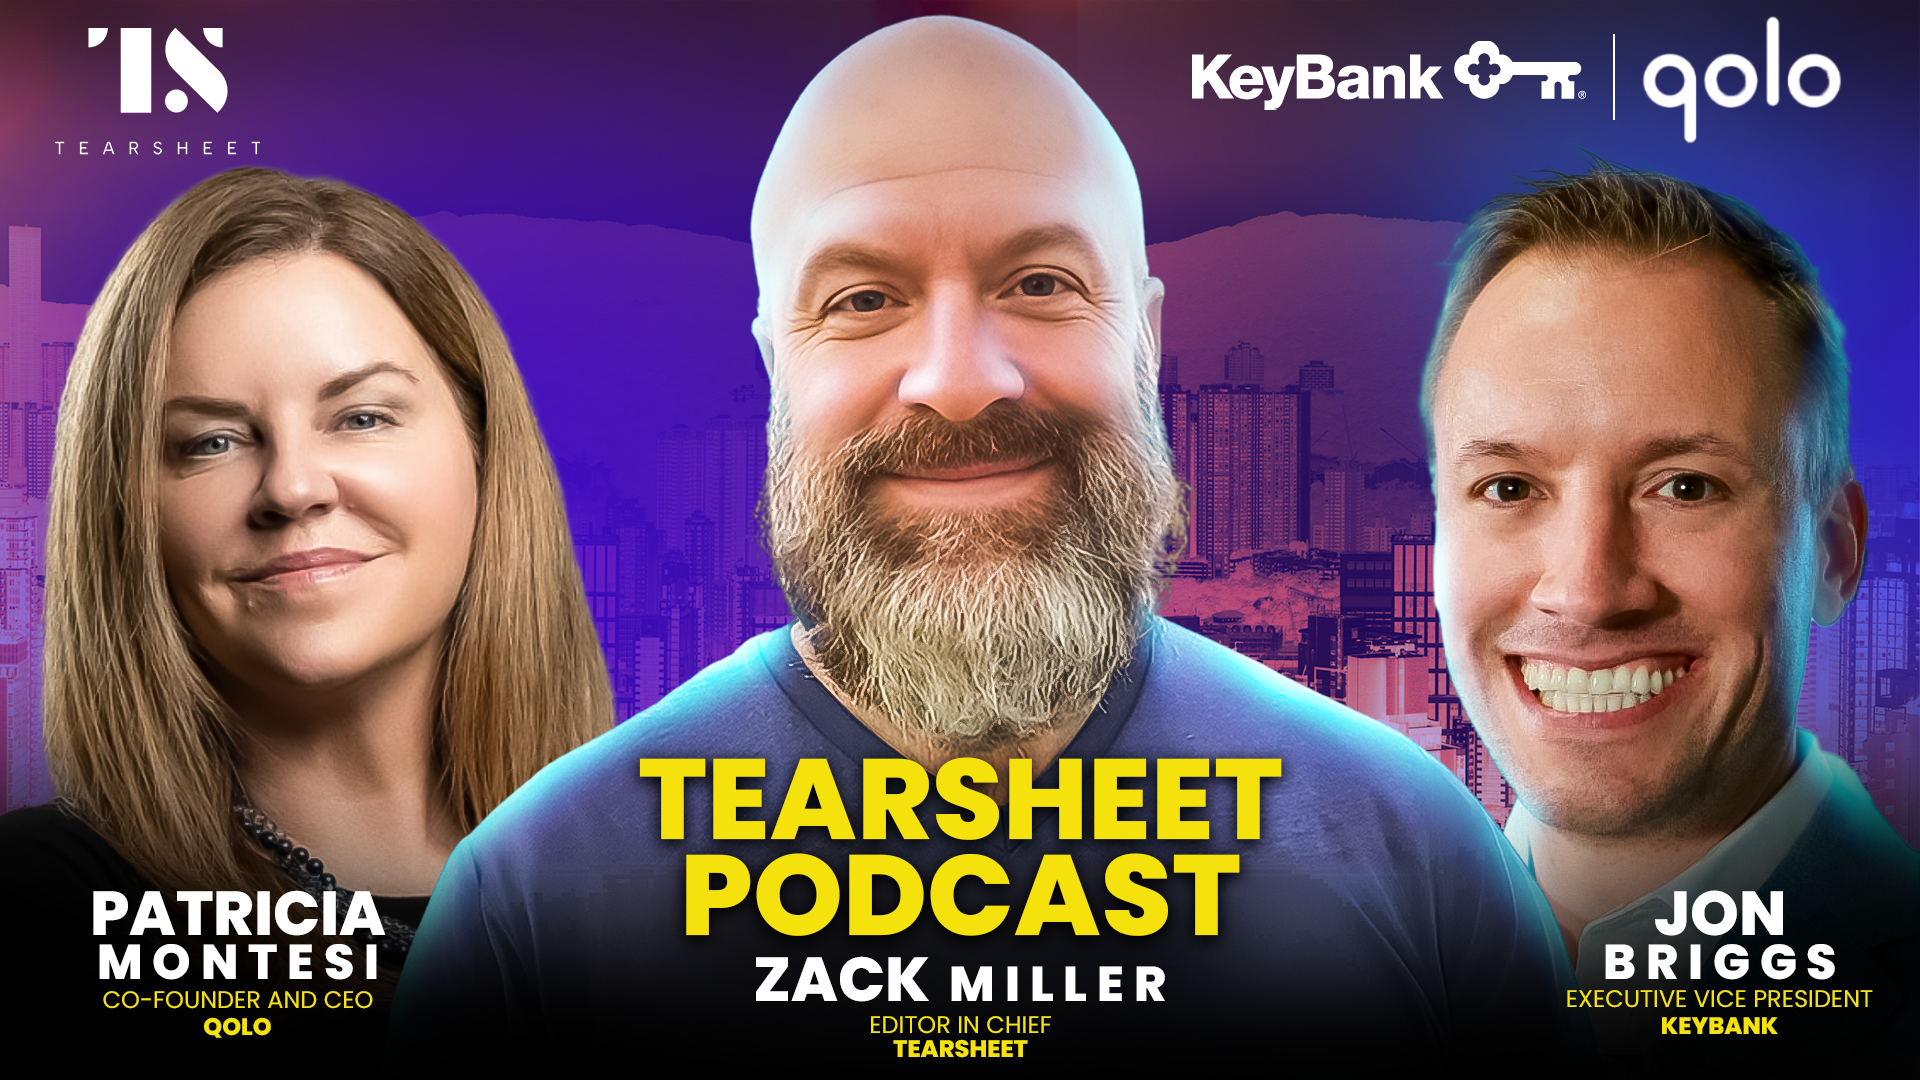
Reshaping embedded finance with KeyBank’s Jon Briggs and Qolo’s CEO Patricia Montesi

KeyBank -- Qolo partnership on Tearsheet Podcast

Strategic partnerships – those relationships between traditional financial institutions and fintechs – have become really integral as banks seek to modernize their offerings and fintechs aim to scale their operations and get distribution.

KeyBank and Qolo have teamed up on an embedded finance offering. On today’s episode, we sit with Jon Briggs, Head of Product and Innovation at KeyBank, and Patricia Montesi, Co-founder and CEO of Qolo. 

Their collaboration story begins two years ago when a single slide in Qolo’s pitch deck caught KeyBank’s attention. “We still talk about it today,” Montesi recalls. “It was the ‘Series A: Winter Slide’, which was all about how fintech had created this spiderweb ecosystem of suppliers. And sort of put the burden back on banks and corporates to bring it all together.” Their shared goal of simplifying fintech sparked a partnership that’s addressing how treasurer think about and use banking. 

As Briggs explains, “We enter partnerships because they need a lot of mind share, a lot of sweat equity.” What set Qolo apart was their deep understanding of banking-grade compliance and operational risk. This makes the integration process less painful. The result of their collaboration? KeyVAM, a virtual account management system that simplifies money movement by consolidating balances and transactions in a virtual platform, reducing the need for organizations to manage multiple accounts or complex account structures.

KeyBank’s Jon Briggs and Qolo’s Patricia Montesi are my guests today on the Tearsheet Podcast.

Genesis of a Powerful Fintech Partnership

The collaboration between KeyBank and Qolo is a testament to the power of strategic bank-fintech partnerships. Briggs highlights the importance of cultural alignment. He states, “What distinguishes a partner from a vendor is that cultural and executive alignment.” Their shared vision has been key in overcoming the challenges of launching a new product.

Unveiling KeyVAM: A New Era in Treasury Management Solutions

KeyVAM represents a significant leap in core banking modernization. Briggs describes it as “a hyper-modern core ledger” that allows clients to open sub-accounts instantly. What sets it apart is its robust UI and API capabilities. This puts self-serve at the forefront of the product.

Rethinking Account Opening and Management

One of the most striking features of KeyVAM is its ability to streamline account opening. “We put our clients in the driver’s seat,” Briggs explains. “They can do it in as little as 60 seconds.” This quick speed and instant payment setup mark a major step forward in digital banking.

Strategic Importance of Embedded Finance

The development of KeyVAM is not just about solving current client needs. It is a strategic move in the evolving landscape of embedded finance. Briggs notes, “Deposits are going to become even more important for banks going forward, and it’s frankly going to be the gating item for growth.” KeyVAM allows KeyBank to compete with technology and innovation rather than just on rate.

Overcoming Challenges in Fintech Integration

Montesi stresses the importance of education when introducing new technologies in traditional banks. “It’s a really big part of understanding it at that level because a lot of real-time, instant, virtual – a lot of risk and compliance people get nervous when they hear these things,” she explains. This focus on education has been essential for adapting and integrating smoothly.

The Big Ideas

  1. Cultural Alignment has been crucial in navigating challenges and ensuring a successful partnership. Briggs shares, “What distinguishes a partner from a vendor is that cultural and executive alignment.”
  2. KeyVAM is a recent innovation in core banking systems. Briggs explains, “Nobody’s innovated around the core operating account which is at the centre of every banking relationship.” Such banking innovations represent a significant step forward in business banking solutions.
  3. Speed and Efficiency are the game-changers in digital banking. The ability to open accounts in as little as 60 seconds is a game-changer. Briggs notes, “We put our clients in the driver’s seat,” highlighting the focus on client empowerment and efficiency.
  4. KeyVAM helps KeyBank stay competitive by focusing on the value of deposits. This approach is key in navigating today’s changing regulations. Briggs highlights, “Deposits are going to become even more important for banks going forward.” KeyVAM positions KeyBank to compete effectively in this landscape. It results in efficient cash flow management by streamlining accounts. 
  5. Montesi stresses the importance of education and the integration of new technologies. He states, “You have to spend the right amount of time educating folks along that journey.” This focus on education has been crucial in overcoming integration challenges.

Listen to the full episode


Subscribe: Apple Podcasts I SoundCloud I Spotify I Google Podcasts

Read the full transcript (TS Pro subscribers)

subscription wall for TS Pro