Titan’s banking-native AI bet: Banking intelligence can’t be retrofitted 

Over the past year, technology vendors have been using a new phrase to describe AI for financial institutions: adapted for banking. Whether the language is “trained on banking data” or “wrapped in a banking interface,” the implication is the same: a general-purpose model was retrofitted for an industry that it was never designed for.

However, this approach equates knowledge to understanding. Banking is not a general knowledge domain; it is a structured system of relationships between products, policies, regulations, risk frameworks, and supervisory expectations that bankers spend years learning to navigate. A model that has read about banking is not the same as a model designed to work within it.

Titan was built for banking. The platform combines three things. Banking-native models trained to reason through real regulatory and supervisory logic. A context layer grounded in both industry knowledge and each institution’s own policies and data. And agents that put that intelligence to work across risk, compliance, underwriting, and operations, all while keeping humans in control. 

This architecture earned Titan the AI Startup of the Year Award at Tearsheet’s AI Innovation Awards 2026. Tearsheet spoke with Arjun Sirrah, Titan’s Founder and CEO, about why banking-native AI requires a different foundation, what it takes to reach production inside a regulated institution, and where the market is headed.
Arjun Sirrah, Founder & CEO, Titan 


Q: Why did Titan choose to build banking-specific models instead of adapting general-purpose LLMs?

Arjun Sirrah, Titan: Banking doesn’t need generalist AI that knows a little about everything. It needs AI that understands the industry at a deep level, including the relationships among products, records, policies, risk tolerances, and both regulatory and supervisory expectations. A general-purpose model wasn’t built to understand why a commercial credit decision differs from a consumer lending decision, how an institution’s policy may differ or be more restrictive than the underlying regulation, or what an examiner will expect to see after that decision is made.

We understood that distinction because our team has lived inside banks. We’ve built and implemented banking products, managed operations and technology, and worked through second-line reviews, audits, and examinations. That experience showed us that banking context wasn’t something to be added at the end. Security, auditability, regulatory reasoning, and institutional accountability had to be designed into the platform.

That’s why Titan combines secure access to foundation models with banking-native models, a banking context layer, and supervised agents. The goal isn’t to make AI sound more like a banker. It’s to give it the structure and context needed to actually reason through real banking work in a way that a banker, risk officer, or examiner can follow and trust.

Q: What was the hardest part of building banking-native models that FIs could actually deploy in production?

Arjun Sirrah, Titan: The hardest part was building a platform around models that could not only produce an accurate, relevant answer, but also one that banks could safely use in a live workflow with confidence and verify.

To reach production, banks must solve several problems all at once. They have to select the appropriate model, protect sensitive information, control access, understand how an output was produced, ground that output in current policies and procedures, document what happened, and determine where human review is required. Then that technology has to fit into an actual workflow without forcing an institution to replace every existing system or redesign its operating model overnight. Assembling all of those pieces independently and correctly is a genuinely hard problem.

That’s why Titan was built around three components that work together: banking-native models, context, and agents. The models include Titan’s Banking Model, designed for the precision and regulatory reasoning banking requires, alongside secure access to frontier LLMs, routed to the right model for the task. The context layer grounds every output in a proprietary knowledge graph that encodes how banking works across products, regulations, and risk frameworks, and in some deployments, a second knowledge graph or ontology built from the institution’s own policies, procedures, and data. The agents then connect that intelligence to real banking workflows, handling the searching, retrieving, and documenting, while surfacing recommendations to human experts for review and final decision. Production readiness comes from making all three work as a single system rather than assembling them independently.

Q: What is one lesson you’ve learned about building banking-specific models that surprised you?

Arjun Sirrah, Titan: A key lesson is that governance doesn’t have to slow AI adoption. When it’s designed in from day one, governance can actually accelerate it.

Banks aren’t resistant to useful technology, but they’re risk-averse by nature, and their hesitation usually comes from unanswered questions, things like: Where is the data going? Which model is being used? What information informed the response? Can we reconstruct what happened? Who reviewed the recommendation? If those questions are addressed only after a pilot, the project will likely stall just as it begins to show value. But if these are answered right at the start as part of the design itself, the various teams can evaluate the same system together.

We’ve also learned institutions don’t have to start with the most autonomous or complex use case. They can begin by giving employees a secure, governed alternative to unapproved shadow AI tools, then ground those outputs in the institution’s approved policies and procedures, and finally introduce supervised agents into targeted workflows. This way, governance is the foundation for scaling, allowing an institution to move from experimentation to production with greater ease and confidence, rather than a gate at the end of innovation.

Q: Titan’s Banking Agents automate underwriting, risk, and compliance workflows. What makes banks comfortable trusting these models and agents with higher-stakes decisions?

Arjun Sirrah, Titan: Trust begins with defining the AI agent’s role correctly right from the start. Titan’s agents aren’t designed to replace the accountable banker or make opaque final decisions. They’re designed to do the legwork: collect the needed information, retrieve the relevant policies and procedures, analyze that data against those requirements, and finally produce a recommendation for a human to review. The banker remains responsible for the judgment and review at all the appropriate control points, and ultimately, the final decision.

Several design principles reinforce this approach. The agents are grounded in the institution’s own products, data, policies, and risk tolerances. Their work is logged, traceable, and reviewable at any time. They combine AI reasoning with defined tools and approval steps, and they surface their findings to human experts rather than hiding the process behind a black-box answer. This gives risk, compliance, and business teams the ability to inspect not only the recommendation, but the context and reasoning behind it.

Institutions become much more comfortable when AI expands the capacity of their people without removing the judgment or accountability. The machines handle the repetitive but important tasks: the searching and retrieving, the staring and comparing. This lets the people focus on the actual decision-making that requires experience, interpretation, and responsibility.

Q: Since launching in 2025, what has been the biggest change you’ve seen in how banks approach AI adoption?

Arjun Sirrah, Titan: AI is beginning to be treated less as an isolated experiment and more as a new operating layer within banking infrastructure. That is the biggest shift we’ve seen since launching in October 2025, and it has happened faster than most expected.

Early conversations were mostly centered on experimentation, model selection, and general-purpose productivity. Banks were testing tools, but many hadn’t really established the path from an individual use case to a fully deployed, controlled enterprise capability. Increasingly, the conversation is now about production: replacing ungoverned AI usage, grounding outputs in actual institutional knowledge, selecting workflows with clear operational value, and building the auditability and human oversight required to scale both responsibly and effectively.

What’s also emerging is a deeper realization about why so many early AI deployments underdelivered. It wasn’t the model. It was the absence of banking context. General-purpose models don’t understand the relationships between a bank’s products, policies, regulatory obligations, and risk frameworks. Without that structure, outputs may sound reasonable but don’t reflect how banking actually works. Institutions are starting to ask harder questions about what knowledge their AI is reasoning from, and whether that knowledge was built for banking or borrowed from somewhere else entirely.

We’re also now seeing institutions think more holistically. They’re no longer looking for a chatbot or a single-point solution. Instead, they’re examining their data, processes, and operating models as a whole, and asking how AI can improve the way the institution works across risk, compliance, underwriting, and operations if the right context is invoked at the right time. Titan’s rapid growth since emerging from stealth, and the pace at which institutions are replacing generic, ungoverned tools with governed, auditable capabilities, reflect that shift.
How BILL is rebuilding for the Fortune 5 million and gearing up to take big swings on AI

For most small and midsize businesses, financial operations still look a lot like they did a decade ago. Bills get keyed in manually. Receipts pile up. W-9s get chased down at tax time. While the tools have multiplied, the work hasn’t gone away. “Most finance teams work in an incredibly manual way,” says Michael Cieri, Chief Product Officer at BILL. “There’s a ton of work done by finance professionals that could be automated, and could actually be done better through the use of technology.”

The gap between the promise of modern financial software and the day-to-day reality of running the books at a small business is something BILL has spent nearly two decades trying to close. 

The company processes over 1% of US GDP in payments and has moved more than a trillion dollars across its platform – a scale that gives it both a data advantage and a particular sense of accountability. When you’re handling that volume of transactions for the long tail of American businesses, the stakes of getting automation wrong are very high.

Cieri joins us on the show to talk through where BILL’s product thinking stands today: how Cieri’s team decides when to take big swings versus make incremental improvements, how it builds and validates AI features for a high-trust domain.

Watch the episode

Listen to the full podcast

Subscribe: Apple Podcasts I SoundCloud I Spotify

The real problem is the fragmentation

BILL describes its target market as the “Fortune 5 million”: the large set of small and midsize businesses that don’t have internal IT shops or engineering teams but still need to run serious financial operations. These businesses have more software options than ever, but that abundance hasn’t translated into less manual work. “Customers end up skipping a lot of newer functionality because it doesn’t work that well together,” Cieri explains. “They do lots of things manually.”

Cieri frames BILL’s core mission around two things: returning time to finance professionals by automating the repetitive work, and improving financial outcomes by helping businesses make better decisions about how they move money.

The trust barrier is part of the equation too. SMBs sitting at different points on the adoption curve – some comfortable leaning on technology, others not –  require a platform that can serve both ends of the spectrum without forcing anyone into a model they’re not ready for. “This is one of the things people are most nervous about,” Cieri says of AI in finance. “Having AI hallucinate, or something going wrong.” BILL’s response has been to lean hard into its compliance posture, security infrastructure, and licensing record as the foundation for earning that trust.

Task-based automation before agentic ambition

The conversation about AI in finance has tended to race ahead of what’s actually delivering value for customers. Cieri is candid about the marketing vs. deliverable gap. A few years ago, the narrative was about wholesale transformation of white-collar work. What’s actually worked, he says, is narrower and more practical. “Instead of this big bang change, we’ve found success with task-based automation of things that are just repetitive – things people do day in and day out that eat up a bunch of time.”

Two examples from BILL’s recent product work illustrate the approach. The first is a W-9 agent that handles the process of collecting supplier tax information ahead of the 1099 season – a task that might otherwise consume days or weeks of someone’s calendar. The second is in spend and expense management, where the goal is to make routine transactions essentially touchless: swipe, spend, and move on, with the system handling receipt capture and IRS compliance in the background.

These task-oriented solutions focus on the kind of friction that finance teams actually live with, and eliminating them compounds meaningfully over time. BILL measures the value here in time-per-transaction before and after, and the KPI is clear enough to inform what gets built next.

Reimagining what was already “solved”

One of the more interesting threads in Cieri’s thinking is the idea that innovation at BILL is about going back to problems the company already addressed and asking whether the original solution still holds up. “We’ve been building BILL for 20 years,” he says. “Is this still needed? If we were to do this today, with a bunch of smart people starting in a garage, would we build it that way? Probably not.”

The internal framing Cieri uses is “reinvent and reimagine” – a lens the product team applies to major components of the platform that were built under different assumptions about how software gets used. Some core assumptions have changed though: those systems were designed for human operators. Now the base axiom is that the human operator becomes more of a check, an exception-handler, coaching the AI that does the day-to-day execution. Building for that change means rethinking UI, workflow logic, and the degree to which customers can dial automation up or down.

This recalibration is happening at the same time BILL is managing a broader organizational transition. In May 2026, CEO and founder René Lacerte outlined the company’s direction as it moves through this next phase. The company also announced a set of leadership appointments designed to support its transition toward becoming an AI-native company – changes that reflect how seriously BILL is taking the structural rethinking of how financial software gets built and used.

Building AI for a high-stakes domain

Finance is a domain where the cost of AI error is immediate and concrete. Cieri’s team has built a shared AI platform over the past 12 to 18 months that sits on top of a common data lake, with an orchestration layer that routes different tasks to different LLMs depending on what’s required. The development model started centralized – weekly meetings, a unified AI roadmap, tight coordination – and has since moved toward a decentralized structure where individual product teams build agents on top of the shared platform. The next chapter, Cieri says, involves centralizing again around multi-agent orchestration: sequences of tasks that hand off between agents based on how earlier steps were resolved.

Validation is taken seriously. BILL uses proprietary evaluation frameworks to score AI efficacy, particularly for non-deterministic outputs where there’s no single right answer. Target accuracy rates run close to four nines for sensitive operations. Customer satisfaction and time-savings metrics are tracked alongside technical performance, and token cost is increasingly factored into the equation as the platform scales.

“We have 20 years of data. We’ve moved over a trillion dollars,” Cieri says. “That data, when you mine and leverage it correctly to train and prompt AI, gives us the right to encode bills better than anyone else, sniff out fraud, fat-fingered bills, and missed payments better than anyone else.” That data corpus is what makes the platform’s AI outputs demonstrably different from what a general-purpose LLM could produce, with context specificity visible at the moment of execution.

Sequencing the automation roadmap

One of the more careful distinctions Cieri draws is between workflow automation and payment automation. BILL has moved aggressively on the former – reducing the manual overhead that surrounds financial transactions without touching the transactions themselves. On the latter, the company is more deliberate. “We’re still building trust and the right to automate more of the payment side,” he says. “Earning the trust to move money agentically – that might be chapter two, chapter three.”

This sequencing reflects a broader philosophy about how to earn the right to do more. Activation in the first six months is a key metric: are customers actually running their bills and transactions through the platform, or did they sign up and drift back to old habits? From there, the goal is to expand share of wallet and product adoption, pulling in expense management, procurement, and other surfaces once the core accounts payable relationship is established.

On the product strategy side, Cieri describes a framework-driven approach to deciding where to take big swings versus where to improve incrementally. “Right now we’re in the “bigger innovation, take bigger swings” phase,” he says, “because the technology unlock is incredible, and the speed at which the tech continues to evolve leads us to believe there are big swings to take.” That posture will eventually rebalance, the company will need to consolidate and deepen what it builds, but for now, with the pace of AI development still accelerating, BILL is betting on moving fast on new ground.

How J.P. Morgan Payments eliminated 13 billion keystrokes a year by automating the paper behind payments

The payments industry likes to measure progress in milliseconds. Real-time rails, stablecoins, and instant settlement dominate the conversation. But for many businesses, the biggest source of friction is everything that surrounds the payment itself.

For J.P. Morgan Payments, that friction still arrives in envelopes.

In 2025 alone, the bank processed roughly 480 million checks and payment documents through its lockbox network. Behind every payment was a mix of invoices, remittance slips, handwritten notes, folded documents, staples, and countless formatting variations that traditionally required human intervention.

Before automation, processing that volume meant employees performed roughly 13 billion manual keystrokes every year.

Teaching AI to handle the messy middle

Rather than trying to eliminate checks that still account for about 25% to 26% of outgoing and incoming B2B payments in the U.S., J.P. Morgan Payments focused on eliminating the work they create.

The bank rebuilt its lockbox platform in 2020 with AI embedded into its core workflows. Once payment documents are scanned, computer vision and machine learning extract payment information, validate business rules, and review documents automatically. More recently, large language models have been added to support increasingly complex exception handling.

J.P. Morgan Payments’ tech systems can now process more than 4,000 envelope and document permutations, while the AI processing platform now achieves over 99.999% accuracy in document data extraction and business rule validation.

In 2025, the bank extended that automation into the physical world, deploying robotics at its lockbox facility that open envelopes, extract checks and invoices, unfold documents, organize paperwork, and prepare everything for AI processing.

“By investing in robotic and AI technology to improve our lockbox operations, we are automating the most labor-intensive tasks of the process, freeing our team to focus on more complex, higher-value decision-making,” said Michelle Conklin, Head of Receivables and Public Sector at J.P. Morgan Payments.

The robots were initially deployed at a single site for testing. Following a successful first deployment, they are being further refined and will return later this summer as part of the bank’s phased deployment approach.

Why this matters beyond paper

Checks remain a meaningful part of the U.S. payments ecosystem, particularly in B2B receivables. The real operational challenge is the manual work required to convert paper into usable financial data.

For treasury and finance teams, settlement is only one step in the process. Payments still need to be matched to invoices, reconciled against receivables, and reflected accurately in accounting systems before they become operationally useful.

“Moving dollars is only half the story,” according to Conklin. The other half is ensuring payment data is accurate and actionable the moment funds arrive, helping businesses reduce days sales outstanding (DSO), improve working capital, and accelerate reconciliation.

When payments become information problems

Checks have survived for so long because businesses built decades of workflows around them.

What’s changing now are the economics of processing. AI has reached a point where it can interpret thousands of document variations, extract meaning from unstructured data, and automate work that previously required human intervention.

Going forward, some of the biggest productivity gains across financial services may come from making legacy payment workflows machine-readable.

Read the deeper dive here.

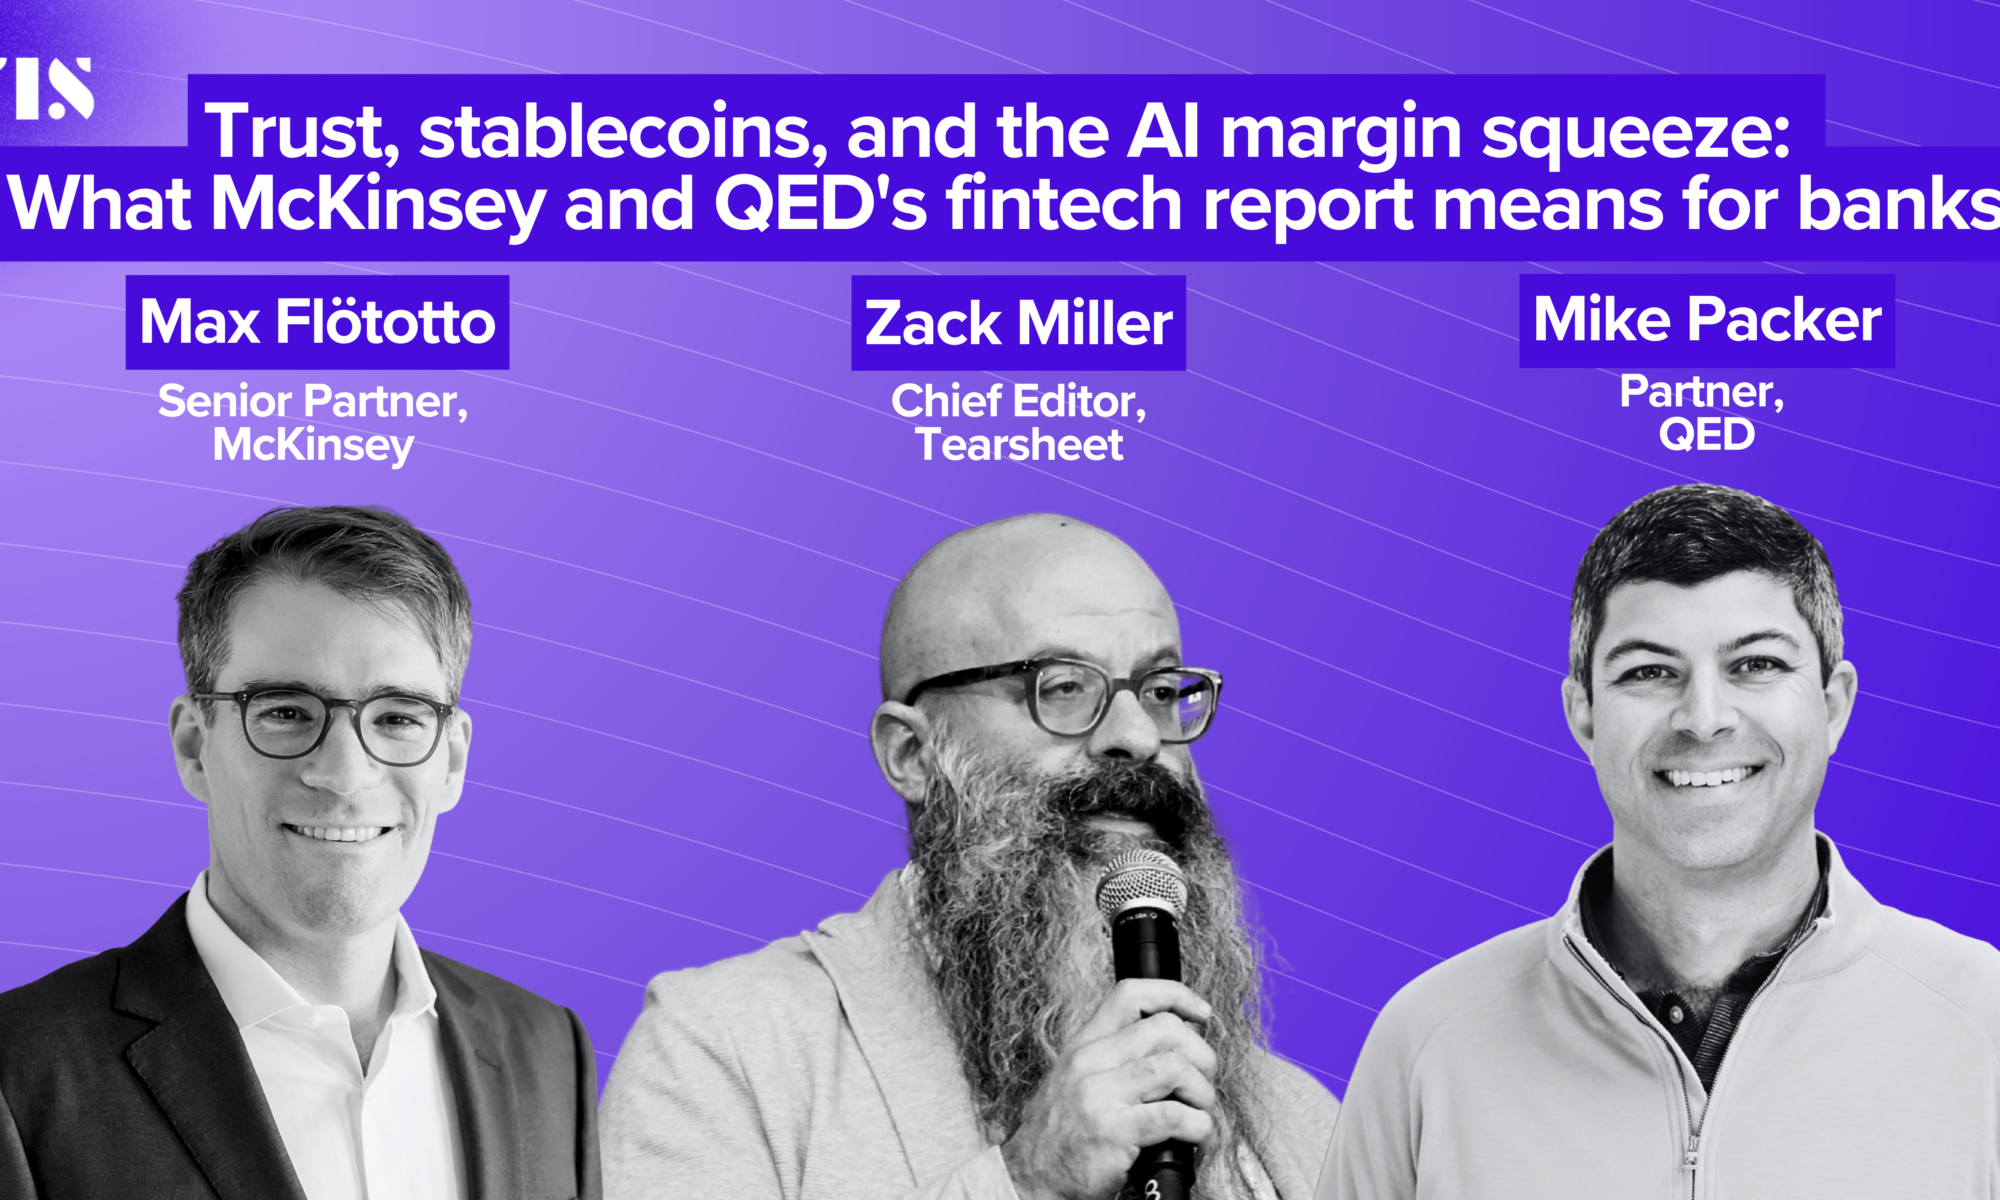
Trust, stablecoins, and the AI margin squeeze: What McKinsey and QED’s fintech report means for banks

Fintech just lived through four distinct ages — pioneers, growth-at-all-costs, the 2021-22 hype cycle, and the brutal reset that followed. Now we’re in a fifth: bigger, more profitable, and more disciplined than any version that came before it. Stripe’s reportedly eyeing a six-figure IPO. Fintech listings tripled investor appetite this year. And yet talk to anyone who lived through 2021, and they’ll tell you this doesn’t feel anything like that boom.

To make sense of that contradiction, I sat down with the authors of a new joint report from McKinsey and QED Investors — two firms that sit on opposite sides of the table from the fintechs they study. Max Flötotto is a senior partner at McKinsey, where he leads the firm’s global retail banking practice and coordinates its fintech work across Europe. Mike Packer is a partner at QED, leading growth-stage investing globally for a firm that’s been backing fintech since its earliest days, nearly two decades now.

We dig into the report’s biggest findings: why the simplest version of banking — collecting deposits, making loans — is structurally at risk if customers start letting their own AI agents shop for the best rate; why fintechs have, for the first time, actually overtaken incumbents on trust in Europe, even as banks ha ve closed much of the product gap; and the massive spread in how seriously banks are actually taking AI, from “talking about thinking about it” to rebuilding their entire operating model around it.

We close with each of them picking the one trend out of six in the report that they think matters most for the next decade.

Max, Mike, welcome to the show.

Watch the episode


Listen to the full podcast

Subscribe: Apple Podcasts I SoundCloud I Spotify


Top-line Takeaway: AI, stablecoins, and fintech are often discussed as separate trends. This conversation argues they’re becoming one story. McKinsey and QED Investors contend that banking’s next competitive advantage will come from rebuilding operating models around AI, earning trust that rivals incumbents, and preparing for a world where money increasingly moves in real time. The bigger risk may be AI reducing banking itself to a commodity, forcing incumbents to compete on efficiency, distribution, and customer relationships rather than products alone.


Read the whole transcript (for TS Pro subscribers)

Where the report’s authors actually agreed and disagreed


What Fifth Third’s invitation to Project Glasswing says about the bank’s role in the financial system

Banking scale has been measured in assets, deposits, and branches. In 2026, another metric may be emerging: how much of the country’s financial activity would be disrupted if your systems stopped working.

That helps explain why Fifth Third’s recent invitation to Anthropic’s Project Glasswing holds importance. The bank has been invited into an invite-only cybersecurity program that grants a small group of vetted partners early access to the Claude Mythos Preview model.

Project Glasswing is a controlled-access initiative, bringing together a limited set of trusted organizations to test advanced AI systems in real-world security environments. The focus is on detecting and helping remediate critical software vulnerabilities at scale. Anthropic has said its Mythos models have already identified more than 10,000 vulnerabilities in widely used, systemically important software, and Glasswing extends that capability to selected partners before wider deployment.

That signals the direction Fifth Third is moving in. The same week, it rolled out a refreshed small-business platform to over 240,000 customers.

From banking customers to orchestrating flows

Fifth Third’s new small-business offering is a digital banking upgrade built around speed and access – Early Pay brings forward incoming funds, digital lending speeds up capital access, Zelle shortens payment cycles, and tap-to-pay streamlines merchant acceptance. The unifying theme is flow.

After its merger with Comerica, Fifth Third now ranks as the 9th-largest U.S. bank with about $294 billion in assets, strengthening its footprint across several fast-growing commercial markets.

Scale matters, but operational density matters more. The more businesses, payrolls, government programs, and payment streams flowing through a bank, the more consequential its systems become.

Why Anthropic cares

Bryan Preston, Fifth Third’s Chief Financial Officer, attributed the bank’s inclusion in Project Glasswing to its role in administering Direct Express, processing payments for U.S. Customs, and handling large volumes of payroll activity across the country. 

These are not ordinary banking products. They are payment flows tied to government programs, public-sector operations, and employer payroll systems that millions of people depend on.

Basically, Fifth Third was selected because disruptions to its systems could ripple far beyond the bank itself.

The emerging hierarchy of banks

Size used to define banks – now their function does. The key distinction is between customer-facing banks and those that operate financial infrastructure.

Fifth Third’s recent announcements suggest it is moving toward the latter category.

The broader shift is that regional banks are increasingly being discussed alongside infrastructure providers, payment operators, government disbursement systems, and national cybersecurity efforts. Increasingly, a bank’s importance may be measured by systemic dependence on how critical an institution is to keeping the financial system smoothly functioning.

J.P. Morgan Payments’ Michael Lozanoff on why agentic commerce can’t scale without governance

J.P. Morgan anticipates that success in agentic commerce will not come from the smartest AI agents, but from the institutions building the governance, permissioning, and trust infrastructure that supports them.

When capability is no longer the bottleneck

Michael Lozanoff, Global Head of Merchant Services at J.P. Morgan Payments, believes the capability question is largely being solved. “Capability without governance is the next challenge,” he notes.

Agents today can already perform end-to-end commerce tasks: discover products, evaluate options, and complete checkout flows. What is still uncertain is whether those actions can be trusted at scale.

A prompt like “reorder office supplies” can produce very different outcomes depending on how “usual” is interpreted, whether cost or availability is prioritized, or how incomplete instructions are resolved.

“The agent may be perfectly capable of executing that,” Lozanoff says. “But what happens when the item is out of stock, and the agent prioritizes availability over cost? Or when it interprets ‘usual’ differently than the consumer intended? The intelligence was there. The governance wasn’t.”

When the human disappears from the transaction

Traditional payment systems were built on a simple premise: a human decides, a human authorizes, a human pays. Agent-driven transactions don’t behave that way. When an AI agent acts on behalf of a user, it disrupts fraud models, authentication logic, and the way risk is interpreted. 

“The shift we’re building toward is moving risk signals away from consumer browsing toward authenticated agent identity and authorization context,” Lozanoff explains. “Is the agent known? Is it permitted to act? Is it operating within the policy it was given?”

That means having a more continuous approach to risk that spans discovery, checkout, and post-transaction monitoring -– following the agent throughout the entire interaction.

Merchants lose visibility

On the merchant side, the challenge is different but equally fundamental: visibility.

Retailers are used to understanding how customers arrive, their search patterns, browsing behavior, and checkout flows. Agentic commerce obscures much of that. Merchants are already raising concerns around fraud, liability, and intent verification. “They also want a clear way to verify that intent if something goes wrong,” Lozanoff notes.

J.P. Morgan’s guidance is to start with the basics of data structure. If product data is not machine-readable, agents cannot reliably discover or compare it. Poor cataloging removes products from the decision surface.

“Clean, rich product data is the foundation,” Lozanoff says. “Without it, agentic commerce doesn’t work for the merchant, regardless of how good the agent is.”

The unresolved liability question

The hardest problem sits at the intersection of intent and responsibility. If an agent follows instructions but produces an unwanted outcome, who is responsible?

Merchant, bank, consumer, or agent provider? “There aren’t clean answers quite yet,” Lozanoff notes.

J.P. Morgan’s view is that a stronger authorization context can reduce ambiguity with the support of granular customer consent, explicit limits, and merchant-defined constraints that make intent clearer before execution. 

From intelligence to governance

As AI becomes more accessible, intelligence stops being the key differentiator. What matters instead is governance: who the agents are, what they can access, and what they are permitted to do under enforceable rules.

“A conversation the broader ecosystem needs to have is around the consistent set of industry standards that will shepherd responsible growth, such as clear ways for agents to identify themselves and transact safely, and common approaches to risk, data sharing, and liability,” Lozanoff says.

The 3-Min Read: Why Anthropic is becoming AI’s reference point

In the span of just twelve months, Anthropic has shifted from being one of several frontier AI labs to a gravitational center of the industry. The change is driven by a compounding sequence of capital inflows, enterprise adoption, and infrastructure-scale positioning that increasingly resembles platform formation rather than startup growth.

The clearest signal came on May 28, 2026, when the company closed a $65 billion Series H round at a $965 billion post-money valuation, briefly making it the world’s most valuable AI startup ahead of OpenAI. Its valuation has climbed rapidly from $183 billion in Series F to $380 billion in Series G, and nearly doubled again in the latest round.

This momentum is being driven by strong enterprise demand. Anthropic now reports an annualized revenue run-rate above $47 billion, largely fueled by adoption of its Claude models in coding and agent-based workflows. Increasingly, Claude is being embedded into production systems where productivity gains translate directly into cost reduction.

Coding has become the primary growth engine, marking the second signal. Software development is now the operating layer of modern enterprises. As Claude moves deeper into these workflows, Anthropic’s identity shifts from product builder to infrastructure provider.

But rapid growth comes with pressure. The company is close to its first operating profit, yet compute costs remain heavy. In Q1 2026, it spent 71 cents for every dollar of revenue on compute, expected to improve to 56 cents in the next quarter. Efficiency is improving, but only because demand is rising fast enough to absorb training and inference costs. Yet Anthropic has also cautioned that planned infrastructure investments could make profitability difficult to sustain over the full year. This tension between scaling demand and managing compute costs is now a pressing challenge for frontier AI companies. Bankers and investors are increasingly focused on Anthropic’s token economics and compute costs, worried that rising AI usage costs could pressure margins and make it harder to justify its valuation after an IPO.

Which leads to the third signal: capital structure alignment. On June 1, Anthropic confidentially filed for an IPO, working with Morgan Stanley and Goldman Sachs, alongside J.P. Morgan Chase. Anthropic leadership notes that frontier model training requires sustained access to large-scale capital, and public markets are structurally better suited to that need. 

Alongside expansion, Anthropic is also moving carefully on safety and control. Through Project Glasswing, the company has scaled access to its Mythos cybersecurity model from roughly 50 organizations to 150 across more than 15 countries. The system has already helped identify more than 10,000 high- or critical-severity vulnerabilities in widely used software.

The same capabilities used to detect vulnerabilities could also be used to exploit them, so the model distribution is limited to vetted partners. Expansion happens through controlled channels rather than open release.

Anthropic is also exploring broader deployment of the model through discussions with the EU cybersecurity agency ENISA, which could extend access beyond the US and UK for the first time – widening its user base through institutional gatekeepers.

What Anthropic is becoming

These shifts show Anthropic evolving into three roles:

  1. A capital-scale company moving toward public-market size with trillion-dollar ambitions.
  2. An embedded intelligence layer inside enterprise systems, especially in software development.
  3. A controlled provider of high-risk AI systems, distributed through strict governance frameworks.

Anthropic is trying to scale and contain at the same time. The broader question is whether the economic and governance structures around frontier AI can scale at the same pace as the systems they are now trying to contain.

Letter from the Editor: Finance is becoming ambient infrastructure underneath everything, but what are we giving up


Introducing our new ‘Letter from the Editor’ series featuring exclusive insight and opinion-driven analysis from Tearsheet editor Sara Khairi. The focus is to link ideas, question assumptions, and track shifts across both mature and emerging trends in financial services.

This will soon be PRO-exclusive content. Subscribe to PRO so you don’t miss out on future exclusives.


Issue # 3

For years, we’ve talked about digitization as if it were ‘the’ destination. We built apps, dashboards, APIs, embedded widgets, AI copilots. We optimized access, sped up onboarding, and compressed decision times. 

Doing this made finance feel easier but not necessarily more present. It still shows up in bursts when you open an app, check a balance, apply for credit, or reconcile at the end of the month. The system is faster, but it remains episodic. You still go to it rather than it staying with you.

That model is starting to give way, and that is what I want to talk about today. Financial services are starting to move beyond the old request-response model. In its place is an incoming, always-present layer that interprets context in the background, responds dynamically, and participates alongside the user instead of merely waiting for input.

We’re already seeing the early contours of this across different parts of the stack. The recent Plaid-OpenAI integration around ChatGPT is one of them. On the face of it, it resembles another AI-powered personal finance assistant: users connect accounts through Plaid, and ChatGPT responds with contextual insights drawn from live financial data like budgeting support, spending analysis, debt management, savings recommendations.

Useful, sure. But also slightly too small as a way of describing what’s actually changing.

Historically, financial experiences lived inside financial products. What OpenAI is effectively testing is finance embedded inside a conversational intelligence layer people already inhabit constantly throughout their day.

That changes the center of gravity. The banking app is no longer the primary interface; conversation increasingly is. And conversation doesn’t behave like traditional software. It doesn’t reset every time you open it. It carries context, stretches across workflows, and stays present while decisions are forming.

This is why I think the industry narrative around “AI in finance” only captures part of what is happening and understates the shift underway; what is actually emerging is more like always-on financial interpretation.

And this evolution didn’t start with ChatGPT.

Embedded finance already moved things in this direction by pulling financial functionality closer to behavior. Shopify embedded capital and payments directly into commerce. Klarna and Affirm brought credit into discovery and intent, not just checkout. Banking capabilities stopped behaving like standalone destinations and started merging into workflows.

Emerging AI systems are what push that logic further.

Agentic AI in wealth and banking, payments and commerce

What’s taking shape now is embedded interpretation. Systems are increasingly expected not just to process transactions, but to understand patterns, maintain continuity across fragmented financial activity, surface relevance proactively, and eventually participate in decisions.

That is a much bigger transition than another chatbot layer. Previous fintech cycles optimized transactions; this one is beginning to optimize financial cognition itself. That changes the competitive landscape in ways I don’t think incumbents are fully prepared for yet.

Historically:

  • Banks owned accounts
  • Fintechs owned experiences
  • Now AI systems are positioning themselves to own interpretation

That third layer may become a highly valuable layer in financial services going forward. Because once a system becomes the place where users continuously interpret financial reality, every action – spending, saving, borrowing, investing, planning – flows through that layer.

This is why the Plaid-OpenAI partnership is gaining eyeballs, even if the product itself evolves, never fully scales as imagined, or struggles commercially. Some skepticism around the launch is warranted, though. Transaction data is incomplete, advice without execution still leaves friction, and consumer demand for AI-powered financial guidance does not necessarily mean they will pay for it at scale. Additionally, behavioral finance has historically been much harder than fintech companies assume or product demos suggest.

But those critiques mostly speak to product viability. The deeper shift is interface migration.

Finance is moving out of banking environments and into persistent intelligence systems that people already use to organize information, interpret decisions, and navigate daily life.

We can also see this in the way AI is being introduced into core banking and wealth workflows. Take the idea behind capabilities like Citi Sky

Across these examples, AI isn’t acting as just an assistant added on top of finance but as a bridge or layer between raw activity and meaning. This is what distinguishes the current AI wave from everything that came before.

We’ve had digitization. Then automation. Then embedded finance. Each wave made finance more efficient, more distributed, and in some cases less visible. But this is about continuity. Continuity is not just availability, so to speak. It is context preserved over time, understanding what changed, what matters now, and what is likely to matter next, without requiring the user to rebuild the frame each time they interact with the system.

That’s a very different expectation to place on financial infrastructure. And it also reorders what ‘good’ actually looks like. 

For years, the goal was to make finance invisible. API-first banking accelerated that by modularizing financial capabilities so they could appear anywhere. Embedded finance distributed those capabilities across commerce, payroll, and software ecosystems. Now AI introduces systems that continuously interpret financial context without being asked.

More intelligence does not automatically mean more clarity

A system can be highly responsive and still create noise. It can surface constant insights while still leaving users responsible for stitching meaning together. And in finance, that stitching has always been the user’s burden.

The ‘always-on’ narrative is often labeled as progress, but its real impact turns finance into an ambient layer.

That shows up in concrete ways in how systems begin to behave. A portfolio that doesn’t just report performance but contextualizes movement in relation to goals and macro conditions. A banking interface that doesn’t wait for queries but flags emerging patterns in cash flow or risk. A wealth tool that doesn’t just answer questions, but anticipates the framing of the question itself.

At this point, the line between ‘user action’ and ‘system interpretation’ starts to blur. And that is where incumbents face a harder challenge.

Financial institutions have always been strong at producing answers. What they are now being asked to build is continuity of understanding. Not correctness in moments, but relevance over time. That is a different operating model. And it is not yet clear that the industry is structurally set up for it.

There’s also a deeper question underneath all of this. If finance becomes continuously present – interpreting, explaining, and responding in real time – what happens to the moments where users used to pause, think, and decide?

Historically, friction was not always a flaw. Sometimes it was the point where attention was forced. A moment to pause, compare, reconsider. Remove too much of that, and you don’t just reduce friction; you potentially reduce visibility into the decision itself.

This is where the industry’s obsession with ‘seamlessness’ starts to feel questionable. Seamlessness feels effortless, but it is not neutral in effect.

This is not an argument against AI in financial services. It’s more of a reminder that presence changes behavior. Systems that are always available tend to become systems that are always shaping.

And that is the real design problem ahead: how much intelligence should stay in the foreground, and how much should disappear into the background until it is needed.

Because the endgame, at least as I see it, is not a constant stream of financial outputs, nor simply better UX or faster payments. It is about moving away from fragmented financial management and toward a system that understands a person’s financial life as it unfolds without overwhelming them.

– Sara

[This will soon be PRO-exclusive content. Subscribe to PRO so you don’t miss out on future exclusives.]

Citi’s AI teammate signals a new model for wealth management

Citi has launched an always-on, AI-powered member of its Wealth team that can engage in conversation, respond in real time, and surface insights instantly.

If AI becomes the front door to wealth management, banks don’t just face a UX problem; they face a structural one as well. How do you keep advice personal under regulatory constraint, and what happens to the human advisor when the interface is no longer human-mediated?

Citi is testing that question with Citi Sky, built with Google Cloud and Google DeepMind.

Citi Sky lets clients talk to it at any time. It delivers real-time market, portfolio, and opportunity insights, shifting wealth management away from scheduled interaction and toward continuous availability. Voice and multimodal interfaces, powered by DeepMind models, push it further into a conversational experience rather than a static dashboard.

But the guardrails are clear. Citi Sky does not execute trades. It interprets, explains, and prepares, while human advisors remain the final point of control.

Underneath that product positioning sits a harder engineering problem.

For Google DeepMind, the challenge is not building intelligence, but controlling it. Generative AI systems are inherently non-deterministic – the same input can produce different outputs, which makes consistency difficult in regulated financial environments.

JP Suh, Product Manager at Google DeepMind, says the fix lies in system design, which includes strict routing, Citi-specific tool use, and tightly bound context to ensure the agent operates within defined limits inside Citi’s environment.

Personalization is deliberately kept separate from model reasoning. Instead of being embedded in training, it is applied at runtime through controlled data access, a structure meant to preserve relevance while reducing hallucinations and keeping compliance intact.

What the move signals

Citi Sky signals that wealth management is moving from a pull model to a presence model.

Advice is no longer something clients ‘go to’ on a schedule. It becomes present in the background and is always available, always responding.

That compresses advisors’ surface area and changes their rhythm in the relationship. Routine interaction fades, replaced by fewer but higher-stakes moments where judgment, context, and trust actually matter.

Wealth management is slowly shifting toward a model where intelligence is continuous and human involvement becomes more selective, intentional, and contextual.

What Citi Sky says about the reinvention of client relationship models in wealth management

Wealth management follows a familiar rhythm where advisors book meetings in advance, send market notes after the fact, and make decisions that move at the speed of inboxes and calendars.

Citi Wealth is aiming to break that cadence with Citi Sky, built in partnership with Google Cloud and Google DeepMind. The bank describes it as an always-on AI-powered member of the Citi Wealth team that can talk, respond, and surface insights in real time.

Citi’s Head of Wealth, Andy Sieg, says the intent is to move away from the fragmented experience clients have lived with for years. “For decades, managing your financial life meant navigating apps, calls, and meetings,” he said in a press release. “With Citi Sky, you simply ask – and act. This is the shift from interface to intelligence, from transactions to outcomes.”

The Citi-Google Cloud relationship extends beyond a typical vendor arrangement. While Google provides the underlying infrastructure and AI stack, the collaboration evolved into a deeper co-development effort. Teams from Google Cloud and Google DeepMind worked alongside Citi engineers to shape Citi Sky’s architecture, conversational experience, and guardrails, while Citi retains ownership of the client experience, data, and decisioning layer.

From infrastructure modernization to client-facing intelligence