

‘Stablecoins and tokenized deposits will be complementary, not competitive’: BNY’s Carl Slabicki on the next chapter for treasury
- APIs are becoming the go-to tool for banks in stitching together legacy platforms and emerging ones, reflecting deeper shifts in banking and its underlying business model.
- Carl Slabicki, Executive Platform Owner, Treasury Services at BNY, unpacks the key themes and how New York-headquartered BNY is moving decisively on them.
The push toward an always-on, digital-first economy has compelled incumbent institutions to reassess how money flows. APIs sit at the center of that rethink, transforming payments from a calendar and timezone-bound process into one that can run continuously.
This year, Citizens Bank refreshed its open banking API. BNY is taking a parallel path: broadening treasury services with initiatives in FX settlement, blockchain, stablecoins, and tokenized deposits. Adding these as layers on top of treasury services builds on BNY’s existing treasury services without rebuilding the whole stack.
APIs are becoming the go-to tool for banks in stitching together legacy platforms and emerging ones. However, their impact runs deeper. They spotlight key themes about the changing nature of modern banking and the business model underpinning financial services.
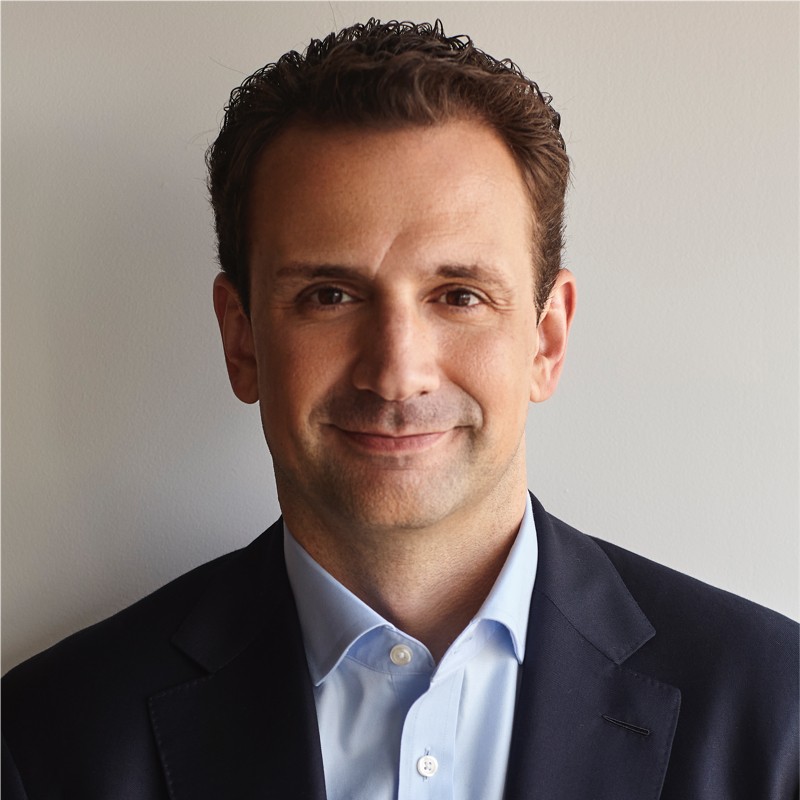
Carl Slabicki, Executive Platform Owner, Treasury Services at BNY, breaks down these themes and how New York-headquartered BNY is moving decisively on them. He also sheds light on where banks need a sharper lens when beginning their API journey.
The story banks often get wrong about API adoption
The biggest misconception about API adoption is that it’s simply tactical “plumbing” for isolated functions instead of recognizing it as the foundation of a platform-centric business model, says Slabicki.
Many institutions bolt point-to-point APIs onto legacy systems and services without rethinking the overall architecture or questioning the core capabilities being delivered. As a result, these implementations deliver short-term convenience but often fail to scale or unlock new revenue streams.
On the other hand, banks that use APIs for always-on, end-to-end services can create a value-added experience as a platform by offering self-serve developer portals where clients can build their own experiences.
“This approach not only accelerates internal agility but also creates marketplaces of embedded finance and analytics offerings, reshaping treasury from a cost center into a dynamic, monetizable ecosystem,” notes Slabicki.
BNY’s treasury strategy: Keeping people in the loop with strategy, customer engagement, and operational adaptability
BNY’s treasury strategy ties the three threads together: digitization clears away paper-based friction, APIs open up core functions as always-on services, and blockchain innovations like stablecoins and tokenized deposits expand what treasurers can actually do with that connectivity.
The balance comes from pushing into digital without losing sight of human judgment and relationships.
Slabicki underscores the need for an orchestration layer that fuses rules-driven engines with human checkpoints to ensure automation and APIs enhance efficiency without eclipsing human insight.
BNY automates routine work, like credit limit checks, cash flow sweeps, through APIs for round-the-clock execution. But when patterns fall outside predefined thresholds or new opportunities surface, the system triggers real-time alerts and dashboards that arm relationship managers with curated data to step in and advise clients directly.
Beyond straight-through processing, Slabicki sees the real upside in treasury data coming from predictive and prescriptive analytics, enabling clients to sharpen decisions on cash flow, FX, and how to best route payments for cost and speed.
“Turning bulky data sets into actionable insights not only deepens client engagement but also opens new analytics-as-a-service revenue lines,” he notes.
Early entry points for blockchain and tokenized deposits in treasury
Slabicki believes stablecoins, blockchain, and tokenized deposits are transformative: they turn fiat and collateral into programmable, on-chain assets that settle around the clock.
“This opens new possibilities in treasury and capital markets: intraday liquidity optimization, supply-chain finance, real-time corporate payments, and embedded finance, by collapsing traditional netting cycles and manual reconciliations into secure, auditable ledger entries,” he asserts.
These innovations are expected to sit alongside existing rails as API-first overlays and interoperability layers. Slabicki anticipates that banks and market infrastructures are more likely to link token networks into systems like SWIFT, FedNow, RTP, and RTGS through compliant bridges and gateways.
In practice, that could mean a corporate treasury sweeping excess balances into a regulated stablecoin after markets close, then automatically shifting back into central-bank money as they reopen – retaining cash flows, compliance, and network effects while getting final settlement.
“Over the long run, Stablecoins and tokenized deposits will be complementary, not competitive,” adds Slabicki.
As more issuers, custodians, and wallets agree on shared standards, Slabicki expects wallets and consortium chains to begin bridging instant payments, blockchain rails, and legacy systems. Instead of tearing out what works, the future looks more like a hybrid upgrade – faster, clearer, and more adaptable. In essence, it’s about rewiring the world’s money pipes to unlock new revenue, raise service benchmarks, and change how value flows across borders.
[Sidebar:] Cross-border payments are speeding up, but not without turbulence
“We’re already seeing real-time cross-border settlement in action,” says Slabicki.
One-leg-out models tie legacy correspondent networks to SWIFT and local instant payments, such as Australia’s NPP network, which operates 24/7/365 in near real-time. That progress demonstrates that the building blocks – prefunded nostros, ISO 20022 messaging, and enhanced SWIFT SLAs – can now be orchestrated to support fast and reliable settlement.
The challenge is scaling that patchwork globally without fragmenting cash flow or compliance. Jurisdictions still interpret ISO 20022 differently, regulatory rules vary, and operating-hour extensions only mask intraday funding strains and exception workflows.
“To address this, banks and market infrastructures must align on messaging semantics, harmonize cut-off policies, and converge regulatory requirements through industry collaboration,” explains Slabicki.
He sees the future less as a rip-and-replace exercise and more as a hybrid build, enhancing one-leg-out corridors while using APIs and shared compliance layers to knit together SWIFT, RTGS systems, local instant networks, and emerging tokenized rails.
“By building on proven success stories and standardizing the rulebooks behind them, we can expand instant settlement into new corridors — and ultimately achieve truly seamless, 24/7 cross-border value movement,” asserts Slabicki.