
10-Q, Member Exclusive

What’s Left in the Shadows: How 90-year-old Webster Bank punches above its weight by combining purpose with profitability

  • Not your typical regional bank, Webster combines serving local consumers and SMBs with a strategic move into healthcare finance.
  • In today’s 10Q edition: What’s Left in the Shadows, we shine a light on the less-talked-about publicly traded names in the industry that do their own thing but remain integral to the banking ecosystem.
close

Email a Friend

What’s Left in the Shadows: How 90-year-old Webster Bank punches above its weight by combining purpose with profitability

    A storied beginning and a forward-looking purpose


    In 1935, with $25,000 borrowed from friends and family, Harold Webster Smith founded the First Federal Savings and Loan Association of Waterbury, Connecticut, to help people build homes during the Great Depression. His vision was that banking should serve the people around you, not just the bottom line.
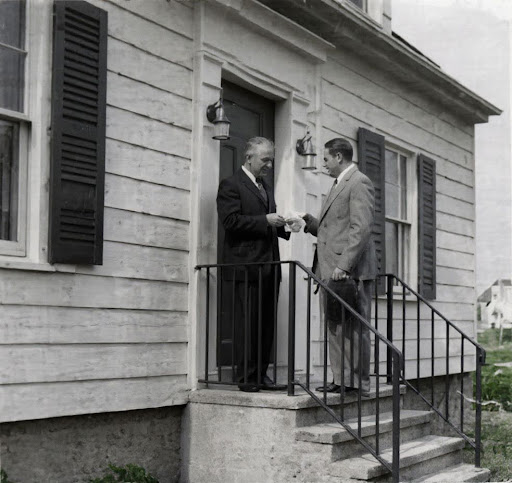
    Webster Bank founder Harold Webster Smith (right) makes the bank’s first loan to Joe Baltrush in December 1935 on the steps of his Waterbury home at 114 Chambers Street. Source: Webster Bank

    The organization was later renamed Webster Bank when it went public in 2002 and converted to a national commercial bank in 2004, enabling broader service offerings while largely preserving its regional identity. 

    Today, Stamford, Connecticut, serves as its headquarters, but its branches extend from suburban New York to Rhode Island and Massachusetts, giving it a solid regional footprint.

    Webster Bank (NYSE: WBS) remains true to its ethos: serving communities across the Northeast while moving billions of dollars of healthcare payments and powering fintech platforms behind the scenes. 

    Webster Bank’s evolution from a local thrift to a publicly traded commercial institution reflects a long-term focus. The bank serves clients across three key areas: commercial banking, consumer banking, and healthcare financial services.

    In today’s 10Q edition: What’s Left in the Shadows, we shine a light on the less-talked-about publicly traded names in the industry that do their own thing but remain integral to the banking ecosystem.


    subscription wall for TS Pro

    0 comments on “What’s Left in the Shadows: How 90-year-old Webster Bank punches above its weight by combining purpose with profitability”

    10-Q, Member Exclusive

    NVIDIA bought Hugging Face. What happens to banks when AI models become open?

    • NVIDIA’s acquisition of Hugging Face could give banks greater control and flexibility over the AI models they use.
    • But as AI models become more open, dependency could shift to the infrastructure powering them, creating new forms of vendor concentration and lock-in.
    Sara Khairi | September 14, 2026
    10-Q, Member Exclusive

    Fifth Third is trying to make a bigger bank feel simpler

    • Fifth Third is simplifying its lineup as it grows, giving customers clearer products built around specific financial needs.
    • Its broader strategy is to expand what the bank can do while making the user experience feel increasingly simple.
    Sara Khairi | September 11, 2026
    Banking, Member Exclusive, Podcasts

    Venture banking 3.0: How Stifel is rebuilding trust after Silicon Valley Bank

    • Stifel's Katya Kohen explains how venture banking is being rebuilt into what she calls 3.0 after Silicon Valley Bank's collapse.
    • She breaks down why bigger banks and neobanks each fell short of replacing SVB, and why venture debt has become essential capital for AI founders.
    Zack Miller | September 09, 2026
    Member Exclusive, The Quarterly Review

    The Quarterly Review: BNY’s Carl Slabicki is pushing toward practical innovation

    • Carl Slabicki is Head of Commercial for Global Payments & Trade at BNY, where he leads client strategy across payments, liquidity, and trade for the firm's global commercial clients.
    • This quarter, Slabicki is focused on connecting capabilities across BNY, driving practical modernization, and grounding conversations around digital assets and AI in client execution.
    Rabab Ahsan | September 08, 2026
    Member Exclusive, Opinion

    The infrastructure paradox: The better you become, the harder customers are to keep

    • Financial infrastructure is becoming part of the business itself, changing what customers are willing to outsource.
    • Providers now have to grow with their customers and keep expanding their value as those customers begin to question how much of the stack they should continue to outsource.
    Sara Khairi | September 04, 2026
    More Articles
